
Neogen (NEOG) Could Be 15% Undervalued As FDA Warning And Quarterly Loss Rattle Investors
Neogen stock reacts to FDA warning letter and quarterly loss
Neogen (NEOG) is under close watch after an FDA warning letter over contaminated HYCOAT product lots and a first quarter swing to a net loss, adding fresh scrutiny to the stock.
The FDA warning and first quarter loss hit a stock that had already run hard. The 90 day share price return was 29.16% and the year to date share price gain was 70.86%, while the 1 year total shareholder return of 113.95% contrasts with a 5 year total shareholder loss of 70.72%, suggesting strong recent momentum against a much weaker long term record.
Scan how other food and animal safety players are priced after Neogen's FDA setback and quarterly loss by reviewing the curated list of solid balance sheet and fundamentals (25 results).
Neogen just delivered a sharp swing to a quarterly loss and absorbed a serious FDA warning, yet the share price has surged over the past year. Are investors repricing the business, or simply chasing a sentiment reversal as potential valuation stretches are tested next?
Most Popular Narrative: 15% Undervalued
Neogen last closed at $11.96, while the most followed narrative pegs fair value at $14. The gap between those figures focuses attention on whether operational fixes and margin repair can offset fresh regulatory pressure from the FDA letter.
Operational improvements and automation at the new Petrifilm production facility, alongside targeted actions to reduce inefficiencies in sample collection and inventory management, are expected to drive gross margin and EBITDA margin improvements over the coming quarters as execution stabilizes and overhead absorption rates improve.
See why 5 investors see Neogen as 15% undervalued.
The fair value of $14 in that narrative is built on a discount rate of 8.05%, with an assumed profit margin moving from a current loss of $7.9 million toward 12.6% in several years and earnings of $112.7 million. Those inputs require investors to be comfortable with Neogen remaining unprofitable over the next three years according to current forecasts, while also assigning a future P/E of 34.5x to those 2029 earnings that is higher than the 24.6x currently cited for the broader US Medical Equipment group.
That framework also implies only modest revenue change from the current $870.4 million to $896.0 million by 2029, so most of the upside case hinges on margin repair rather than rapid top line expansion. With revenue growth running at 2.2% per year on forecasts that are slower than the wider US market at 13.8% per year, the narrative effectively asks whether operational clean up, portfolio pruning and higher quality earnings can justify a richer multiple on relatively flat sales.
For readers weighing the FDA warning alongside that valuation story, the tension is clear. Neogen is currently unprofitable, losses have grown at an annual rate of 70.9% over five years, the value score is 0 and management is still working through integration issues, yet the narrative-backed fair value assumes a shift to materially higher profitability over time.
Result: Fair Value of $14 (UNDERVALUED)
Still, if integration setbacks at the 3M Food Safety business drag on or if macro pressure keeps Animal Safety revenue under strain, the Neogen narrative could unravel quickly.
Find out about the key risks to this Neogen narrative.
Another View: Neogen looks pricey on sales
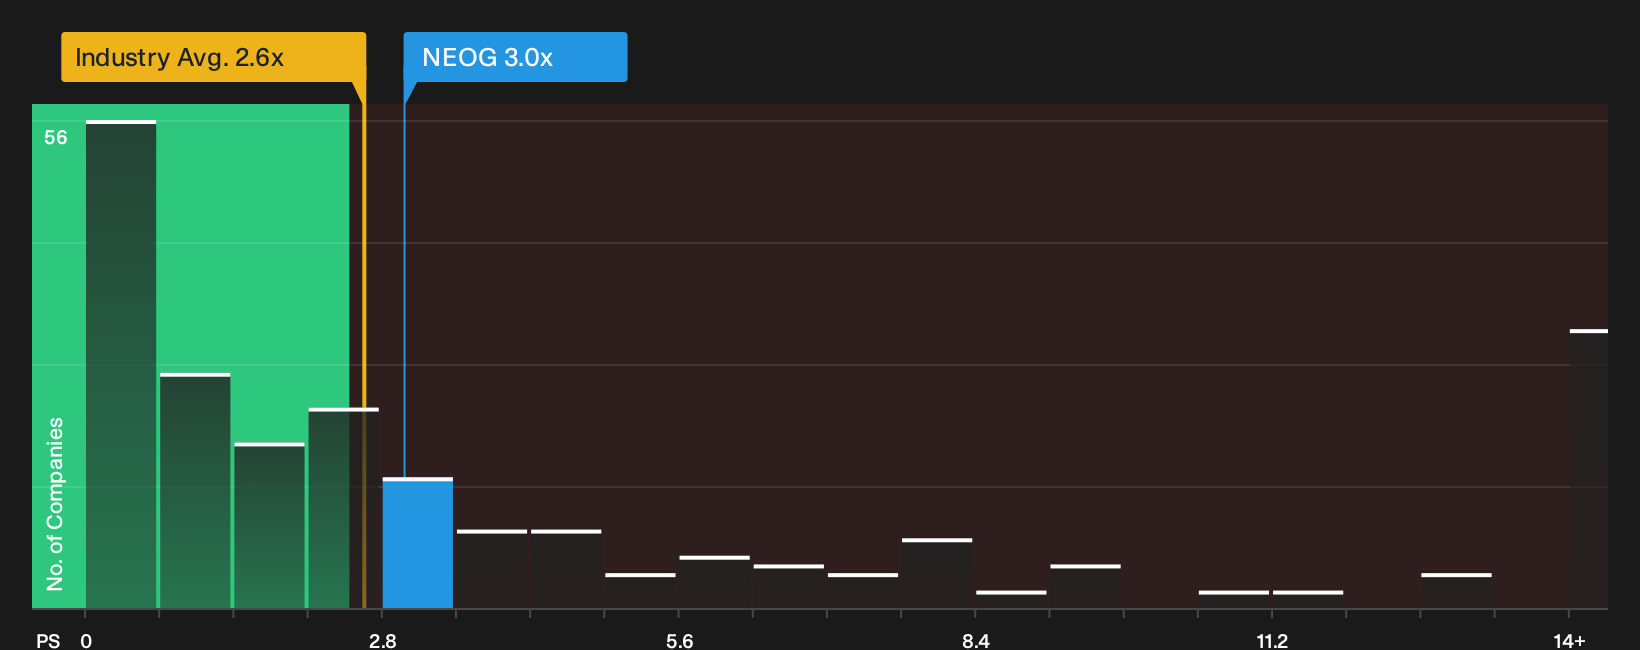
On one hand, the Neogen narrative argues the stock is 15% undervalued if margins eventually catch up to sector averages. On the other, the current P/S of 3x screens as expensive versus both peers at 2.4x and a fair ratio of 1.3x, which points to meaningful valuation risk if sentiment cools.
For anyone weighing those conflicting signals, it helps to see how that sales multiple lines up visually against peers and the fair ratio as a guide to where the market could move next, then decide which story feels more realistic for Neogen today. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this Neogen story feels conflicted to you, do not wait for a clean narrative to emerge before checking the numbers yourself and stress testing the assumptions. To see the specific red flag that keeps showing up in the data, start with this 1 important warning sign.
Looking for more Neogen investment ideas?
If the Neogen story feels finely balanced, broaden your opportunity set now by scanning focused stock lists that target specific strengths and risk profiles.
- Hunt for mispriced quality and see which companies screen as potential bargains using the 27 high quality undervalued stocks.
- Target resilient payers and review stocks that combine income potential with staying power through the 8 dividend fortresses.
- Prioritize resilience first and scan companies that aim for sturdier finances and lower risk using the 31 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com