
Morningstar (MORN) Could Be 17% Undervalued On Envestnet Platform Expansion
Morningstar (MORN) just moved its Morningstar Public/Private Select Series onto Envestnet’s platform, giving advisors on that system access to portfolios that blend public securities with private market exposure.
For context, Morningstar’s latest share price of $195.69 comes after a 3.45% 1-day share price return and 5.01% 7-day share price return, even though the 30-day share price return declined 6.55% and the year-to-date share price return is down 7.00%, while the 1-year total shareholder return has fallen 12.56%. This points to short-term momentum improving against a weaker longer-run outcome as investors weigh product rollouts like the Envestnet partnership against past performance.
Scan beyond Morningstar and see how other wealth and platform providers with similar themes are lining up in our curated list of list of solid balance sheet and fundamentals (25 results).
Recent gains put Morningstar back on investors’ radar after a tough stretch and a fresh Envestnet tie up. Do you lean into the rebound now, or wait for a cheaper entry as the valuation section unfolds next?
Most Popular Narrative: 17% Undervalued
Morningstar last closed at $195.69, while the most followed narrative anchors fair value around $236.67. The story being priced in assumes the business is worth meaningfully more than where the stock currently trades.
The integration of PitchBook private market data into AI platforms such as ChatGPT for Financial Services and Gemini Enterprise for Financial Services creates new data licensing and workflow subscription opportunities that can support higher revenue per user and improved margins as distribution scales.
See why 1 investors see Morningstar as 17% undervalued.
Result: Fair Value of $236.67 (UNDERVALUED)
Still, the Morningstar narrative depends on AI tools like Lumonic 12.0 actually winning paying users and on insider sales not further eroding investor confidence.
Find out about the key risks to this Morningstar narrative.
Another View On Morningstar’s Valuation
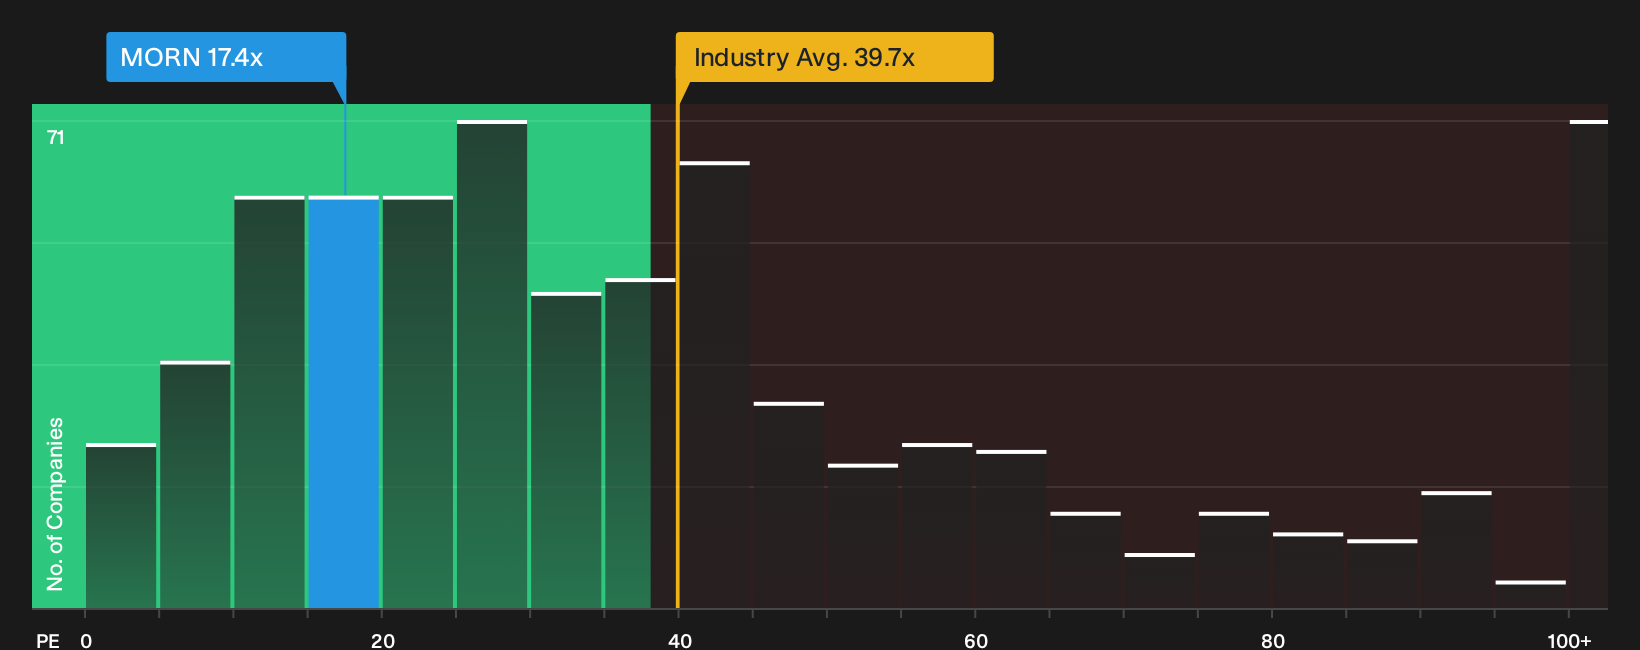
On simple P/E math, Morningstar looks mixed. The stock trades on 17.4x earnings, which is cheaper than the US Capital Markets group at 39.7x and below a 20x peer average, yet above a fair ratio of 13.2x that our model suggests the market could move toward over time. That gap points to some valuation risk if sentiment cools again.
To see how that compares with the wider market and how the current multiple stacks up against the fair ratio, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Morningstar’s valuation and narrative can feel messy, so move quickly from headline takes to your own verdict by weighing the 4 key rewards and 1 important warning sign.
Looking For More Morningstar-Like Investment Ideas?
Morningstar’s valuation can be one piece of your portfolio puzzle, but a broader watchlist of high conviction ideas often separates reactive traders from prepared investors.
- Target rock-solid financial footing by scanning our list of solid balance sheet and fundamentals (25 results), which highlights businesses with balance sheets designed to handle stress.
- Hunt for mispriced potential with the 19 high quality undiscovered gems, which spots strong fundamentals the wider market may not be focused on yet.
- Prioritise resilience by reviewing the 31 resilient stocks with low risk scores and build a watchlist that tilts toward steadier risk profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com