
Top 3 Australian Undervalued Stocks To Watch In October 2026
Oil prices sitting above US$100 per barrel keep pressure on inflation and interest rates, which can rattle many Australian shares. Cash rich businesses trading below their estimated worth can appear more resilient when money is expensive and growth stories are questioned. This article highlights three Australian stocks that screen as undervalued on future cash flows so you can see where value focused investors are starting their search.
The three examples below are only a sample, with the full screen surfacing 7 more Australian businesses with similarly compelling cash flow stories that are not covered here. To go straight to the source and identify your own highest conviction ideas, analyze the full Undervalued Stocks Based On Cash Flows Undervalued Stocks Based On Cash Flows screener.
Qualitas (ASX:QAL)
Overview: Qualitas is an Australian alternative real estate investment manager that focuses on private credit loans and related funds that generate recurring fee-based cash flows.
Operations: The business earns about A$15 million from funds management and direct lending activities, with revenue tied to Australian real estate markets totaling roughly A$131 million.
Market Cap: A$672 million
Qualitas matters for this cash-flow focused list because its real estate private credit engine turns secured property lending into recurring fee income that can be modeled with some confidence in discounted cash flow analysis.
"Banks have continued to move away from commercial property lending since 2009, and private credit’s share of Australian real estate debt has grown from 15% in 2019 to 26% today, with forecasts of 35% by 2030."
What happens to Qualitas’s valuation if one quiet pressure on that fee machine sharply changes how quickly new mandates and deployment arrive?
If that shift in mandates is what matters most for you, go straight to the full narrative for Qualitas for how Qualitas could respond if deployment suddenly accelerates or stalls.
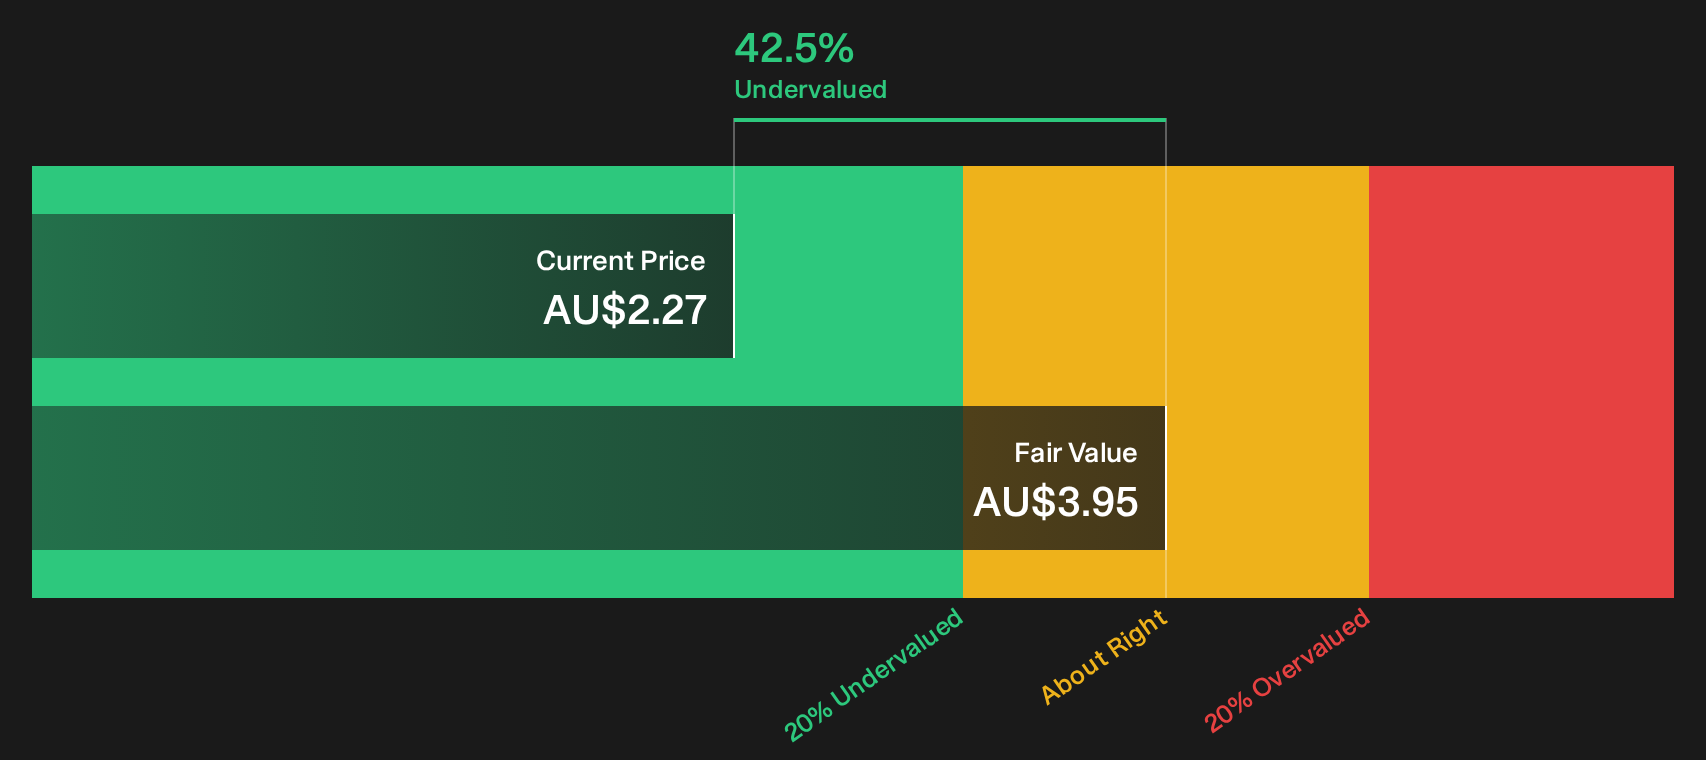
MotorCycle Holdings (ASX:MTO)
Overview: MotorCycle Holdings runs a broad network of dealerships and accessory outlets that sell and service motorcycles while generating recurring after-sales cash flows.
Operations: The group generates about A$560 million from Motorcycle Retailing and A$272 million from Motorcycle and Accessories Wholesaling, almost entirely in Australia.
Market Cap: A$188 million
MotorCycle Holdings matters here because its Motorcycle Retailing arm turns every bike sale into a long tail of servicing, parts and protection plan income that feeds the Undervalued Stocks Based On Cash Flows theme.
"E-commerce sales growth of 66% and a clear push toward an omnichannel model, with stronger digital engagement and data driven sales processes, give the company scope to grow higher margin online parts, accessories and finance attachment."
The real question is what happens to those margin ambitions if a single assumption about how riders spend on extras quietly shifts.
If you want to see how that spending thesis could accelerate or stall in practice, read the full narrative for MotorCycle Holdings for the trade offs the market may be missing.

Origin Energy (ASX:ORG)
Overview: Origin Energy is an integrated Australian utility that supplies electricity and gas. Its Integrated Gas arm produces LNG and domestic gas cash flows.
Operations: Origin Energy generates about A$15.3b from Energy Markets and A$307 million from Integrated Gas, with LNG and domestic gas underpinning theme-linked cash flows.
Market Cap: A$18.9b
Origin Energy matters for this cash flow list because its Integrated Gas segment turns long term LNG and domestic gas contracts into recurring cash that feeds the DCF valuation story, even as retail electricity and other services dominate the headline revenue mix.
"The company's capital-intensive investments in renewables, storage, and international software platforms (Kraken/Octopus) are being valued as sources of near-term EBITDA growth. However, these ventures may face execution risks and cost overruns, which could compress return on capital and drag on future earnings."
The real test is what happens to that cash flow backed valuation if one assumption about future LNG cash generation quietly shifts.
When that LNG assumption starts to shift, the full narrative for Origin Energy outlines how Origin Energy’s cash flows could decouple from headline earnings and reset sentiment.
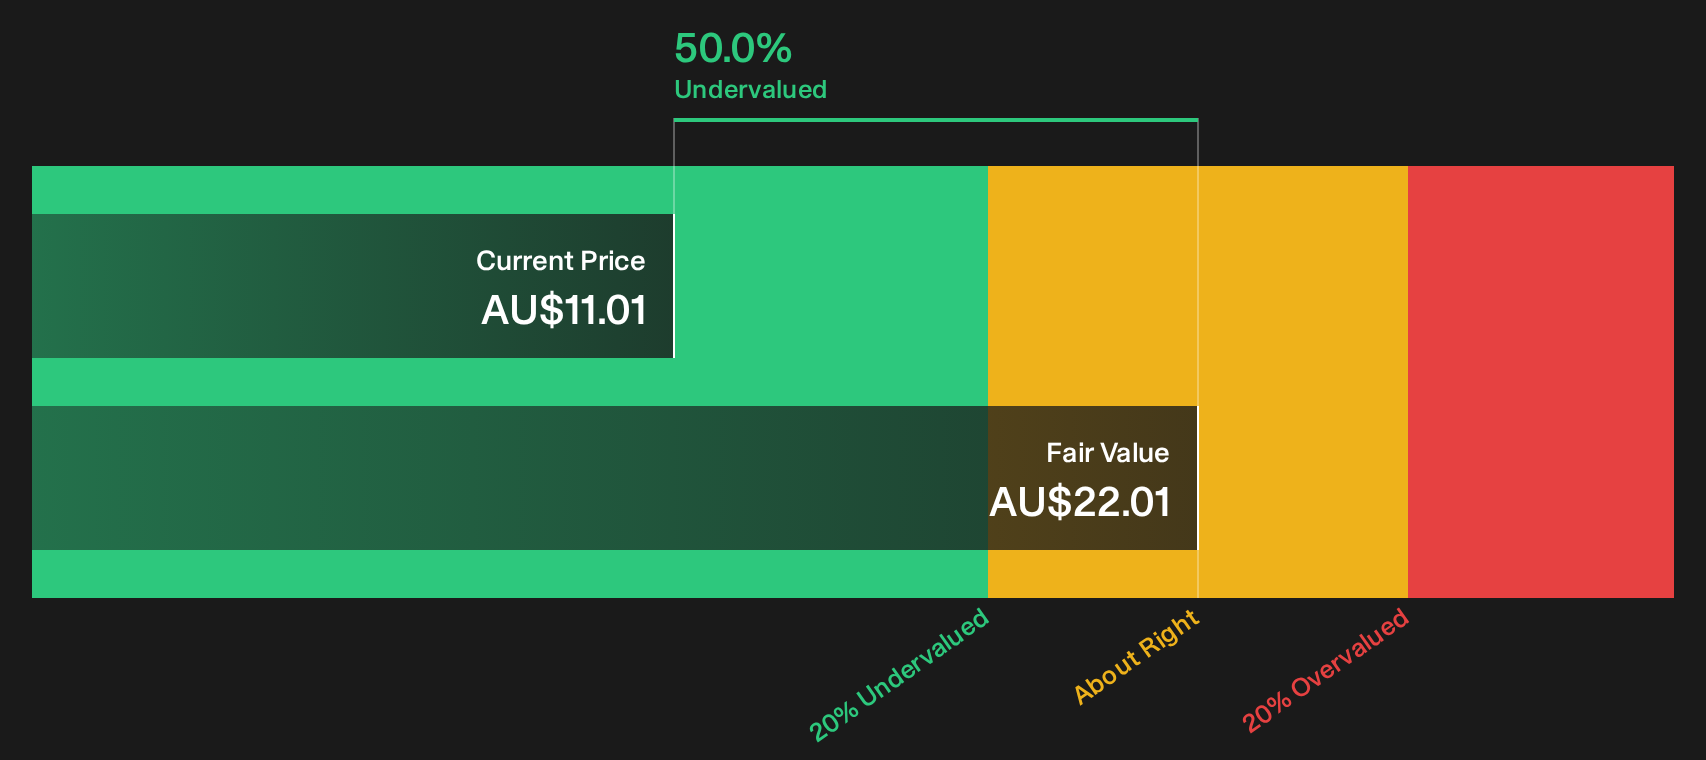
Seeking Alternatives Before The Crowd?
Fresh ideas move first. Breakout stories gain momentum while they are still under the radar. Do not get caught watching prices dropping. Consider taking action based on your own research and circumstances.
- Spot cash rich businesses with falling risk scores by scanning the curated 7 resilient stocks with low risk scores before momentum traders start chasing them.
- Track early infrastructure companies related to AI demand as data center and chip spending continues to flow into the 91 AI infrastructure stocks while it is still timely.
- Pinpoint power grid upgrades connected to electrification and AI loads through the hand picked 44 power grid technology and infrastructure stocks before the broader market recognizes the story.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com