
Is Gerberlyte Launch Altering The Investment Case For Nestlé (SWX:NESN)?
- Nestlé, through its Gerber brand, has introduced Gerberlyte, a child-focused rehydration drink made with organic coconut water and no artificial dyes or sweeteners, reflecting recent portfolio changes already in market.
- The Gerberlyte launch highlights Nestlé’s push to reposition legacy baby food assets toward health driven hydration and nutrition, answering parents’ demand for cleaner ingredient lists while facing direct competition from Capri Sun and Kool-Aid electrolyte drinks.
- We will now look at how Nestlé’s health focused Gerberlyte launch interacts with the existing investment narrative around premium nutrition.
Scan health focused consumer staples beyond Nestlé by reviewing the curated list of solid balance sheet and fundamentals (206 results), which may have room to benefit if cleaner-label hydration and nutrition trends keep building momentum.
Nestlé Investment Narrative Recap
To own Nestlé, you need to believe the group can keep shifting its huge food portfolio toward health focused, premium and science led categories while keeping margins intact despite commodity, FX and tariff pressure. The Gerberlyte launch fits that story, but on its own does not change the near term earnings trajectory or cash generation picture.
The key near term swing factor still sits in execution on pricing, cost savings and demand recovery in weaker regions like Greater China. The biggest risk remains that slower category growth and brand relevance problems in areas such as legacy nutrition offset progress in PetCare, coffee and premium nutrition, leaving profitability and free cash flow under strain.
The board’s appointment of Manuela Bernasconi as Group General Counsel from January 2027 is the most relevant development around this Gerberlyte news. Nestlé is pushing harder into health, wellness and child nutrition, and that brings tighter regulatory scrutiny, more complex labelling standards and a heavier compliance load across multiple regions.
A seasoned internal lawyer stepping into the top legal role can matter for how cleanly Nestlé executes portfolio reshaping, disposals of lower growth brands and faster product rollouts such as Gerberlyte. For you as an investor, the link is indirect but real. Smoother legal and governance execution can support margin work, protect cash flows and reduce the risk that regulatory setbacks interrupt the premium nutrition catalyst.
Nestlé Forecasts Investors Are Watching
Nestlé's narrative projects CHF 94.7b revenue and CHF 12.0b earnings by 2029, based on analyst estimates. This implies 1.7% yearly revenue growth and an earnings increase of CHF 3.0b from CHF 9.0b today.
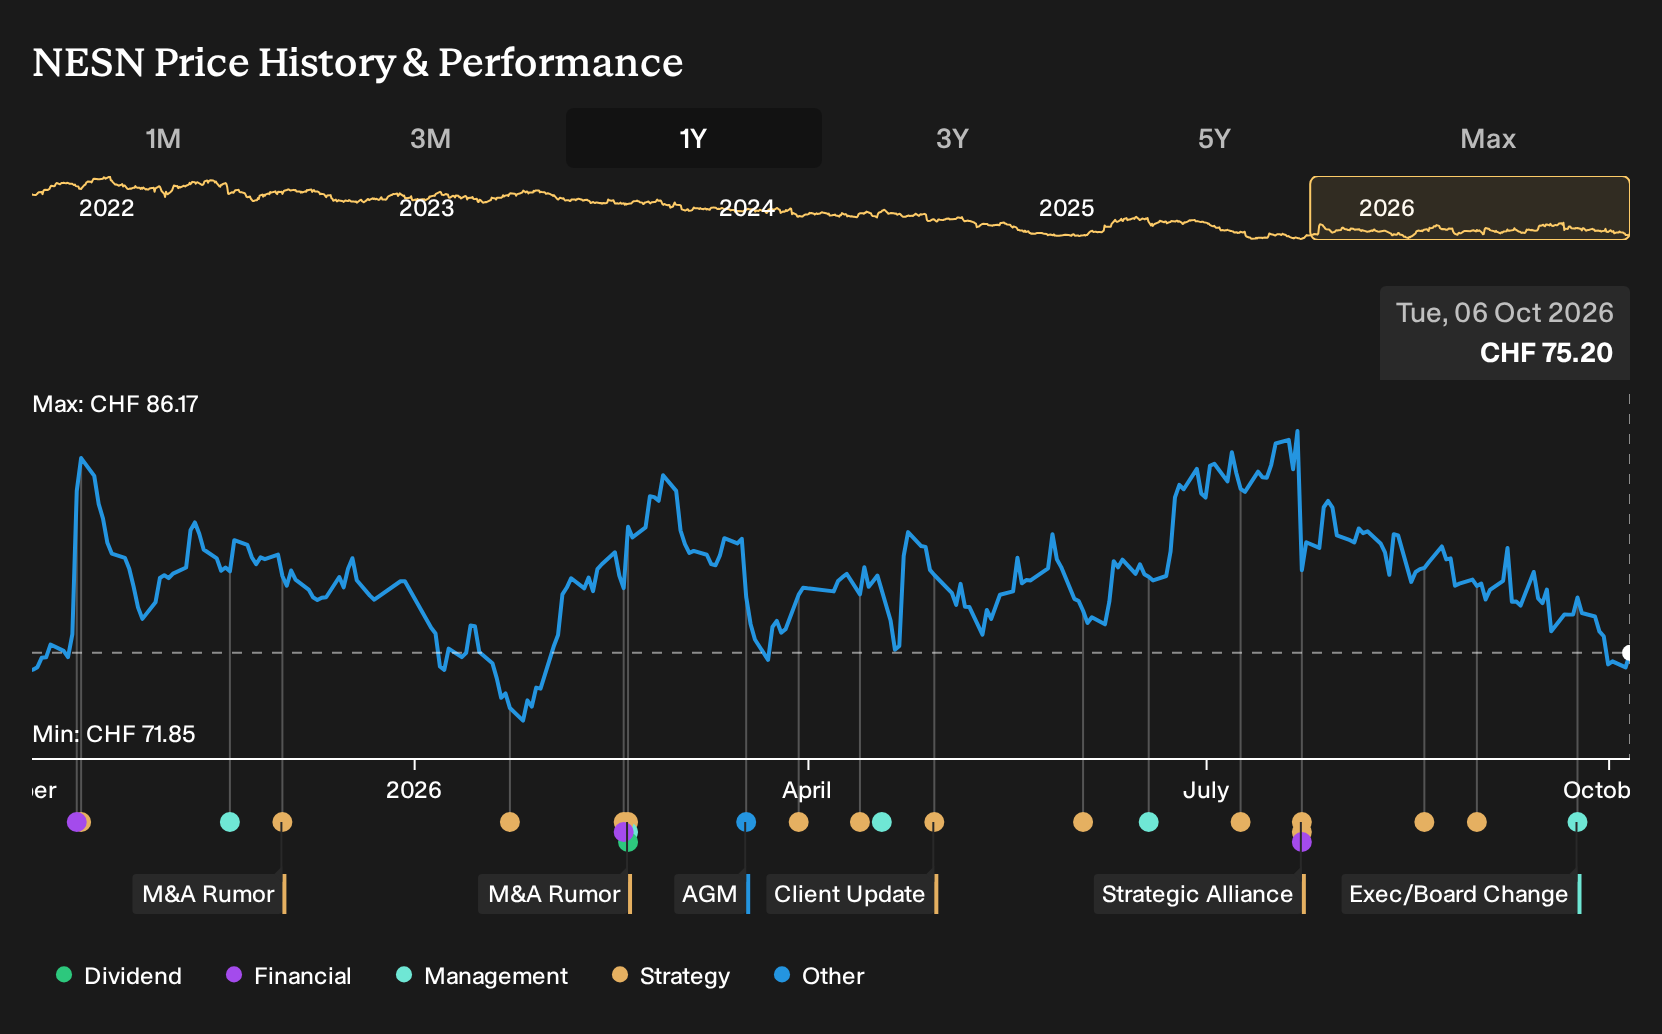
Uncover why Nestlé's fair value indicates a 17% potential upside to its current price before other investors fully price in that gap.
Exploring Other Perspectives
Four fair value views from the Simply Wall St Community spread from about CHF 87.9 to CHF 138.6 per Nestlé share, which shows how sharply retail opinions can diverge. Set that against risks around margin pressure, weak demand in Greater China and execution on health focused brands, then explore these alternative perspectives before deciding how Nestlé fits your portfolio.
Explore 3 other Nestlé fair value estimates, including one that suggests as much as 84% upside from the current price!
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Nestlé research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Nestlé. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Nestlé's overall financial health at a glance.
Looking For More Ideas Beyond Nestlé?
Once you have formed a view on Nestlé, it can help to compare that thesis with other businesses that share similar quality traits or income characteristics. The Simply Wall St Screener lets you quickly filter the market so you can line up potential alternatives side by side and pressure test where Nestlé really earns a place in your portfolio.
- If you care most about resilient balance sheets and steady fundamentals, start with this curated list of solid balance sheet and fundamentals (206 results) that focuses on financially robust companies.
- For investors who want income today as well as potential stability, scan through 164 dividend fortresses and see which high-yield payers might deserve a closer look next.
- When the priority is limiting downside risk, use 227 resilient stocks with low risk scores to zero in on businesses that score well on resilience and volatility measures.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com