
Yuexiu Property (SEHK:123) Secures HK$2.4b As Liquidity Relief Puts Value Back In Focus
Yuexiu Property (SEHK:123) has lined up fresh funding. The developer recently secured several bank facilities totaling up to HK$2.4b to support Hong Kong and Mainland projects, tied to specific controlling shareholder covenants.
For investors watching the tape, Yuexiu Property’s 1-day share price return of 0.61% sits against a year-to-date share price decline of 17.66% and a 1-year total shareholder return that has fallen 31.99%. The fresh HK$2.4b in funding arrives while longer term momentum has been weak and sentiment around risk and liquidity is still resetting.
Compare Yuexiu Property’s funding story with other real estate developers by scanning our hand picked list of solid balance sheet and fundamentals (206 results) that are handling leverage and liquidity in very different ways.
Yuexiu Property now has fresh liquidity available, while the share price has retreated over the past year. The key tension is simple: does that combination create a fundamentally strong business that still represents only a relatively average opportunity at today’s valuation?
Preferred Price-to-Sales of 0.2x: Is it justified?
Yuexiu Property trades on a P/S ratio of 0.2x, which screens as inexpensive when lined up against both peers and the broader Hong Kong real estate sector.
The P/S ratio compares the company’s share price to its revenue per share, so it effectively shows how much investors are paying for each dollar of sales. For a business like Yuexiu Property that is currently loss making, this measure often gets more attention than P/E because earnings do not yet provide a clean anchor.
Analysts assessing the stock describe it as good value at 0.2x P/S compared to the peer average of 0.2x and the Hong Kong real estate industry average of 0.7x. The same metric is also below an estimated fair P/S ratio of 0.4x, which is presented as a level that the market could potentially move toward if sentiment around earnings and balance sheet risk improves.
Explore the SWS fair ratio for Yuexiu Property.
Result: Price-to-sales of 0.2x (UNDERVALUED)
Still, Yuexiu Property carries clear risks, including a recent net loss and share returns that have fallen sharply over 1, 3 and 5 years.
Find out about the key risks to this Yuexiu Property narrative.
Another View on Yuexiu Property’s Value
The SWS DCF model paints a very different picture for Yuexiu Property. At HK$3.31, the stock is described as trading well below an estimated future cash flow value of HK$94.61, which implies a very large potential gap between price and modelled worth. That kind of spread can point to opportunity, but it can also flag serious uncertainty around the inputs investors are relying on. Which side of that trade do you think the market is pricing in?
Look into how the SWS DCF model arrives at its fair value.
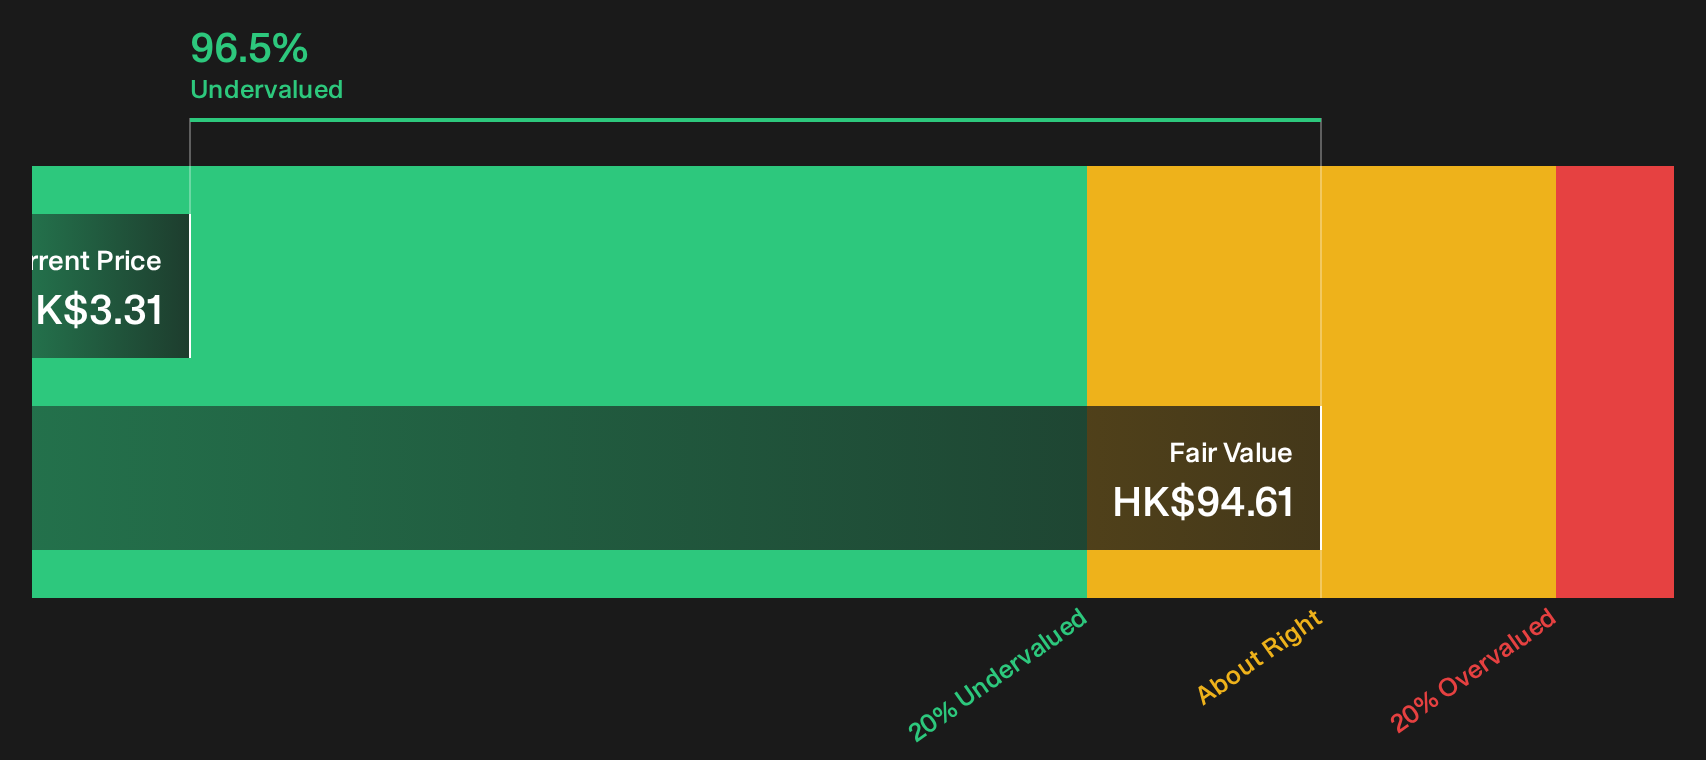
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Yuexiu Property for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 185 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment around Yuexiu Property is clearly mixed, with both risks and potential rewards on the table. Move quickly, look through the numbers yourself and decide where you stand in light of the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Yuexiu Property?
If Yuexiu Property has sharpened your focus on value and risk, do not stop here. Broaden your watchlist now and give yourself more options.
- Target potential mispricing by scanning our 185 high quality undervalued stocks and see which opportunities currently trade at compressed valuations with solid underlying fundamentals.
- Strengthen your income stream by reviewing companies in the 164 dividend fortresses that offer higher yields and consistent payout histories.
- Reduce portfolio stress by focusing on financially robust businesses through the 227 resilient stocks with low risk scores that combine resilience with measured risk profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com