
What C3.ai (AI)'s Billings Decline Means For Shareholders
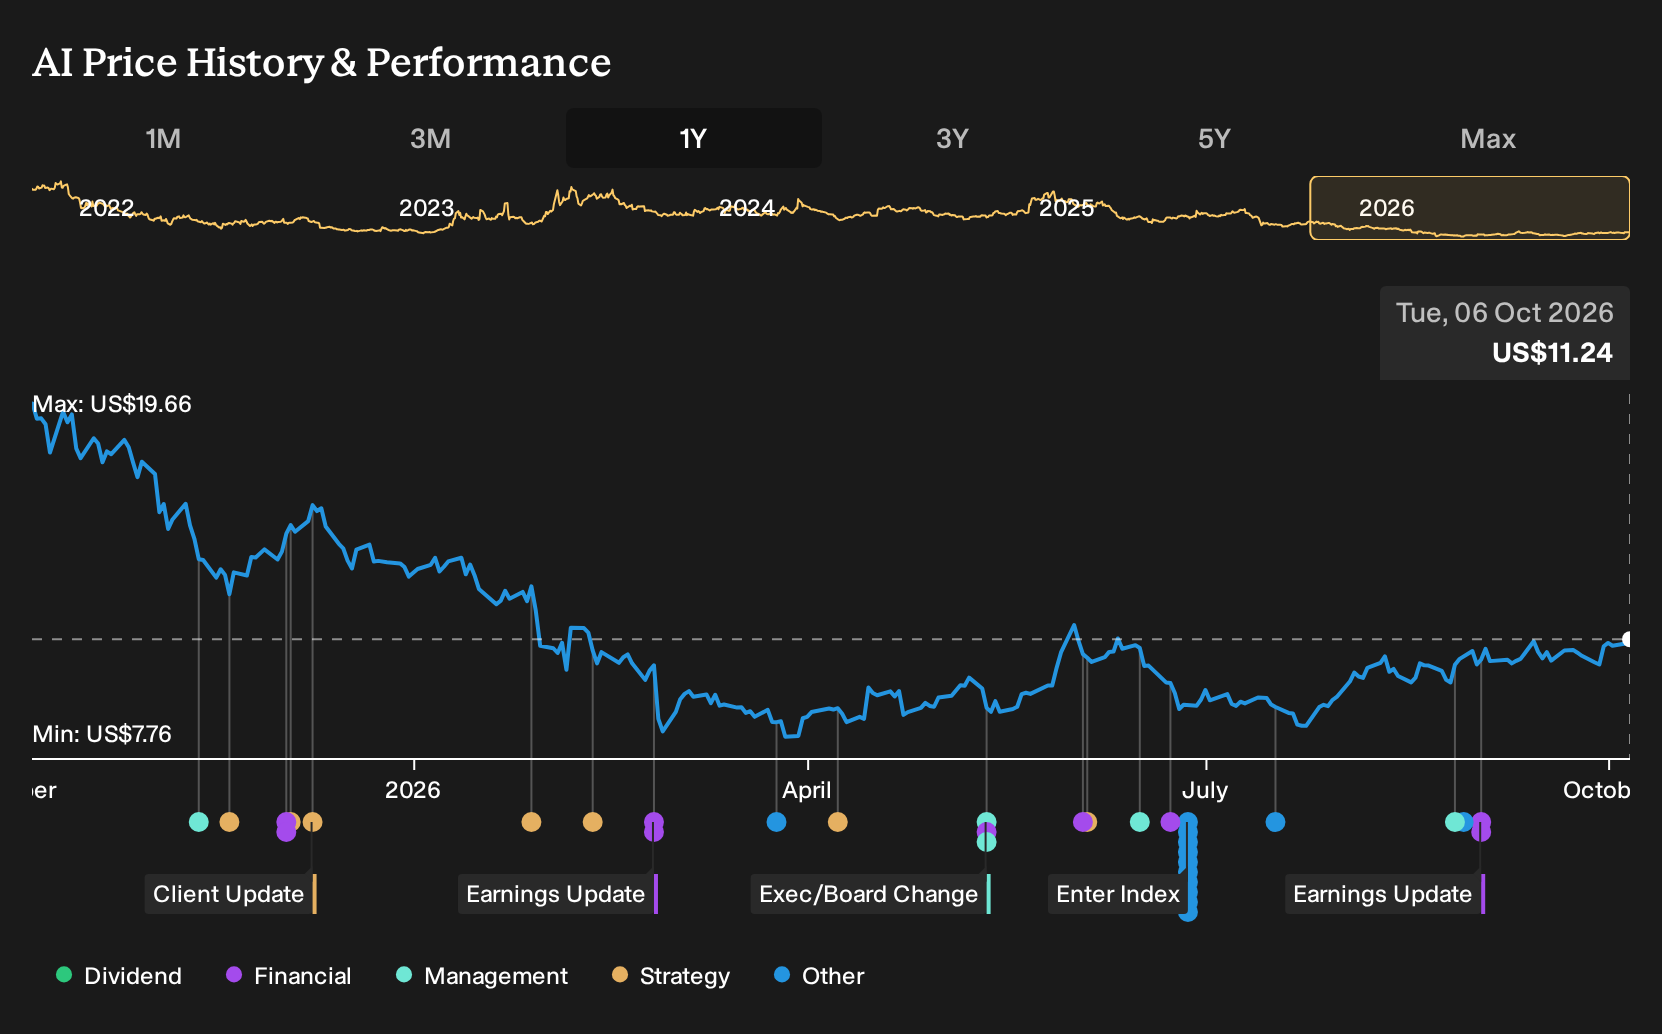
- C3.ai recently reported year over year declines in billings, along with gross margins that sit well below many software peers. This highlights pressure from higher infrastructure costs and weaker structural profitability.
- The business has reported a single quarter of positive free cash flow. However, its overall free cash flow margin remains negative, which points to ongoing cash burn risk despite heavy reinvestment in growth.
- We will examine how C3.ai's investment narrative is shaped by these weaker billings trends and discuss what that may mean for investors.
Balance C3.ai’s billings pressure with other options by scanning a curated set of resilient companies in our 31 resilient stocks with low risk scores, which prioritises stronger financial footing and lower risk profiles.
C3.ai Investment Narrative Recap
To own C3.ai, you need to believe that enterprise demand for AI platforms can offset weak billings, softer gross margins and ongoing losses. In the short term, the key swing factor is whether customer pilots convert into broader deployments that stabilise billings. Recent declines in billings and modest gross margins keep that outcome uncertain for now.
The largest near term risk is continued cash burn on a business that still reports a loss of US$446.4 million and negative free cash flow margins. One positive free cash flow quarter helps sentiment but does not change the core risk if billings softness persists and infrastructure costs remain elevated.
With no fresh announcements tied directly to this billings update, the earlier decision to withdraw financial guidance remains one of the more important reference points. That move highlighted management’s limited visibility on revenue, which aligns with the current pressure on billings and underscores how bumpy near term execution can be.
For you as an investor, this lack of guidance keeps the focus on operational proof points such as consistent billings, gross margin stability around 52% and progress toward lower operating losses. Until those data points become clearer, the C3.ai story rests heavily on patience with execution risk and on your comfort with ongoing cash burn.
C3.ai Analyst Scenario At A Glance
C3.ai's current analyst blueprint is built around slow top line progress and a sharp swing in profitability over several years. Consensus assumptions point to revenue growth of 2.5% a year, earnings today of a US$470.4 million loss and forecast earnings of US$32.7 million by 2029. That implies an earnings improvement of about US$503 million by the 2029 estimate year.
C3.ai's narrative projects US$269.8 million revenue and US$32.7 million earnings by 2029. This rests on 2.5% yearly revenue growth and an earnings improvement of about US$503 million from a current loss of US$470.4 million.
Uncover why C3.ai's fair value indicates a 22% potential downside to its current price, which leaves little room for error.
Exploring Other Perspectives
You now see how sharply opinions on C3.ai can diverge. The most bearish analysts worry that open source AI and in house builds could leave revenue almost flat, with only about US$252.6 million sales and US$30.6 million earnings by 2029. Those views pre date this billings setback, so forecasts and narratives may shift.
Explore 4 other C3.ai fair value estimates, including one that suggests as much as 47% downside from the current price.
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your C3.ai research is our analysis highlighting 2 important warning signs that could impact your investment decision.
- See our latest analysis for C3.ai. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate C3.ai's overall financial health at a glance.
Looking For More Investment Ideas Beyond C3.ai?
If the C3.ai story leaves you wanting a broader watchlist, the Simply Wall St Screener can help you line up alternatives that better match your risk tolerance and income goals.
- If capital protection matters most to you, start with a shortlist of companies that have historically carried sturdier finances by reviewing our list of solid balance sheet and fundamentals (25 results).
- For investors who want a margin of safety on price, scan a focused collection of potential value opportunities using the 27 high quality undervalued stocks.
- If income is your priority, build a watchlist of potential cash generators by checking out the 8 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com