
3 British Undervalued Stocks For October 2026
With U.S. Treasury yields at a 24 year high, global money is being pulled toward safer bonds and away from riskier assets. That makes it harder for many UK shares to command rich price tags, even when their underlying cash engines look solid. For patient investors, that gap between cash flow potential and current pricing can be attractive. This article highlights three UK stocks that currently appear underpriced based on analyst projections of their future cash flows.
These three ideas are only a small sample, and the full screen has surfaced 24 more businesses with similarly interesting cash flow stories that are not covered below. If you want to identify and analyze the highest conviction cash flow opportunities right now, go straight to the Undervalued Stocks Based On Cash Flows screener
Distribution Finance Capital Holdings (AIM:DFCH)
Overview: Distribution Finance Capital Holdings is a specialist UK lender providing working capital and inventory finance to manufacturers, distributors and dealers.
Operations: The group generates £60 million of revenue from commercial financial services in the United Kingdom, centred on working capital and receivables lending.
Market Cap: £122 million
Distribution Finance Capital Holdings fits this cash flow screen because its working capital and receivables lending produce the loan repayments that underpin discounted cash flow valuation, while current pricing implies that engine is not fully reflected in the share price.
"The expansion from pure inventory finance into asset finance and structured finance gives Distribution Finance Capital Holdings more ways to serve the same manufacturers and dealers. This can support higher loan volumes and fee income over time, benefiting revenue and earnings."
What ultimately happens to margins and cash generation depends on how one less visible pressure on its funding costs plays out.
If that funding squeeze is what you care about most, read the full narrative for Distribution Finance Capital Holdings to see whether rising costs are masking a much stronger cash engine.
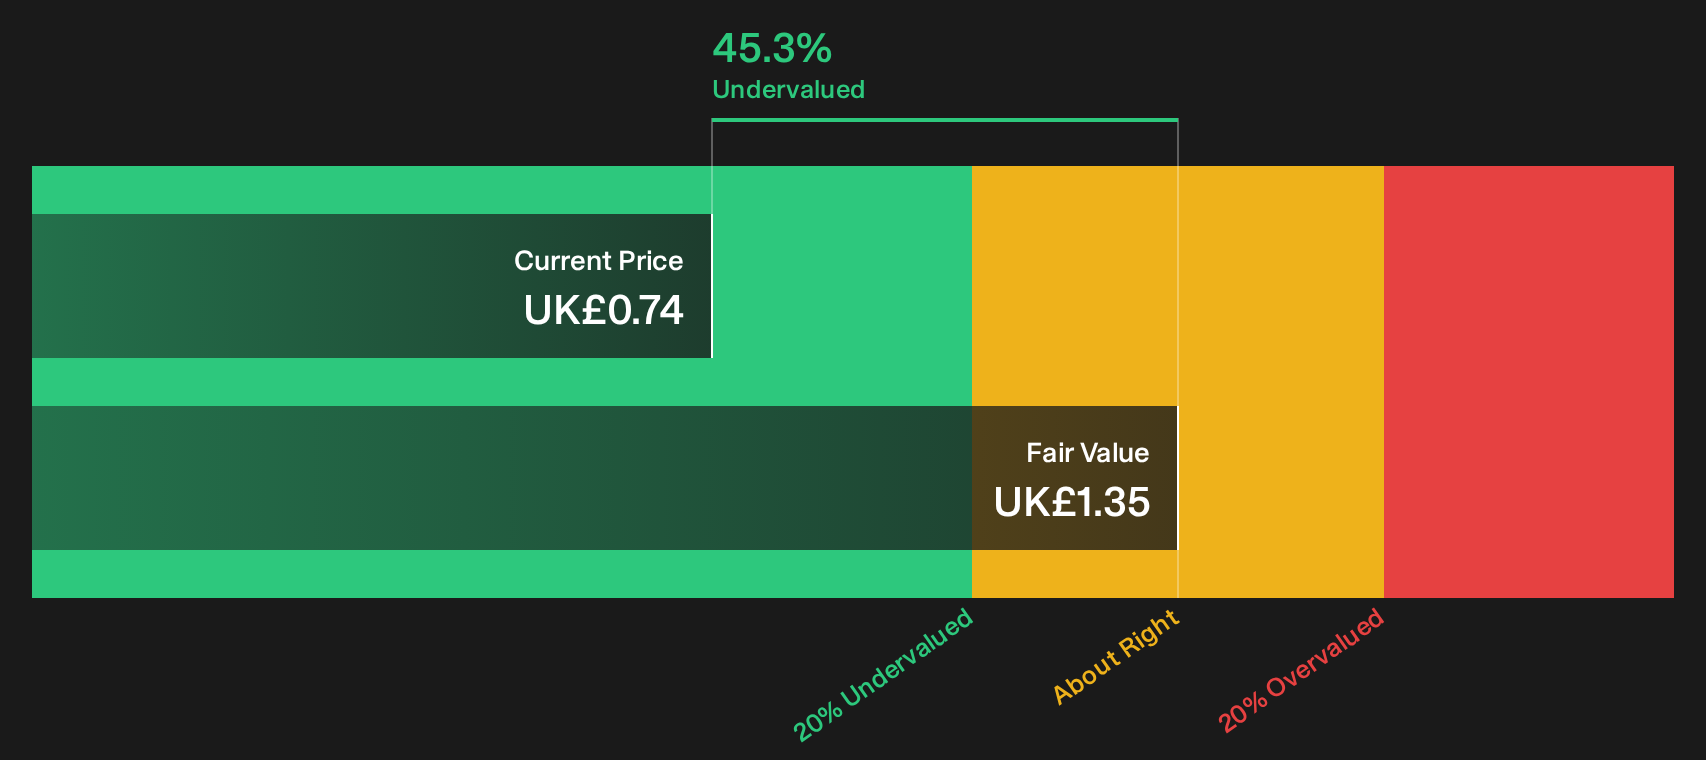
Smiths News (LSE:SNWS)
Overview: Smiths News runs UK focused newspaper and magazine distribution, final mile delivery and related logistics services that generate recurring cash flows.
Operations: Smiths News generates £1.0b of sales from its Smiths News including DMD distribution business, almost entirely in the United Kingdom.
Market Cap: £179 million
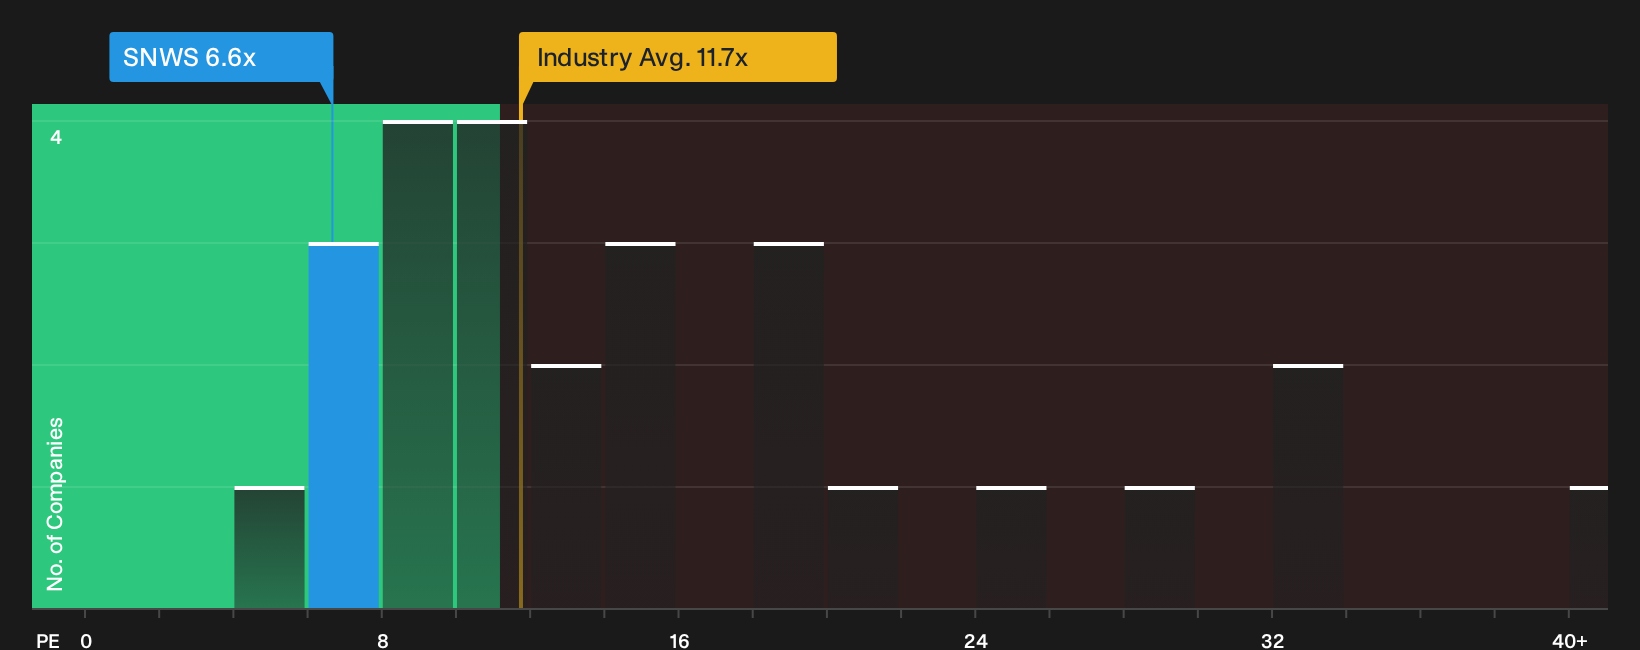
Smiths News connects cleanly to the undervalued cash flow theme because its UK newspaper and magazine logistics network generates recurring distribution fees that support a discounted cash flow valuation. The shares trade on a P/E of 6.6x versus far higher peer and industry averages, leaving investors to judge how those long term delivery contracts ultimately interact with its thin margins.
Those thin margins and low P/E invite a closer look at whether the cash story is decoupling from the share price. Check the analysis report for Smiths News for how the numbers stack up.
Gamma Communications (LSE:GAMA)
Overview: Gamma Communications provides cloud-based voice, video and contact-center services that give organisations subscription-style communications and software tools.
Operations: Gamma Communications generates most of its £659 million business revenue from Enterprise and Germany SME segments, supported by wider European operations.
Market Cap: £973 million
Gamma Communications matters for this cash flow screen because its cloud telephony and contact-center subscriptions convert recurring customer usage into predictable cash earnings.
"The adoption of cloud-based communications in large European markets, especially Germany, which has significantly lower cloud penetration (<20%) than the UK, is a key factor as German SMEs and enterprises migrate from legacy PBX to cloud platforms."
What happens to those cash flows if one key assumption about how quickly larger customers shift their communications budgets quietly changes?
If that shift in budgets is what you are weighing, read the full narrative for Gamma Communications to see whether accelerating cloud adoption could be masking even stronger cash potential.

Seeking Alternatives Before The Crowd
Fresh ideas move first. While others react to yesterday’s headlines, you can look for the next breakout, monitor early momentum and avoid dropping laggards while it matters by getting in early.
- Look for under the radar growth stories by scanning a curated pool of 4 high quality undiscovered gems before they attract wider investor attention.
- Explore potential income opportunities from companies with established payouts using a focused shortlist of 1 dividend fortresses before yields change in response to new money.
- Monitor the next tech infrastructure developments by tracking hand picked 91 AI infrastructure stocks while they are still building momentum under the radar.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com