
What Comes Next For Monte Dei Paschi After A 75% Gain
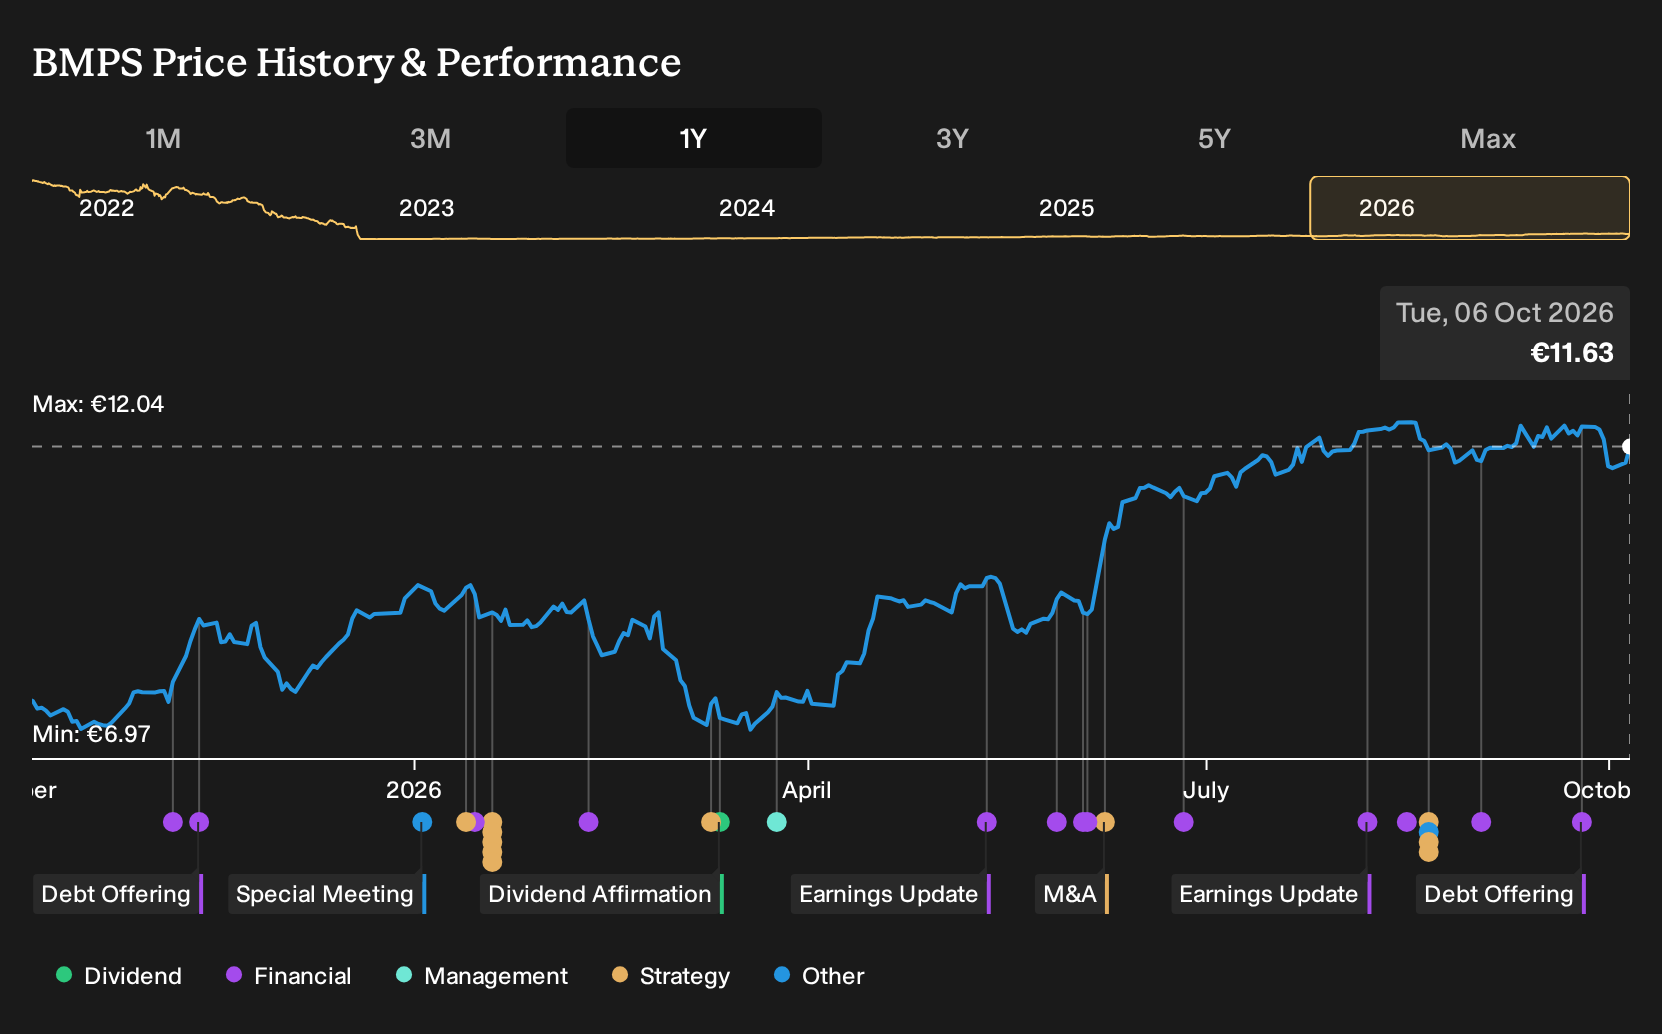
If you only read the 2025 research on shrinking margins, aging demographics, and fintech pressure, Banca Monte dei Paschi di Siena looked like a high risk way to play Italian banking consolidation. Holding Banca Monte dei Paschi di Siena over the past year would have returned 75.1%, including dividends. If you had bought on 6 October 2025 with those warnings in mind, what should this outcome say about how investors weighed those risks and the later takeover battle headlines?
Banca Monte dei Paschi di Siena has already moved. See which of 185 high quality undervalued stocks still trade below our estimates.
The Argument You Would Have Been Weighing On Banca Monte dei Paschi di Siena
The shares cost €7.44 at the start of the period. Anyone looking at Banca Monte dei Paschi di Siena then had to choose between two very different stories. Both rested on detailed assumptions about margins, capital, and the impact of a potential Mediobanca tie up.
On the bullish side, the optimistic Narrative pointed to a Fair Value of €9.28, the price implied if its scenario played out. This was based on 15.1% revenue growth assumptions, strong 35.6% profit margins, and heavy reliance on merger synergies to offset shrinking net interest margins.
The bearish view anchored on a Fair Value of €6.35, again a value implied by its own forecast path. It focused on aging demographics, fintech rivalry, and higher credit risk from accelerated mortgage and retail lending potentially dragging margins and earnings lower over time.
What The Facts Did To The Monte dei Paschi Argument
The unsolicited €30.6b bid from Intesa Sanpaolo for Banca Monte dei Paschi di Siena, later lifted to €35b, supported the optimistic case that consolidation value and merger synergies mattered. The Banco BPM withdrawal and the board’s view that Intesa’s initial premium sat below peers, together with Italy’s plan to cut its stake, gave investors mixed signals. Overall, the period cut both ways.
The key lesson is simple. When a thesis leans on takeovers or mergers, track actual bid premia, required ownership thresholds, and any competing offers rather than assuming consolidation value will appear on the terms that early forecasts imagined.
What Banca Monte dei Paschi di Siena’s Price Already Bakes In
Today Banca Monte dei Paschi di Siena trades at €11.63, after a 75.1% gain over the past year. The selected Narrative’s Fair Value sits below that level because it sees the current valuation as already baking in ambitious benefits from the bank’s expansion and planned integrations.
This view hinges on Banca Monte dei Paschi di Siena turning a larger, more complex group into durable fee and commission income. Anyone buying now is effectively assuming that integration costs and capital demands do not derail that shift, which is exactly where the selected Narrative sees the main execution risk.
"Although Banca Monte dei Paschi di Siena presents the Mediobanca, Banco BPM and Banca Generali combinations as a way to build a broad, fee oriented platform, the enlarged group would be exposed to higher execution and integration risk across multiple retail, corporate, investment banking and wealth businesses at once, which could keep operating costs structurally elevated and cap improvements in the cost/income ratio and net margins."
One Narrative has put a figure on that disagreement. → See the Narrative with its lower Fair Value, assumptions and all
Where Monte dei Paschi Points Next
Banca Monte dei Paschi di Siena shows how much effort banks pour into fees and digital reach. Your watchlist does not have to stop there.
Large global lenders are also investing in mobile tools, AI support and faster transaction rails. They want customers to stay, click and borrow without friction.
One of them is focusing on real time cross border payments and credit lines for fast growing tech platforms.
The same push that makes Banca Monte dei Paschi di Siena emphasize fee income also encourages this other bank to deepen trading desks and advisory work.
If that shift toward data heavy, fee rich services keeps broadening, this quieter giant could offer an interesting second angle on the same pressures and possibilities.
That argument has a Narrative and a number behind it. → See the company one Narrative values 26% above its price
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com