
Missed Out On Argan's Run? Here Is What Holders Saw
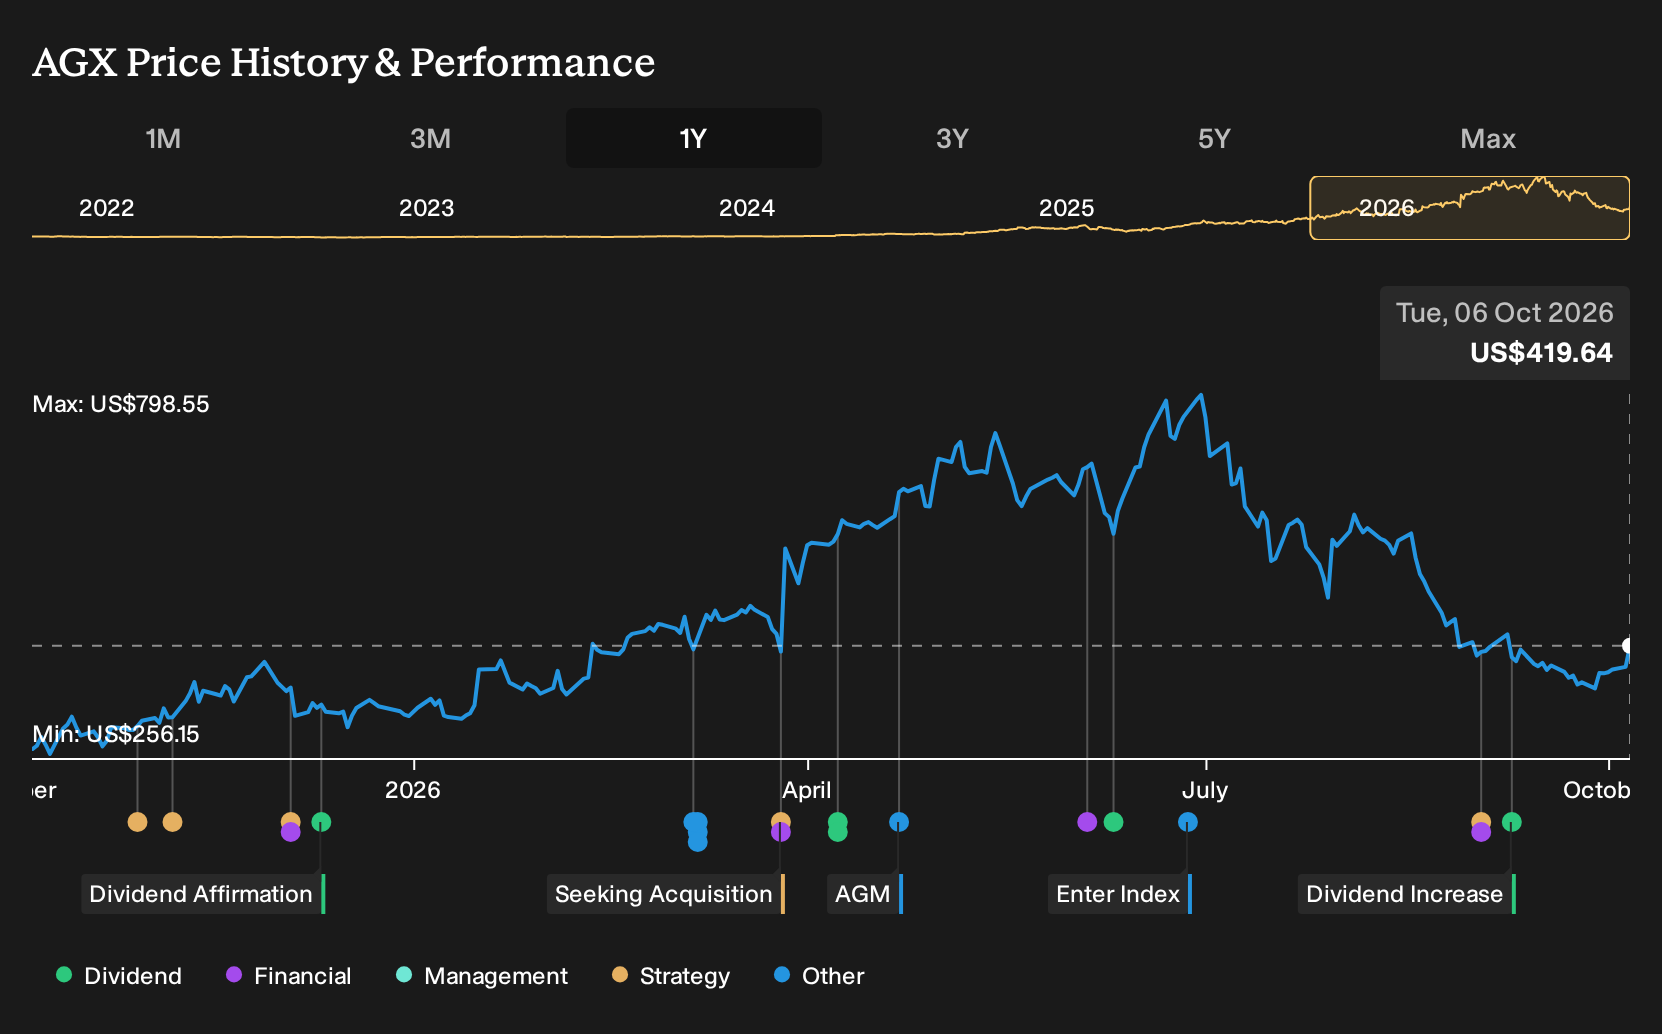
If one contract captured Argan’s recent story, it was the wave of new gas and renewable projects tied to AI data centers that helped push the reported backlog to about US$2.9b in the latest fiscal year. Investors who held Argan over the past year are up 57.0%, including dividends. If you were deciding back on 6 October 2025, what beliefs about those future projects would have been necessary to justify buying in?
Argan is not the only name tied to this theme. Zero in on 40 power grid technology and infrastructure stocks and compare how each one is priced.
The Two Stories Argan Investors Were Weighing
The shares cost US$264 at the start, so anyone buying Argan had to decide which future they trusted more.
In the bullish script, the stock looked underpriced against a Fair Value of US$285, a rough estimate of what the assumptions implied it might be worth. That view leaned on revenue growth of 13.3% a year and profit margins at 10.8% over a 10 year stretch.
The cautious angle pointed to a Fair Value of US$230, framed as a lower implied worth if things went less smoothly. That outlook still used 18.1% annual revenue growth, but with margins drifting to 9.4% and risk that a gas heavy backlog might age badly.
What The Argan Evidence Actually Tested
The clearest test for Argan was the record US$2.9b backlog tied to AI, electrification projects and the completion of Trumbull Energy Center. This supported the bullish demand and execution story. Set against that, Q2 2027 results showed revenue and net income above Q2 2026 while net margin slipped from 14.8% to 13.9%. Overall, the evidence cut both ways.
The key lesson is simple. When a thesis leans on multi-year project pipelines, track backlog size, mix by end market and the direction of reported margins each period to see whether the quality of that work is improving or fading.
What Argan’s Price Now Asks You To Believe
Argan trades at US$420 today after a 57.0% gain over the past year. The selected Narrative’s Fair Value sits below the current price, framed around limits on crew capacity and what that might mean for how much AI power work can realistically be taken on.
The Narrative asks you to judge whether today’s valuation still works if Argan’s ability to staff projects and win fresh awards proves tighter than hoped. A buyer now would need confidence that execution quality holds even if more EPC competitors chase the same grid and gas jobs.
"Several bearish analysts point to a ceiling on available crews at Argan. This factor is viewed as a structural cap on how much work the company can realistically take on without adding meaningful new capacity."
That disagreement has a full argument behind it. → Uncover the lower Fair Value this Narrative argues for
Argan And The Power Behind It
Argan highlights the construction side of AI hungry power projects. You can also look at the hardware that keeps those electrons moving.
Data centers and grids both lean on reliable generation and heavy-duty electrical gear. One industrial player focuses on gas turbines plus the transformers and switchgear that route power.
Its installed turbines keep customers coming back for servicing, maintenance and software upgrades. That repeat work can matter as much as selling new equipment.
As AI facilities and electrified demand keep stressing old grids, that service heavy role could evolve again. The question is how much value the market already assigns to that shift.
It is written up in full, assumptions and all. → Explore the Narrative that puts this company 23% above its price
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com