
Does Fintech Network Expansion Change The Bull Case For Jack Henry Stock (JKHY)?
- Hyland previously announced it joined the Jack Henry Fintech Integration Network, gaining access to Jack Henry resources to support its OnBase integrations with SilverLake and Symitar Episys for secure, workflow oriented use of core banking data.
- The arrangement keeps OnBase as a central content hub instead of another document silo, which can reduce operational friction for Jack Henry clients that rely on existing core applications.
- We will now look at how Jack Henry's integration focused work with Hyland could influence the broader investment narrative around the business.
Look beyond Jack Henry & Associates to identify other fintech infrastructure plays gaining traction through bank integrations with a curated list of 91 AI infrastructure stocks.
Jack Henry & Associates Investment Narrative Recap
To own Jack Henry & Associates, you need to be comfortable with a slow but steady fintech infrastructure story that leans on sticky bank and credit union relationships, high recurring revenue and disciplined cost control. The Hyland news fits that theme. It reinforces Jack Henry as a connectivity layer rather than a closed core, which supports the existing cloud and modernization push.
The most immediate operational catalyst still sits in how effectively Jack Henry converts hosted and public cloud interest into larger contract wins and ongoing software usage. The main near term risk remains pressure on margins if cost inflation or weaker deconversion related revenue persists. This Hyland integration work looks incremental, not a needle moving shift.
The Hyland joining of the Fintech Integration Network matters most where it intersects with the Jack Henry platform rollout. That public cloud native stack already runs around 30 integrated core modules for roughly 100 institutions serving about 16 million digital users, which creates a clear need for clean, governed content and workflow access across partners.
By tightening integrations with OnBase through SilverLake, Symitar and Jack Henry's service layers, the business can make those modernization projects easier for banks to adopt without ripping out familiar systems. That supports the existing catalysts around hosted adoption, higher value bundled wins and AI enabled workflows, while still leaving the long term client consolidation risk firmly in place.
Jack Henry & Associates' current analyst narrative points to revenues of US$3.1b and earnings of US$610.5m by 2029, based on an assumed 6.6% yearly revenue growth rate and an earnings increase of about US$107.7m from the US$502.8m reported today.
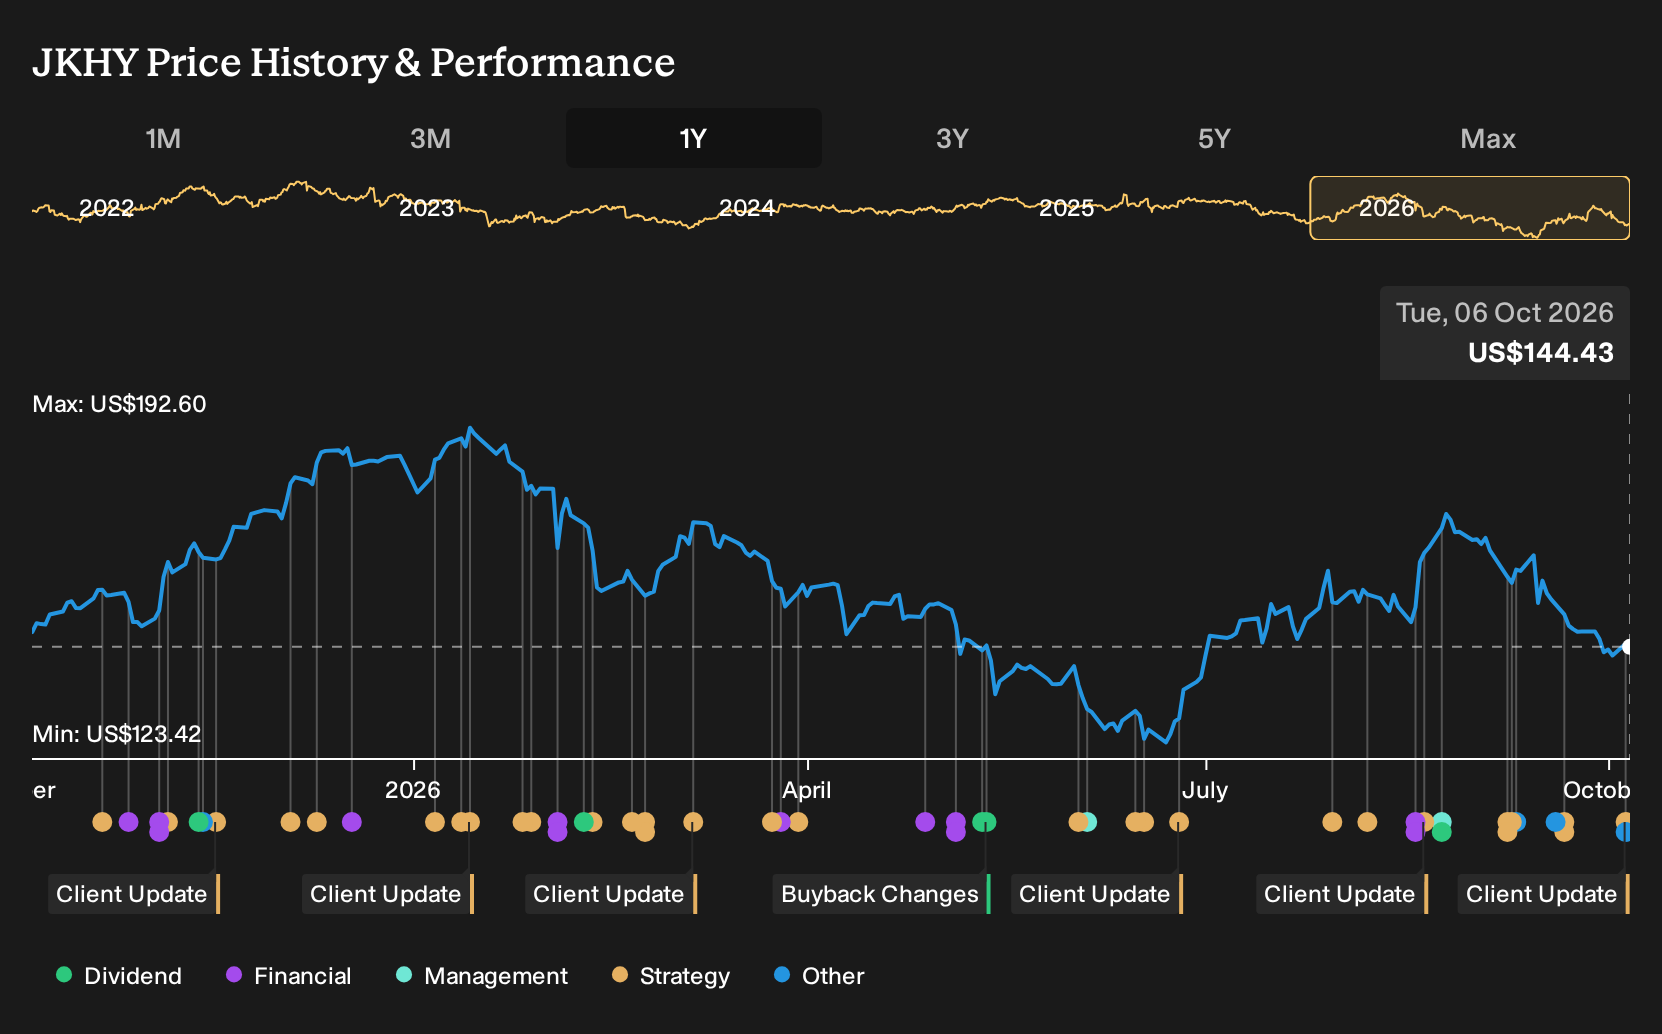
Uncover how Jack Henry & Associates' fair value indicates a 32% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community cluster between about US$163.7 and US$206.8, so some retail investors see Jack Henry & Associates as tightly ranged, while others lean toward a richer outcome. Set that alongside bank consolidation risk, as well as cloud and AI catalysts, then explore these viewpoints before forming your own stance.
Explore 2 other Jack Henry & Associates fair value estimates, including one that suggests it could be worth just $163.69.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Jack Henry & Associates research is our analysis highlighting 5 key rewards that could impact your investment decision.
- See our latest analysis for Jack Henry & Associates. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Jack Henry & Associates' overall financial health at a glance.
Looking for more investment ideas beyond Jack Henry & Associates?
Once you have a view on Jack Henry & Associates, it helps to widen the lens and compare it with other businesses that match your risk tolerance, income needs and return goals. The Simply Wall St Screener can surface candidates that fit different angles so you can build a watchlist that matches how you like to invest.
- If capital preservation matters to you, consider starting with 31 resilient stocks with low risk scores, which combine steadier risk profiles with more resilient fundamentals.
- For investors hunting for quality at a reasonable price, scan through 27 high quality undervalued stocks, which pair stronger balance sheets with more modest market expectations.
- Income focused portfolios may benefit from reviewing 8 dividend fortresses, which offer higher yields while still aiming to keep payouts supported by underlying cash flows.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com