
Entergy (ETR) Could Be 16% Below Fair Value As Texas CEO Change Draws Focus
Leadership change at Entergy Texas puts focus on ETR
Entergy (ETR) is back on investor radar after David Borde was appointed president and CEO of Entergy Texas, effective October 5, 2026, succeeding Eliecer Viamontes.
Recent trading tells a mixed story for Entergy. The share price is up 2.41% over the last day and 3.50% across the past week, yet it is down 3.75% over 30 days and 9.70% over 90 days. At the same time, a 10.25% one-year total shareholder return and very large three- and five-year total shareholder returns above 7x indicate that longer-term momentum remains strong, and the leadership change in Texas arrives as investors reassess both growth potential and risk around a US$103.25 entry point.
Scan how Entergy compares with other regulated utilities by reviewing the hand-picked 40 power grid technology and infrastructure stocks that could benefit as grid investment and leadership shifts come into focus.
Entergy now trades around US$103, with analyst targets sitting meaningfully higher. However, the valuation model implies a premium, raising the question of whether this gap reflects unwarranted caution or a warning flag on price.
Most Popular Narrative: 16% Undervalued
Entergy is trading at $103.25, while the most followed narrative sets fair value at about $122.68. The valuation debate centers on whether the long term demand and buildout story fully justifies that gap when discounted at 7.24%.
Substantial long term electricity demand growth from industrial development, population migration to the Gulf South, and large scale data center expansions in Entergy’s service territory now includes approximately 7 to 12 GW of hyperscale data center potential, 3 to 5 GW of traditional industrial demand, and signed agreements with AWS and Meta that together support the updated outlook for roughly 8.5% to 9% annual retail sales growth, which could lift regulated revenue and earnings over time.
See why 26 investors see Entergy as 16% undervalued.
Result: Fair Value of $122.68 (UNDERVALUED)
Still, the Entergy narrative depends on regulators approving large projects on workable terms, and on huge capital needs not forcing more expensive funding or heavier dilution.
Find out about the key risks to this Entergy narrative.
Another View: Entergy looks expensive on earnings multiples
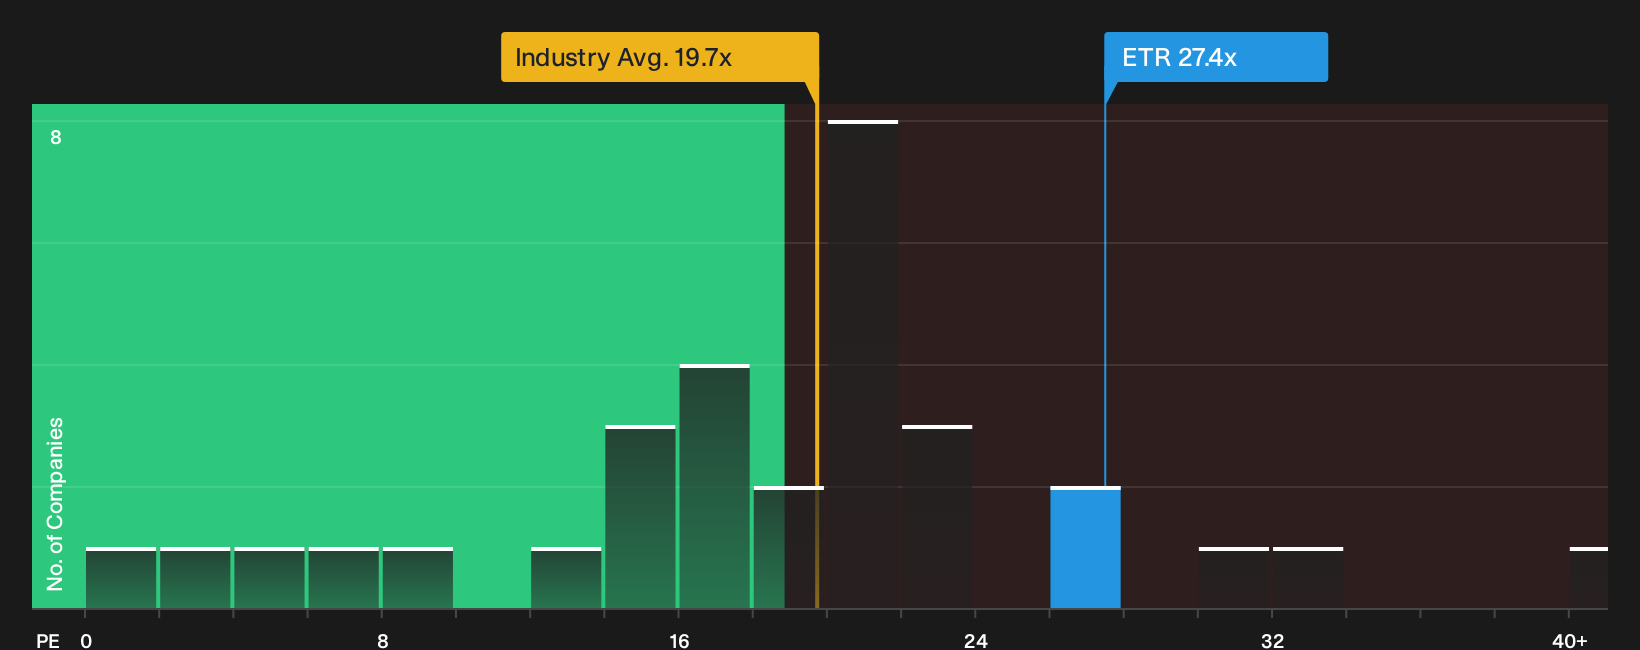
The first narrative paints Entergy as 16% undervalued on a fair value of $122.68. A simple P/E check tells a different story. The stock trades on 27.4x earnings, while the fair ratio is 23.5x and the US Electric Utilities group sits near 19.7x. This implies less room for error than the narrative suggests. Which signal do you trust when growth or regulation wobble?
To see how this earnings based view stacks up against a fuller valuation breakdown, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Plenty of optimism around Entergy sits alongside real concerns about risk and valuation wobble. Consider taking action, test the numbers yourself and weigh both sides by reviewing the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Entergy?
If Entergy has your attention, do not stop there. Broaden your watchlist now and give yourself more options before the next big move slips away.
- Target resilient balance sheets backed by consistent fundamentals using the list of solid balance sheet and fundamentals (25 results).
- Hunt for potentially mispriced opportunities by scanning the 27 high quality undervalued stocks.
- Build a cash flow focused watchlist by reviewing the 8 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com