
Wallenstam (OM:WALL B) Could Be 5% Above Fair Value After Årstaberg Push
Wallenstam (OM:WALL B) has just paired a fresh residential push in Årstaberg with a SEK 300 million green bond issue. Together, these moves link new housing development with energy focused upgrades in central Stockholm.
Wallenstam’s recent Årstaberg expansion and green bond issue come after a tougher run in the market, with the latest share price at SEK 35.6, a 30-day share price return down 12.44%, and a 1-year total shareholder return down 16.72%.
Scan other real estate stocks that pair energy-focused projects with new development pipelines by reviewing our curated list of list of solid balance sheet and fundamentals (206 results)
So is Wallenstam’s Årstaberg build out and green bond a sign that the underlying business is quietly executing while sentiment has turned colder, or is the share price simply catching up with fundamentals?
Most Popular Narrative: 5% Overvalued
Wallenstam’s latest close at SEK35.6 sits modestly above a narrative fair value of SEK34. This frames the recent Årstaberg activity against more cautious long term expectations based on a 9.76% discount rate.
Persistently higher interest rates and tighter monetary policy are likely to significantly increase Wallenstam's financing costs over time, especially as less of the loan book is currently interest rate hedged and more new loans are being issued at variable rates. This is expected to reduce net profit and constrain future earnings growth.
See why 0 investors see Wallenstam as 5% overvalued.
Result: Fair Value of SEK34 (OVERVALUED)
Still, if Wallenstam keeps occupancy high while managing financing and upgrade costs tightly, that combination could quickly challenge the cautious 5% overvaluation narrative.
Find out about the key risks to this Wallenstam narrative.
Another View: What Wallenstam’s P/E Is Really Saying
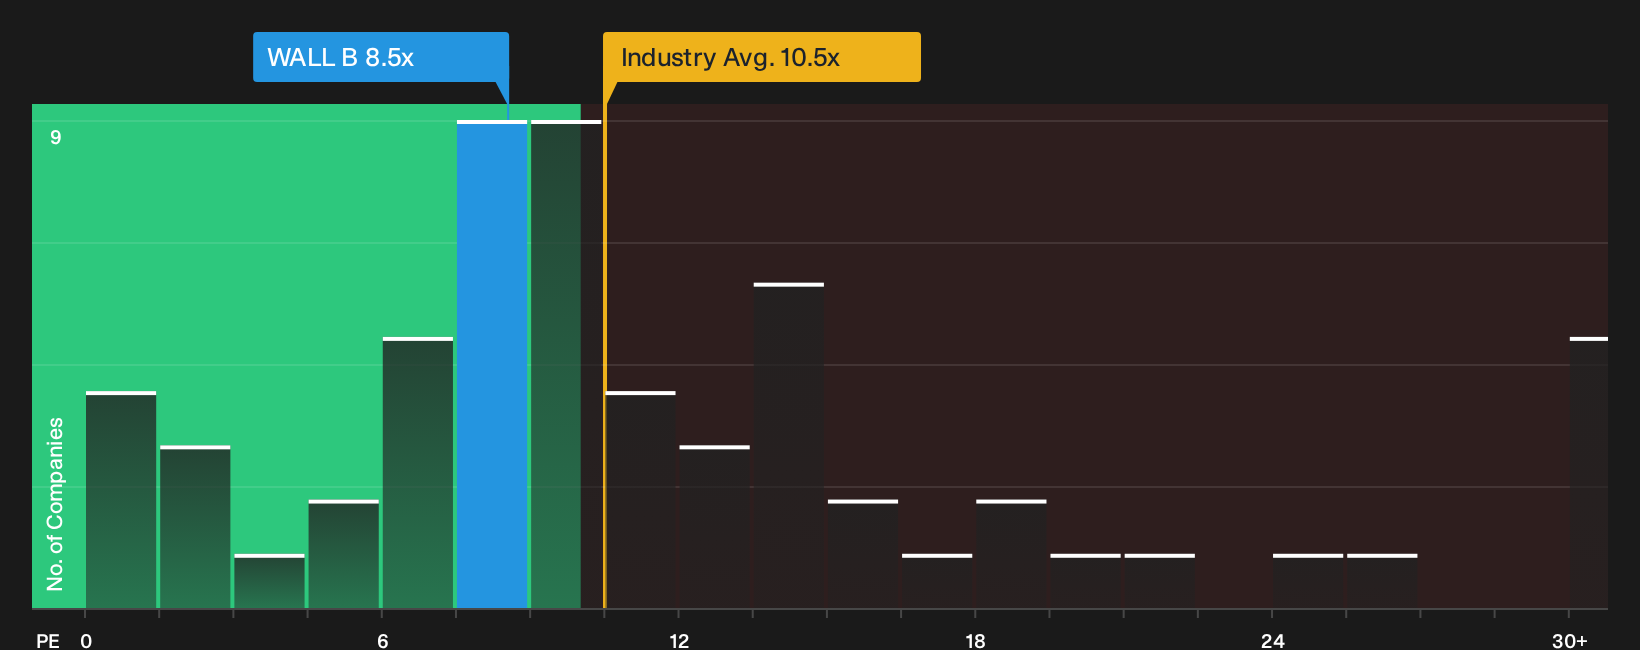
Step away from that SEK34 fair value for a moment and look at how the market is actually pricing Wallenstam today. On a P/E of 8.5x, the stock trades cheaper than the Swedish real estate sector at 10.5x and well below a 21.3x peer average, yet sits slightly above a fair ratio of 7.7x that our model suggests the market could lean toward over time.
That mix of relative discount and fair ratio premium points to a tug of war between perceived opportunity and valuation risk. It leaves a simple question for you as an investor: Is the modest P/E gap to the fair ratio a sign of overoptimism, or a small price for exposure to Wallenstam’s portfolio strength?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Wallenstam can feel confusing, so consider acting promptly, review the numbers for yourself, and weigh up the 3 key rewards and 3 important warning signs
Looking for more investment ideas beyond Wallenstam?
If Wallenstam has sharpened your focus on pricing, risk and quality, you can use that same mindset to spot other opportunities that might fit your portfolio better.
- Target strong fundamentals and healthy balance sheets by running your filters through our list of solid balance sheet and fundamentals (206 results) to see which businesses hold up under closer inspection.
- Hunt for mispriced opportunities using the 185 high quality undervalued stocks and compare potential upside with the quality metrics that matter most to you.
- Lock in potential income streams by checking the 164 dividend fortresses and weighing those yields against payout stability and your risk tolerance.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com