
Debt Refinance Could Be A Game Changer For Live Nation Entertainment (LYV)
- Live Nation Entertainment recently announced plans to issue US$840 million and €500 million of senior notes due 2032, with guarantees from certain domestic subsidiaries, to redeem existing 6.500% senior secured notes due 2027, cover offering costs, and support general corporate uses including possible further debt repayment.
- This refinancing move highlights Live Nation Entertainment’s focus on reshaping its capital structure, which directly affects interest costs, financial flexibility, and the amount of cash that can ultimately support venue, technology, and ticketing investments.
- We will now look at how Live Nation Entertainment’s new 2032 senior notes could influence its investment narrative, which is built around global expansion.
Live Nation Entertainment Investment Narrative Recap
For Live Nation Entertainment, the long term belief is that global demand for concerts, venue expansion and Ticketmaster’s scale can eventually support consistent profits, even though the business is currently loss making with net income of US$258.0 million in the red. The new 2032 notes do not alter that core thesis on their own. However, they sit in the background as the group leans into venue and technology projects.
The key near term swing factor remains execution on that heavy buildout while keeping fans, artists and sponsors engaged at scale. The largest risk still comes from regulatory and antitrust pressure around Ticketmaster, where existing consent decree obligations and legal processes could restrict contract terms, raise costs and limit how much benefit Live Nation Entertainment ultimately captures from its ticketing platform.
The most relevant recent development is the plan to issue US$840 million and €500 million of senior notes due 2032 to redeem the 6.500% senior secured notes due 2027 and for general corporate purposes, which may include further debt repayment. That matters because Live Nation Entertainment already relies entirely on external borrowing for liabilities and has no customer deposit funding.
This refinancing affects how much cash flow in future can be directed toward Venue Nation arena openings, international expansion and Ticketmaster product investments that support catalysts such as higher ticket volumes and sponsorship income. It also intersects with risk, since a business that is still unprofitable with a negative return on equity and ongoing legal exposure needs consistent operating performance to comfortably service a large debt stack over time.
What Analysts Are Baking Into The Live Nation Entertainment Story
Live Nation Entertainment's narrative projects US$34.4b revenue and US$996.6m earnings by 2029. This assumes 9.4% yearly revenue growth and an earnings swing of about US$1.25b from a loss of US$258.0m today.
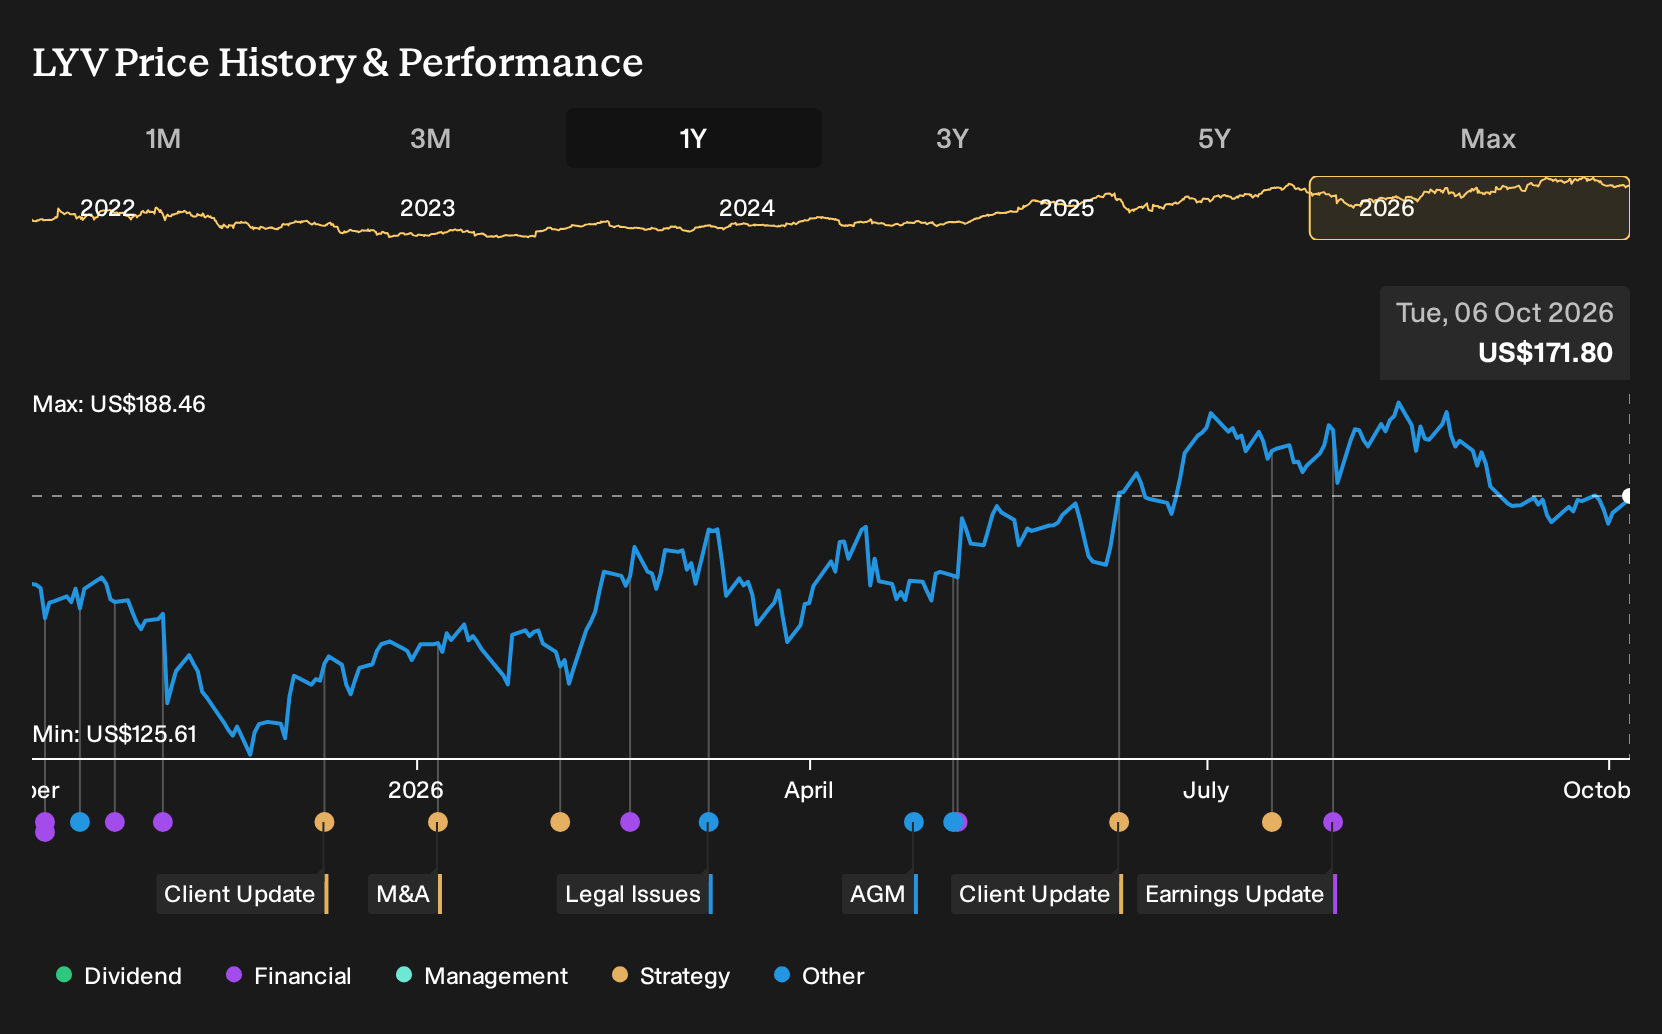
Uncover why Live Nation Entertainment's fair value indicates an 18% potential upside to its current price that could close sooner than investors expect.
Exploring Other Perspectives
Fair value estimates for Live Nation Entertainment from three Simply Wall St Community members cluster between US$170.52 and US$201.96, with all forecasts made before the new 2032 debt offering. You are weighing these varied views against live regulatory cases around Ticketmaster, which could reshape earnings power and make multiple viewpoints especially worth exploring.
Explore 2 other Live Nation Entertainment fair value estimates, including one that suggests an upside potential of as much as 18% from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider trusting your own analysis.
- A great starting point for your Live Nation Entertainment research is our analysis highlighting 1 key reward that could impact your investment decision.
- See our latest analysis for Live Nation Entertainment. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Live Nation Entertainment's overall financial health at a glance.
Looking For More Investment Ideas Beyond Live Nation Entertainment?
If Live Nation Entertainment has you thinking about balance sheets, earnings potential and long term debt profiles, it can be useful to line it up against other opportunities that share qualities you care about. The Simply Wall St Screener lets you filter for exactly that so you can quickly build a focused watchlist instead of scrolling through endless tickers.
- If you want a margin of safety, start with companies that screen as mispriced on fundamentals and see which ones show up in the 27 high quality undervalued stocks.
- If capital preservation matters more than big swings, look at businesses that pass tighter risk filters and see what appears in the 31 resilient stocks with low risk scores.
- If you are searching for quality that is not yet widely followed, scan through the 19 high quality undiscovered gems and see which stories deserve a closer look.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com