
What FactSet Research Systems (FDS) Partnership With SUBSCRIBE Means For Shareholders
- SUBSCRIBE announced a partnership with FactSet Research Systems, giving more than 8,600 clients integrated onboarding to private funds, digital subscription flows, and unified reporting for public and private holdings inside FactSet's platform.
- The tie-up embeds alternative investment workflows directly into existing FactSet research and analytics, which tightens client stickiness and pushes the product deeper into buy side processes.
- We will look at how FactSet's investment narrative around data platforms and margin discipline is shaped by this SUBSCRIBE integration.
FactSet Research Systems Investment Narrative Recap
To own FactSet Research Systems, you need to be comfortable with a data and workflow platform that leans on steady subscription sales, disciplined margins, and product depth across public and private markets. Recent results show sales of US$634.7m in Q4 and US$2.48b for the year, with earnings under pressure. The SUBSCRIBE deal fits the thesis that deeper workflows can support retention, but it does not radically change the near term earnings picture.
The key short term swing factor remains how pricing and client budgets behave while technology costs climb. Net income for the year declined to US$533.5m and profit margins compressed, so any further lift in cloud or software spending without matching revenue could bite. Main risks still sit with tighter asset manager and bank spending, plus higher tech investment, rather than this single partnership.
The announcement most tied to this story is the fiscal 2027 outlook. Management is guiding to revenue between US$2.60b and US$2.63b and a GAAP operating margin of 31% to 32%, with GAAP diluted EPS of US$17.00 to US$17.50. That framing matters for how you weigh the SUBSCRIBE integration because it shows where FactSet Research Systems thinks profitability can land while it invests in new workflows.
SUBSCRIBE’s private market tooling plugs directly into that plan. If the integration helps clients run more of their public and private reporting on the same platform, it supports the push toward higher value enterprise data feeds and workflow intensity that sits behind the margin guidance. The risk is execution. Technology expenses are already higher, so delays, weak client uptake, or added complexity around alternative data flows could dilute the margin targets that underpin the near term catalyst story.
FactSet Research Systems is framed by analysts as moving toward US$2.9b in revenue and US$707.0m in earnings by 2029, from current earnings of US$533.5m and a forecast revenue growth rate of 5.6% a year. That implies an earnings increase of about US$173.5m from earnings today to the consensus forecast, with the 2029 estimate year acting as the anchor for those projections.
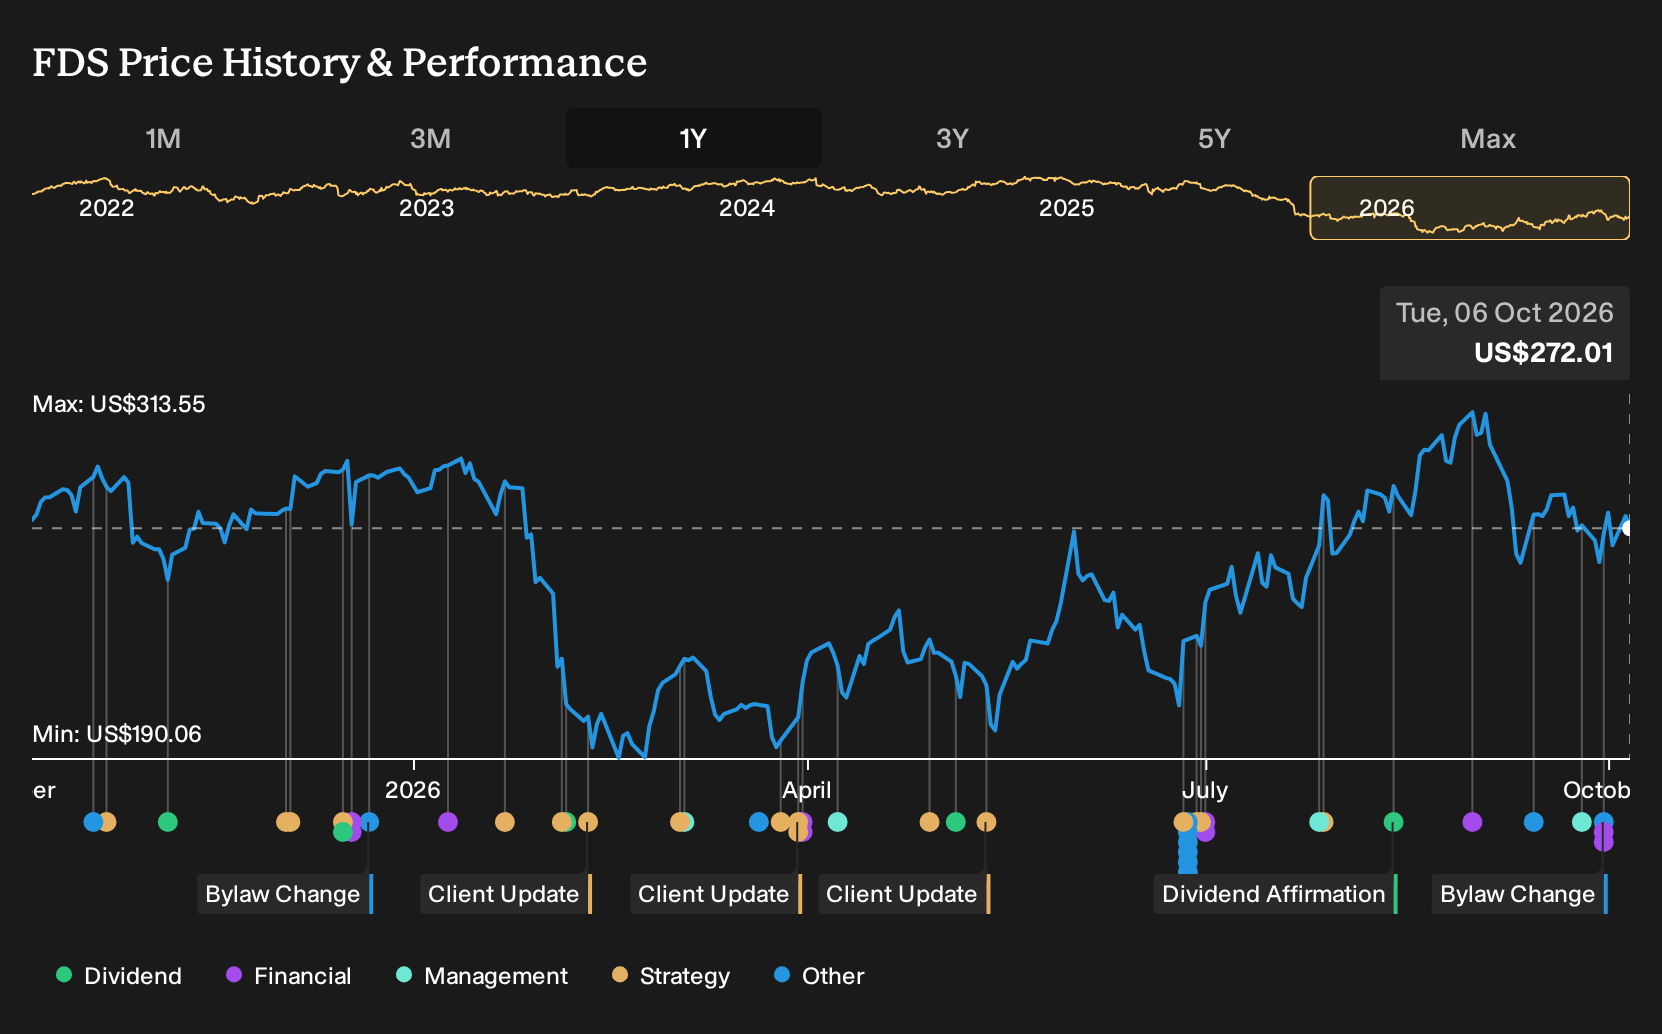
Uncover why FactSet Research Systems' fair value aligns with its current price.
Exploring Other Perspectives
One alternate take on FactSet Research Systems leans hard into AI competition risk rather than client budget pressure. The most cautious analysts were already assuming only about 5.5% annual revenue growth and earnings of roughly US$695.5m by 2029 on an 11.6x P/E, before this SUBSCRIBE partnership. Use that difference to explore how fresh news could eventually shift both narratives.
Explore 5 other FactSet Research Systems fair value estimates, including one that suggests as much as 23% downside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis and judgment.
- A great starting point for your FactSet Research Systems research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for FactSet Research Systems. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate FactSet Research Systems' overall financial health at a glance.
Looking for more FactSet Research Systems sized ideas?
If the FactSet Research Systems story has you thinking about portfolio balance, use that same mindset to scan a wider field of potential opportunities with the Simply Wall St Screener.
- For investors who want stability to sit alongside higher risk holdings, consider a 31 resilient stocks with low risk scores that already score well on resilience and financial strength.
- If dependable income is a priority, focus on payout strength and cash coverage by reviewing a curated set of 8 dividend fortresses that may suit an income focused approach.
- When you want quality without stretching the valuation, aim your search at a universe of 27 high quality undervalued stocks that combine fundamentals with more measured pricing.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com