
What Alm. Brand Shares Earnings Outlook Upgrade Means For Shareholders
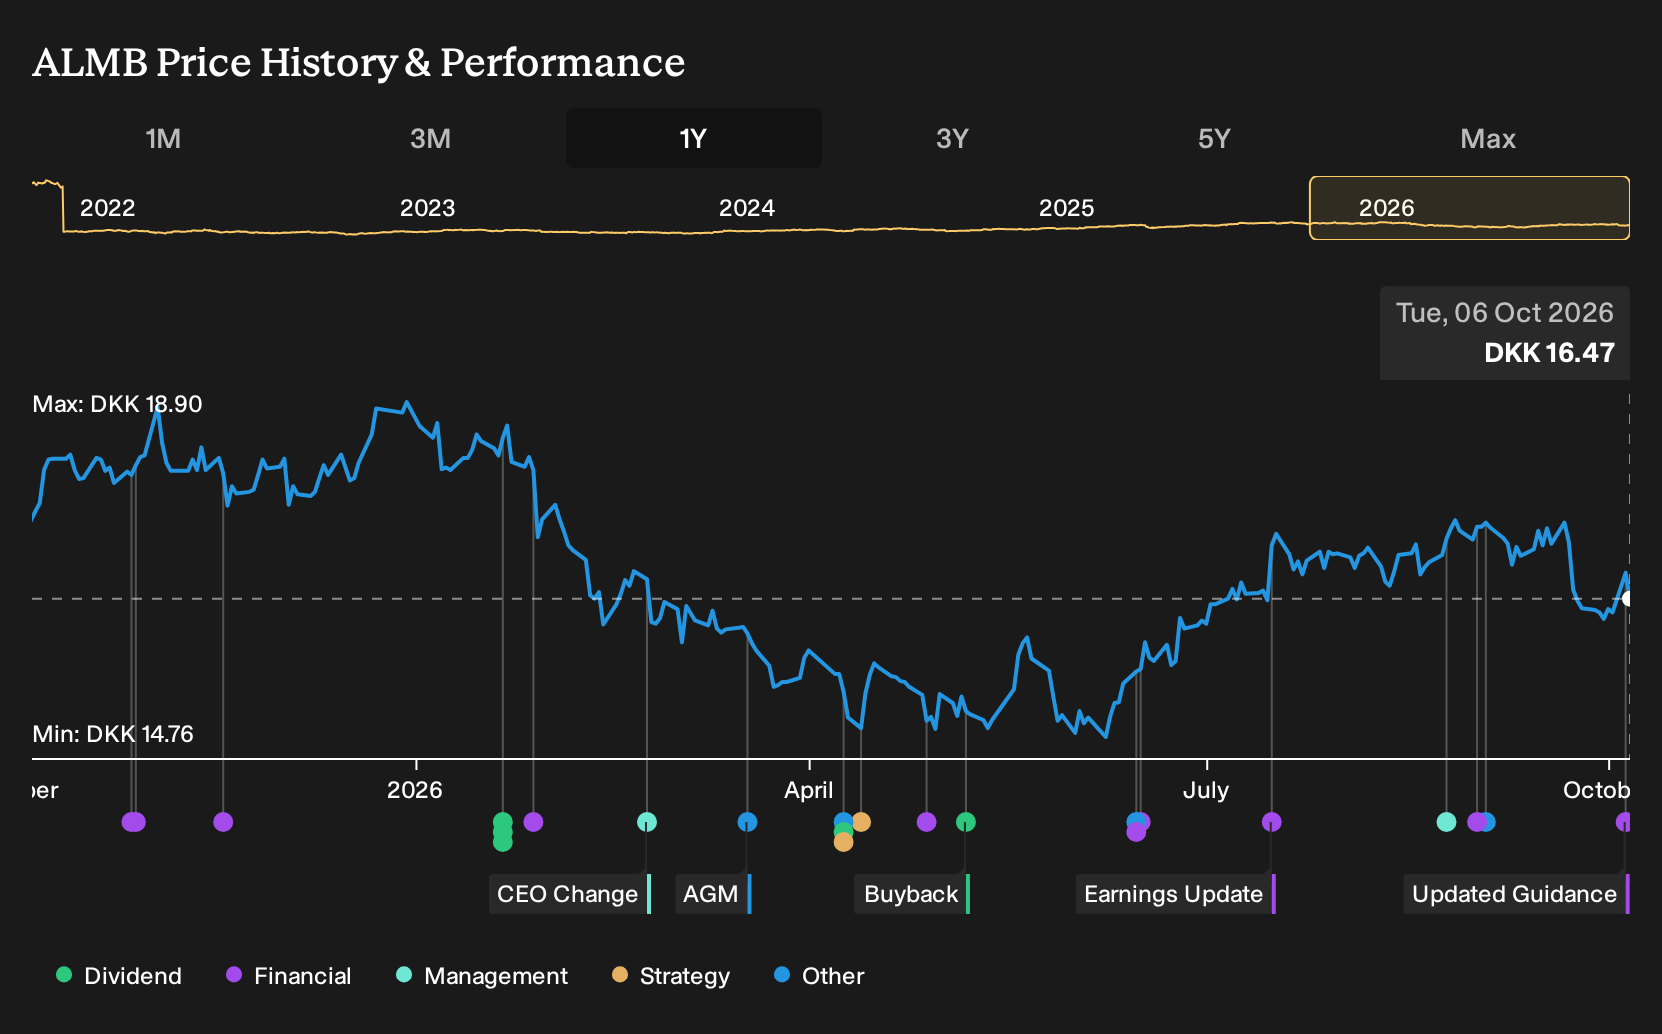
- Alm. Brand raised its 2026 insurance service result guidance in early October, lifting the full year target range by DKK 250 million to DKK 1.5-1.6 billion after reporting a favourable third quarter performance.
- The sharper earnings outlook points to improved underwriting and cost execution in the core insurance book, which directly affects how investors may weigh Alm. Brand’s ability to fund dividends, buybacks, and future efficiency projects from operating cash flows.
- We will now look at how Alm. Brand’s stronger full year guidance could reshape the existing investment narrative around earnings quality.
Alm. Brand Investment Narrative Recap
To own Alm. Brand, you need to be comfortable with a relatively high payout model and a focus on improving insurance operations rather than chasing fast top line expansion. The upgraded 2026 insurance service result guidance to DKK 1.5-1.6b suggests underwriting, repricing and synergies are tracking ahead of earlier expectations. The key near term swing factor remains execution on pricing and claims, especially in motor. The biggest risk still looks tied to whether recent claims patterns and cost efficiency hold, given the high payout ratio reduces room for error.
The higher guidance does not remove structural pressures. Competition in personal and commercial lines, a tax rate above the statutory level and pending capital model work through the partial internal model all continue to matter for Alm. Brand. If claims frequency, repricing and synergy delivery stay on course, that supports near term earnings quality. If they slip, the combination of high capital return ambitions and a payout ratio close to 100% could strain flexibility.
The fresh guidance upgrade is the clearest recent signal for investors to focus on. Management now sees the 2026 insurance service result DKK 250m higher than previously guided, at DKK 1.5-1.6b excluding Q4 run offs. That directly ties into the short term catalyst around earnings quality. It shows the underlying book is currently running ahead of prior projections after the third quarter. Investors can use that as a real time check on earlier expectations for margin improvement from repricing and synergies.
The SEB Autumn seminar appearance on 1 October 2026 sits in the background as a supporting event rather than a separate catalyst. It mainly matters because it gave Alm. Brand a platform to articulate the same themes investors are watching. Those include personal lines expansion with bank partners, the impact of motor repricing and the balance between cost savings, capital strength and a high payout ratio. The guidance hike then put a firmer number against that story and sharpened the debate around both upside potential and the risks.
Alm. Brand's current analyst narrative points to DKK 13.4b in revenue and DKK 1.6b in earnings by 2029, with revenue assumed to stay broadly flat and earnings rising from DKK 1.2b today. This implies a DKK 0.4b increase in profit against an essentially stable top line.
Uncover why Alm. Brand's fair value indicates a 20% potential upside to its current price that could close sooner than many investors expect.
Exploring Other Perspectives
The Simply Wall St Community has only two fair value views on Alm. Brand, stretching from DKK 19.70 to about DKK 28.06 per share, so you already see a broad gap in expectations. Consider these alongside the guidance upgrade and the high payout ratio, then explore how differing views on claims risk and capital flexibility shape your own stance.
Explore another Alm. Brand fair value estimate, including one that suggests it could be worth just DKK19.70.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis and judgment.
- A great starting point for your Alm. Brand research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Alm. Brand. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Alm. Brand's overall financial health at a glance.
Looking for more Alm. Brand style ideas?
If Alm. Brand's payout profile and guidance reset has sharpened your thinking, it can help to line it up against other opportunities using the Simply Wall St Screener. That way you compare like for like and decide where the risk and reward trade off feels most comfortable.
- If you care most about finding companies that look cheap on quality fundamentals, start with a focused set of 185 high quality undervalued stocks that already screen for both strength and price.
- If balance sheet resilience matters more to you than headline yield, filter for businesses with low leverage and healthy buffers using the list of solid balance sheet and fundamentals (206 results).
- If you are hunting for ideas that the market may not be paying full attention to yet, cast a wider net across the 615 high quality undiscovered gems and see which stories deserve a closer look.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com