
Southern (SO) Heads To The American Growth Summit, Is It Still Below Fair Value?
Southern (SO) heads into its American Growth Summit appearance in Washington on 29 September 2026, with CEO Christopher C. Womack addressing investors as the utility’s shares trade near US$83.79 and carry a market value around US$96.3b.
Southern’s share price has edged higher over the past week, but that short burst of momentum follows a 30 day share price return that fell 4.9% and a 90 day share price return that declined 13.9%, even as total shareholder return over five years reached 62.45%.
Look beyond Southern at the summit and compare other regulated utilities and infrastructure plays using our hand picked 39 power grid technology and infrastructure stocks
After that recent slip yet a share price still near US$83.79, the real question for Southern is where fair value sits between its current quote and a wide range of analyst and intrinsic estimates.
Most Popular Narrative: 16% Undervalued
Southern is trading below the most widely followed fair value estimate of about $99.76, so the spotlight falls on what could justify that gap and whether the growth story can carry the current premium P/E over the long haul.
Accelerating large-load and data center activity in Southern’s territories, including more than 17 GW of contracted large-load agreements for the mid 2030s, a late stage pipeline of about 8 GW and a prospective funnel above 75 GW, points to a long runway of usage driven revenue and regulated rate base growth that may not be fully reflected in current valuation.
See why 65 investors see Southern as 16% undervalued.
Result: Fair Value of $99.76 (UNDERVALUED)
Still, the Southern story can be knocked off course if large data center contracts slow or if heavy DOE-backed and equity funding pressures future earnings power.
Find out about the key risks to this Southern narrative.
Another View: Southern Through The DCF Lens
While the popular narrative pegs Southern around a $99.76 fair value using analyst earnings and multiples, the Simply Wall St DCF model lands in a very different place. On that future cash flow view, SO at $83.79 screens as expensive versus an estimated value of about $3.73. Which approach do you trust more when the gap is this wide?
Our DCF model is only as useful as the assumptions behind it, so it is worth understanding how it treats growth, capital spending and discount rates before leaning on it too heavily for decisions. Look into how the SWS DCF model arrives at its fair value.
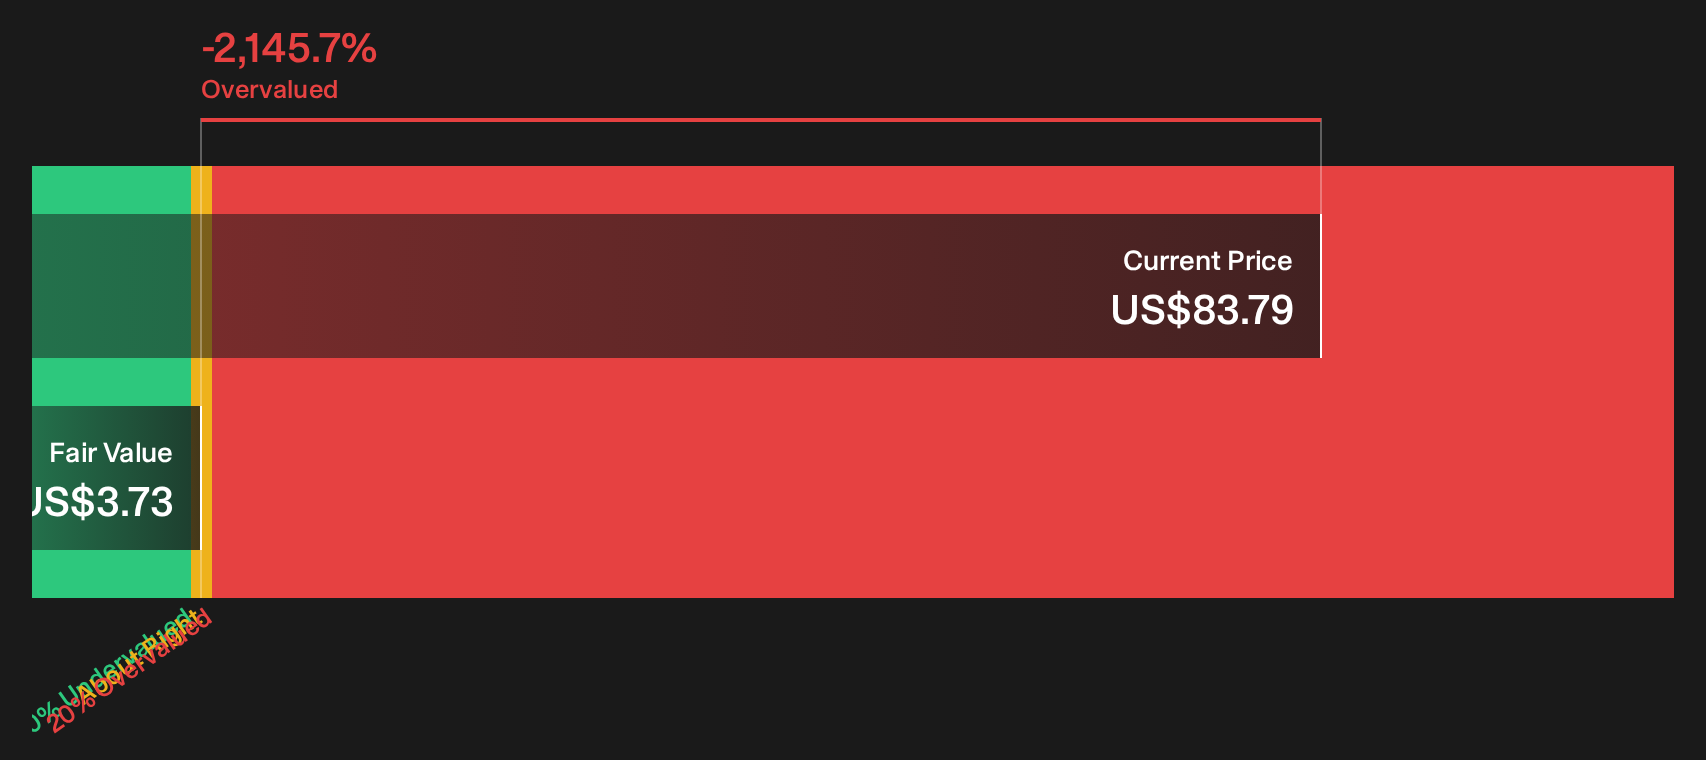
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Southern for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 27 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around Southern can make the story feel murky. Move fast, review the full picture, and weigh both sides using 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Southern?
If Southern no longer feels like the only place to focus, you could broaden your watchlist and let fresh opportunities come to you instead of reacting late.
- Target potential bargains early by scanning our curated pool of quality companies trading below intrinsic value using the 27 high quality undervalued stocks.
- Prioritise strength and resilience by filtering for businesses with sturdy finances and dependable balance sheets through the list of solid balance sheet and fundamentals (25 results).
- Spot future leaders before they hit the spotlight by reviewing a hand picked 19 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com