
Should Phase 3 Psoriasis Win Require Action From Takeda Stock Investors?
- Takeda Pharmaceutical released Phase 3 LATITUDE data in 2026 showing its oral TYK2 inhibitor zasocitinib achieved higher complete skin clearance rates than deucravacitinib and apremilast in adults with moderate-to-severe plaque psoriasis, with regulatory reviews ongoing in the U.S. and Europe.
- The psoriasis results highlight how a once-daily pill that produced rapid, durable skin clearance in hard-to-treat areas could reshape Takeda Pharmaceutical’s dermatology franchise mix and future product launch priorities.
- We will now assess how Takeda Pharmaceutical’s investment narrative could shift if zasocitinib’s head-to-head psoriasis data leads to a meaningful commercial opportunity.
Takeda Pharmaceutical Investment Narrative Recap
To own Takeda Pharmaceutical, you need to believe that its late stage pipeline can gradually outweigh pressure from generics, pricing reform and a still heavy debt load. The psoriasis readout for zasocitinib reinforces that argument at an operating level, since it adds another potential branded pillar alongside existing gastroenterology and rare disease therapies.
In the near term, the key swing factor is how efficiently Takeda can convert its R&D portfolio into approved, reimbursed medicines while managing cash flow and debt from the Shire deal. The biggest immediate risk remains pipeline underperformance or delays, which could prolong current profit weakness and keep dividend coverage and leverage in a tight spot.
The most relevant recent update is the new Phase 3 LATITUDE data for zasocitinib in moderate to severe plaque psoriasis. Those results, along with ongoing regulatory reviews in the U.S. and Europe, give Takeda Pharmaceutical another potential growth asset that sits alongside its existing brands in gastroenterology, oncology and neuroscience.
For catalysts, investors are watching whether zasocitinib can secure timely approvals and then build meaningful usage in psoriasis. Over time, they are also monitoring its potential in psoriatic arthritis and other immune conditions under study. Execution risk is real, including competitive responses, possible pricing pressure and the need to support launches while Takeda still carries material debt and unprofitable group earnings.
Takeda Pharmaceutical Consensus Expectations Around Zasocitinib
Analysts currently frame Takeda Pharmaceutical as a turnaround story that leans on steady top line expansion and a sharp swing in profitability. The headline view is for revenue to rise at 2.5% a year over the next three years while profit margins move from a loss position of 3.5% today to 8.1% by year three. That margin shift does a lot of heavy lifting in the earnings model and gives late stage assets like zasocitinib more leverage if they reach scale.
On current estimates, the Street expects Takeda to move from a loss of ¥163.4b today to earnings of ¥401.3b by 2029, with some analysts pencilling in as much as ¥628.9b and others closer to ¥270.8b. That swing of roughly ¥564.7b from current losses to forecast profits is material and shows how sensitive the story is to execution on the broader pipeline, pricing, and cost base rather than psoriasis alone. For investors, the spread between bullish and cautious forecasts underlines how much uncertainty still sits around the earnings path.
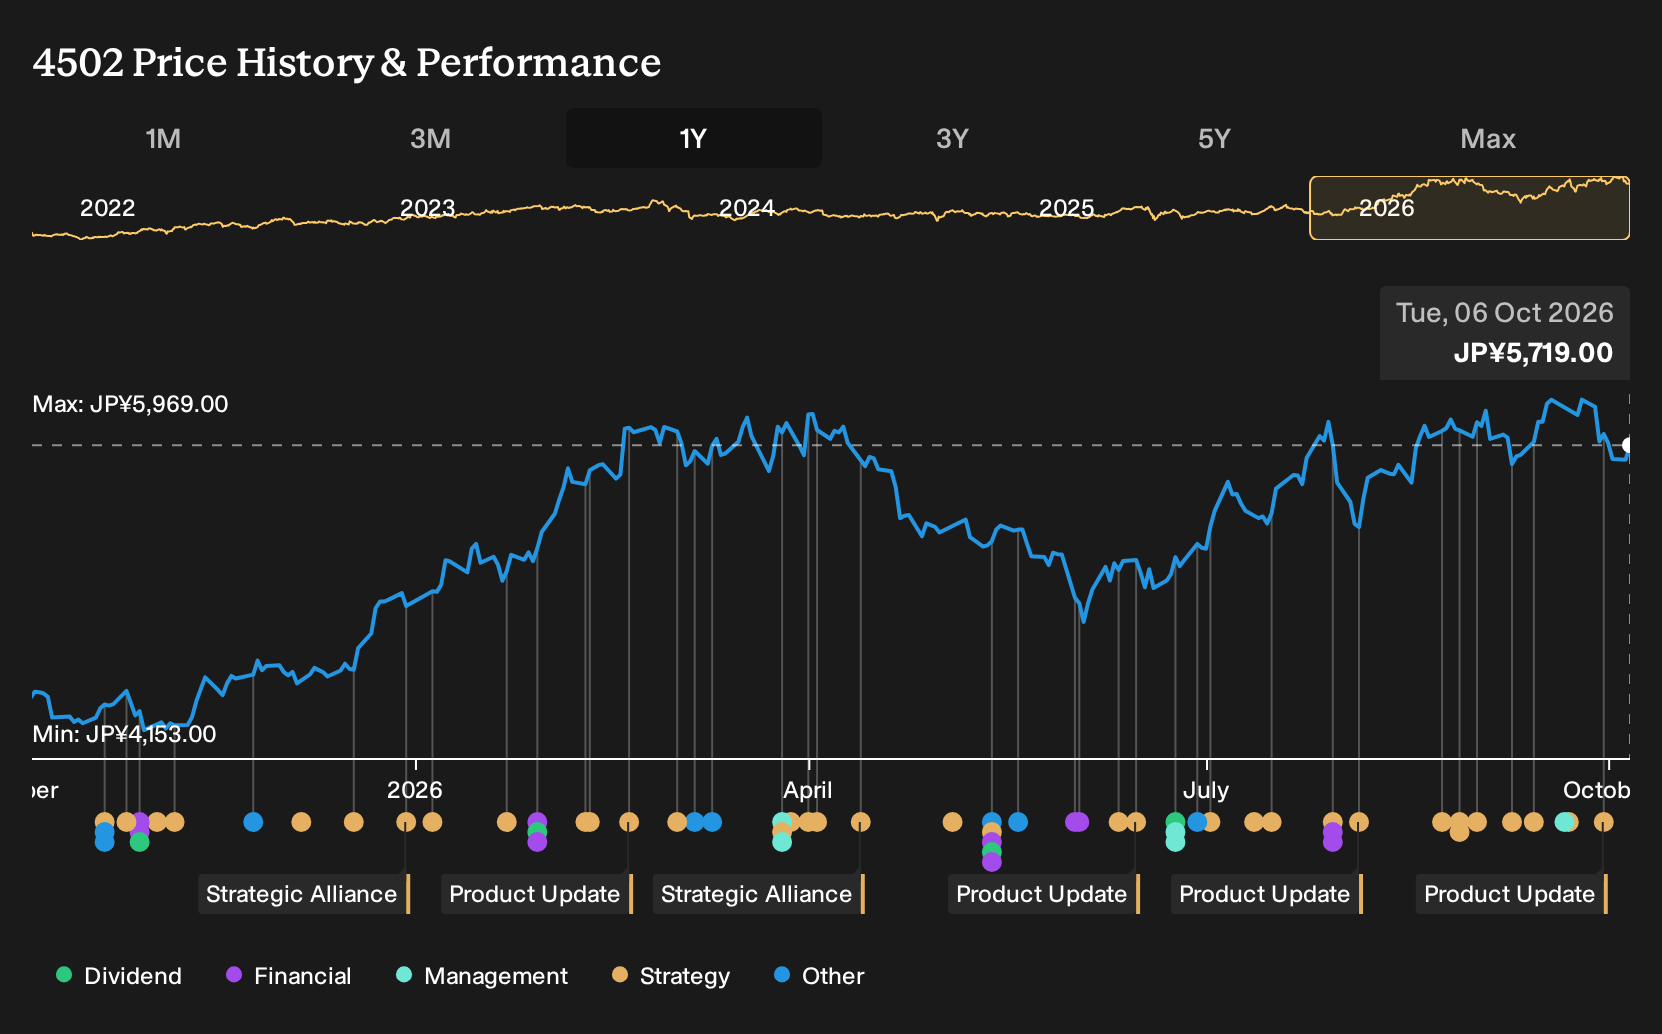
Valuation work built on those numbers assumes that by 2029 Takeda Pharmaceutical delivers ¥4,976.1b of revenue and ¥401.3b of net profit and that the shares trade on a P/E multiple of 30.1x. That prospective multiple is roughly double the current 15.3x level quoted for the wider Japanese pharmaceuticals sector. The implied premium rests on both the margin turnaround and confidence in late stage programs such as zasocitinib. With the stock at ¥5,753.0 and the average target at ¥6,603.31, analysts are mapping out a 12.9% gap that investors need to judge against the risks around competition, regulation and the company’s still meaningful debt load.
Takeda Pharmaceutical is not expected to materially change its share count over the next three years, which keeps the focus on organic growth and operating leverage rather than financial engineering. The analyst models rely on a 5.0% discount rate to bring future cash flows back to today. This is a reminder that small changes in assumptions about rates, margins or uptake for drugs like zasocitinib can move fair value estimates quite a bit. For anyone weighing the stock, the key question is how comfortable you are with these embedded expectations and where your own numbers would sit inside or outside that analyst range.
Takeda Pharmaceutical's narrative projects ¥4,976.1b revenue and ¥401.3b earnings by 2029. This requires 2.5% yearly revenue growth and an earnings increase of roughly ¥564.7b from a current loss of ¥163.4b.
Uncover why Takeda Pharmaceutical's fair value indicates a 15% potential upside to its current price before the discount closes.
Exploring Other Perspectives
You are seeing two very different stories about Takeda Pharmaceutical around zasocitinib. The bullish camp leans hard into pipeline strength. Before this psoriasis news, the highest analysts were already modeling revenue of ¥5,072.4b and earnings of ¥423.0b by 2029. If zasocitinib over delivers, that optimistic script could stretch even further, while more cautious voices may revisit their lower earnings paths. Exploring both ends of that range can help you decide which version seems closer to your own expectations.
Explore 2 other Takeda Pharmaceutical fair value estimates, including one that suggests as much as 151% upside from the current price!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Takeda Pharmaceutical research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Takeda Pharmaceutical. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Takeda Pharmaceutical's overall financial health at a glance.
Looking For More Investment Ideas Beyond Takeda Pharmaceutical?
If the zasocitinib story has you rethinking how much late stage pipelines can reshape a portfolio, it can be useful to widen the lens beyond Takeda Pharmaceutical and scan for other opportunities that fit your risk and return preferences.
- For investors who want growth potential without abandoning balance sheet discipline, consider screening for 75 high quality undiscovered gems that pair strong fundamentals with under-the-radar coverage.
- If capital preservation and steadier price moves matter most to you, filter the market for 22 resilient stocks with low risk scores that score well on resilience and downside protection.
- Income focused readers who like to get paid while they wait can zero in on 21 dividend fortresses that combine higher yields with an emphasis on durability.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com