
What Eutelsat Communications Taught You About Stories That Break
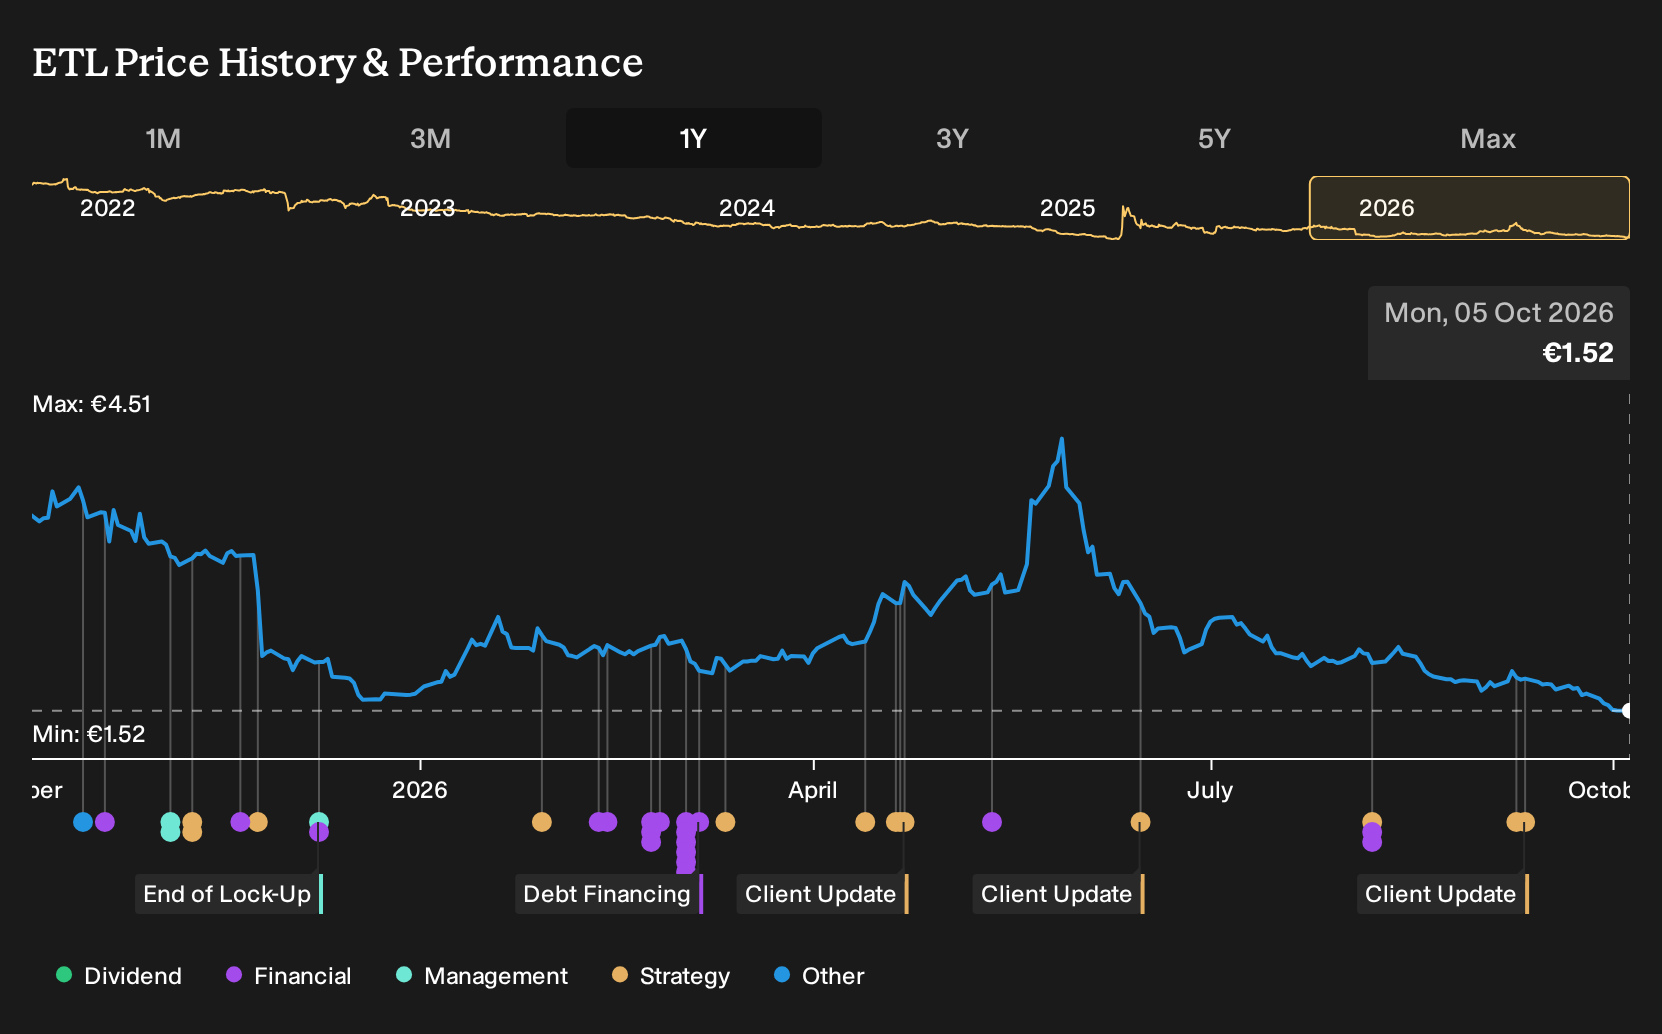
If you had backed Eutelsat Communications for its GEO plus LEO promise when analysts were debating between a bullish 3 year ramp and a more cautious 2.7% revenue path, the outcome has been painful. Investors who held Eutelsat Communications over the past year are down 45.8%, including dividends. The key question now is which parts of that earlier case, from margin recovery to a 44.5x or 23.6x P/E, were always fragile and which assumptions still hold.
The useful thing about a Narrative is that the reasoning is checkable: the assumptions sit beside the argument, and together they imply an estimated Fair Value you can disagree with.
If the move has made Eutelsat Communications harder to judge, start where the gap is still open and scan 186 high quality undervalued stocks.
The Two Stories Investors Were Choosing Between On Eutelsat Communications
The shares cost €3.71 at the start of the period, and anyone looking at Eutelsat Communications then was choosing between two very different but reasonable stories.
On the bullish side, the Fair Value was set at €6.7, built on the idea that a hybrid GEO plus LEO network could support 4.3% annual revenue growth and a future P/E assumption of 44.5x.
The more cautious bear narrative pointed to a Fair Value of €3.39, using 2.7% annual revenue growth and a 23.6x future P/E, and highlighting pressure from GEO segment decline as a key risk.
What The Results Changed For The Eutelsat Communications Thesis
Eutelsat Communications secured lead responsibility for the LEO segment of Europe’s IRIS² programme and reported LEO revenue of €297 million, about 25% of total sales, alongside a completed €5b refinancing and large government contracts. At the same time, the group still reported a loss and net margin fell from -32.7% to -34.3%. The evidence cut both ways.
The key assumption here was that GEO plus LEO growth would eventually repair profitability. For any similar satellite stock, track whether rising LEO revenue share actually brings net margin closer to break-even in reported results.
What Eutelsat Communications' New Price Already Assumes
Today Eutelsat Communications trades at €1.52, after a 45.8% loss over the past year. The selected Narrative treats this drop as more pessimistic than its Fair Value, built on IRIS²-related Low Earth Orbit build-out and capital recycling plans.
Analysts behind that Narrative lean on LEO-driven revenue, tighter spending and asset sales. A buyer today would need to believe that IRIS² capex and OneWeb expansion convert into higher margin LEO capacity without GEO weakness and funding costs eroding those gains.
"The signing of the SpaceRISE consortium agreement and the IRIS² multi-orbit constellation project is a catalyst for growth, as it represents significant investment in future satellite infrastructure and is expected to generate around €6.5 billion in revenues over a 12-year concession period, which will positively impact future revenue streams."
One Narrative has put a figure on that disagreement. → See the Narrative with its higher Fair Value, assumptions and all
Before The Next Story Makes Headlines
This company's disappointment is already part of the story. Your next idea could come from looking where the price and the possibilities still seem far apart. Here are three companies priced below our estimates.
- Company 1 - 30% below our estimate - supplies power and thermal solutions supporting intensive data center infrastructure expansion.
- Company 2 - 25% below our estimate - sells consolidated cybersecurity tools enterprises adopt as digital and AI risks grow.
- Company 3 - 49% below our estimate - services marine engines under extended agreements as cleaner fuel systems gain adoption.
Those are three of them. See all 206 companies with the balance sheet to back it up →
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com