
What GigaCloud Technology (GCT) Earnings Beat Means For Shareholders
- GigaCloud Technology reported revenue of $412 million with earnings per share of $1.16, alongside strong year over year gains and rapid growth in European gross merchandise volume.
- The business is leaning on its expanding marketplace and progressing New Classic integration, which are helping deepen international reach and support higher platform efficiency.
- This article explores how GigaCloud Technology's record earnings per share may influence its investment narrative and how investors might think about its future growth potential.
Scan beyond GigaCloud Technology and size up other fast growing platforms and marketplaces with the hand picked ideas in our 19 high quality undiscovered gems.
GigaCloud Technology Investment Narrative Recap
To own GigaCloud Technology, you need to believe its B2B marketplace can keep scaling across the US, Europe, and Asia while logistics integration supports that growth. The latest revenue of US$412 million and EPS of US$1.16 reflect that thesis on execution. The key short term focus is continued volume and take rate traction on the marketplace, especially in Europe.
The biggest risk stays the same. Heavy dependence on European momentum and exposure to tariffs and shipping disruption can squeeze margins or slow volumes. Recent results and the share price move of 1.69% do not remove those pressures, although they give management a bit more operational breathing room.
The most relevant recent update is the quarter where GigaCloud Technology posted US$412 million of revenue, up 28% year over year, with record EPS of US$1.16. That result sits at the center of the current story. It shows the business handling higher throughput while integrating more complex logistics and marketplace activity.
European GMV rising 66% year over year matters because it directly touches both the main opportunity and the key risk. Stronger international volumes support the case for continued earnings growth and efficiency gains. At the same time, it increases exposure to any regulatory or logistics issues in that region, so execution quality and network reliability remain crucial to watch.
GigaCloud Technology's current analyst story points to revenues of US$2.0b and earnings of US$221.8 million by 2029. That narrative leans on 10.0% yearly revenue growth and an earnings increase of about US$65.7 million from US$156.1 million today, with 2029 set as the main forecast year.
Discover why GigaCloud Technology's fair value signals a 12% potential upside to its current price, which could close sooner than many investors expect.
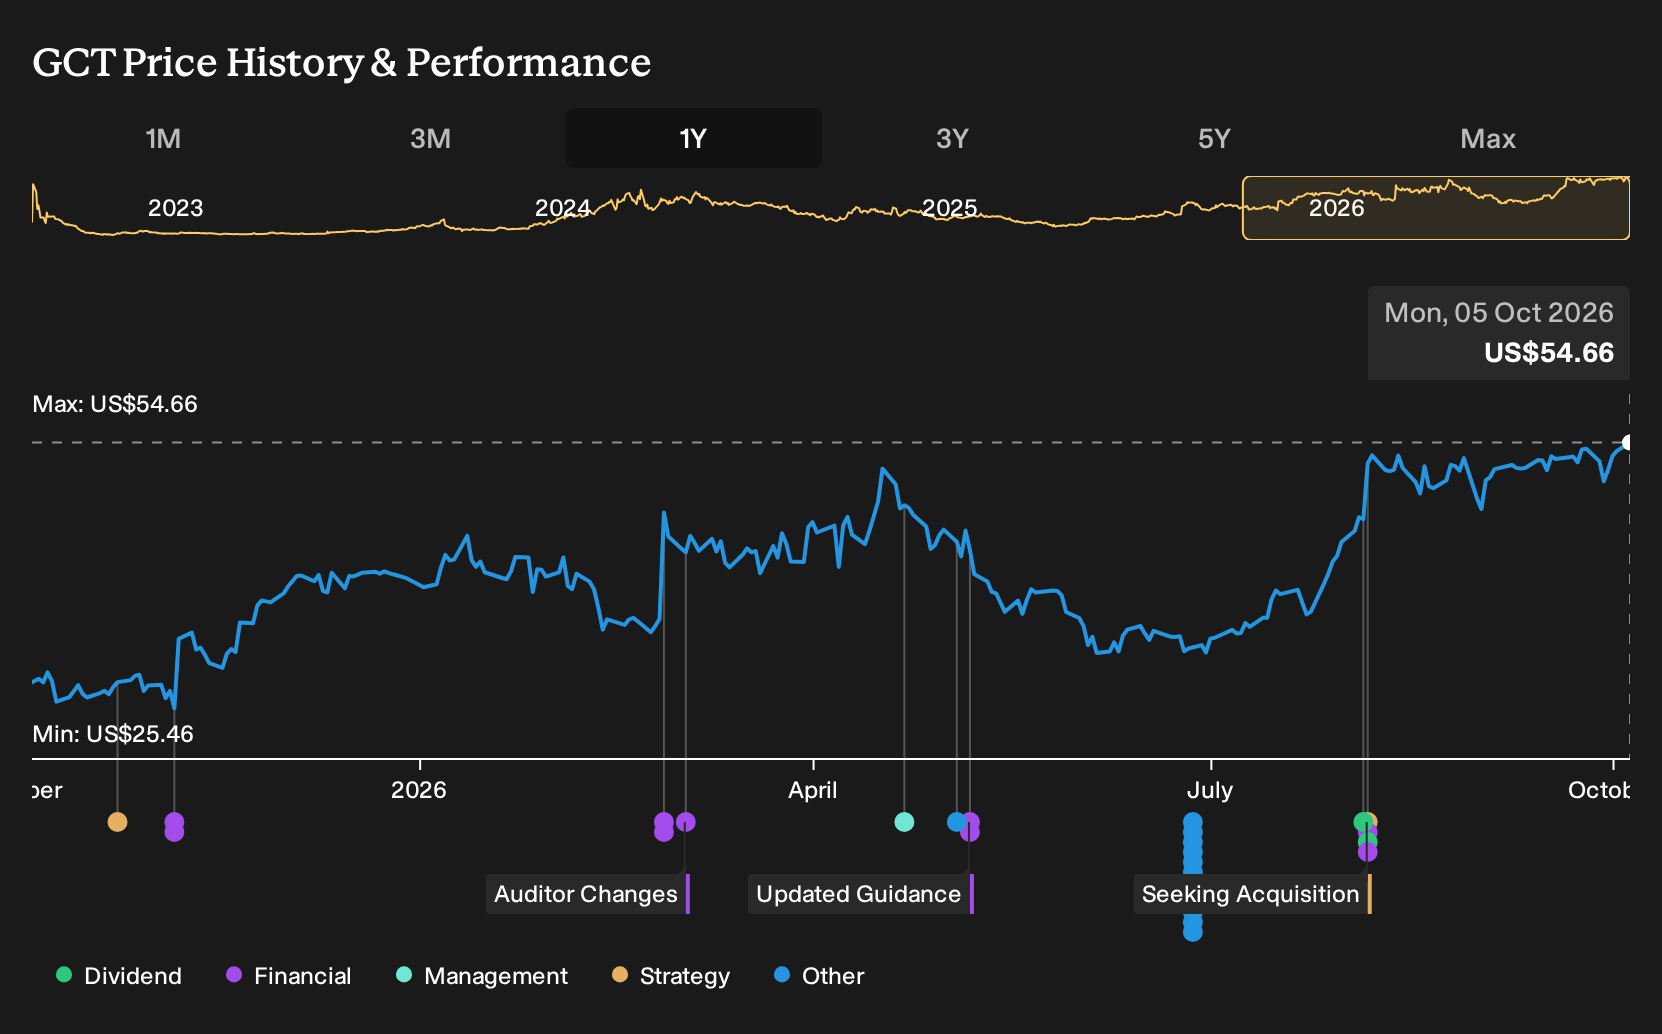
Exploring Other Perspectives
For GigaCloud Technology, the bullish twist is the aggressive buyback story. The most optimistic analysts were already baking in earnings of about US$252.4 million on US$2.0b of revenue by 2029, helped by expected share count declines. Those views came before this EPS beat, so you may see forecasts and opinions shift in very different directions.
Explore 3 other GigaCloud Technology fair value estimates, including one that suggests as much as 51% potential upside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your GigaCloud Technology research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for GigaCloud Technology. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate GigaCloud Technology's overall financial health at a glance.
Looking For More Ideas Beyond GigaCloud Technology?
If GigaCloud Technology is already on your radar, it can help to set it alongside other opportunities with clear financial traits so you can compare quality, risk, and income potential quickly.
- If you want to focus on financial strength and cleaner balance sheets, scan a curated list of solid balance sheet and fundamentals (25 results) to see which businesses match that profile.
- For readers who care most about resilient returns with less volatility, consider a basket built from 31 resilient stocks with low risk scores that screens for sturdier fundamentals.
- If income is your priority, you can zero in on cash generating payers by starting with our shortlist of 7 dividend fortresses that already clear a 5% yield hurdle.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com