
Will Revenue Miss Change Arthur J. Gallagher Stock Narrative
- Arthur J. Gallagher recently reported quarterly revenue of US$4.00b, up 24.3% year on year, alongside a narrow earnings per share beat, while revenue came in slightly below analyst expectations.
- The mix of strong top line expansion and a small shortfall versus forecasts highlights how tightly execution, cost discipline, and organic momentum are being monitored in Arthur J. Gallagher’s brokerage and risk management operations.
- We will now explore how Arthur J. Gallagher's strong 24.3% revenue growth, alongside a slight revenue miss, could influence its investment narrative.
Arthur J. Gallagher Investment Narrative Recap
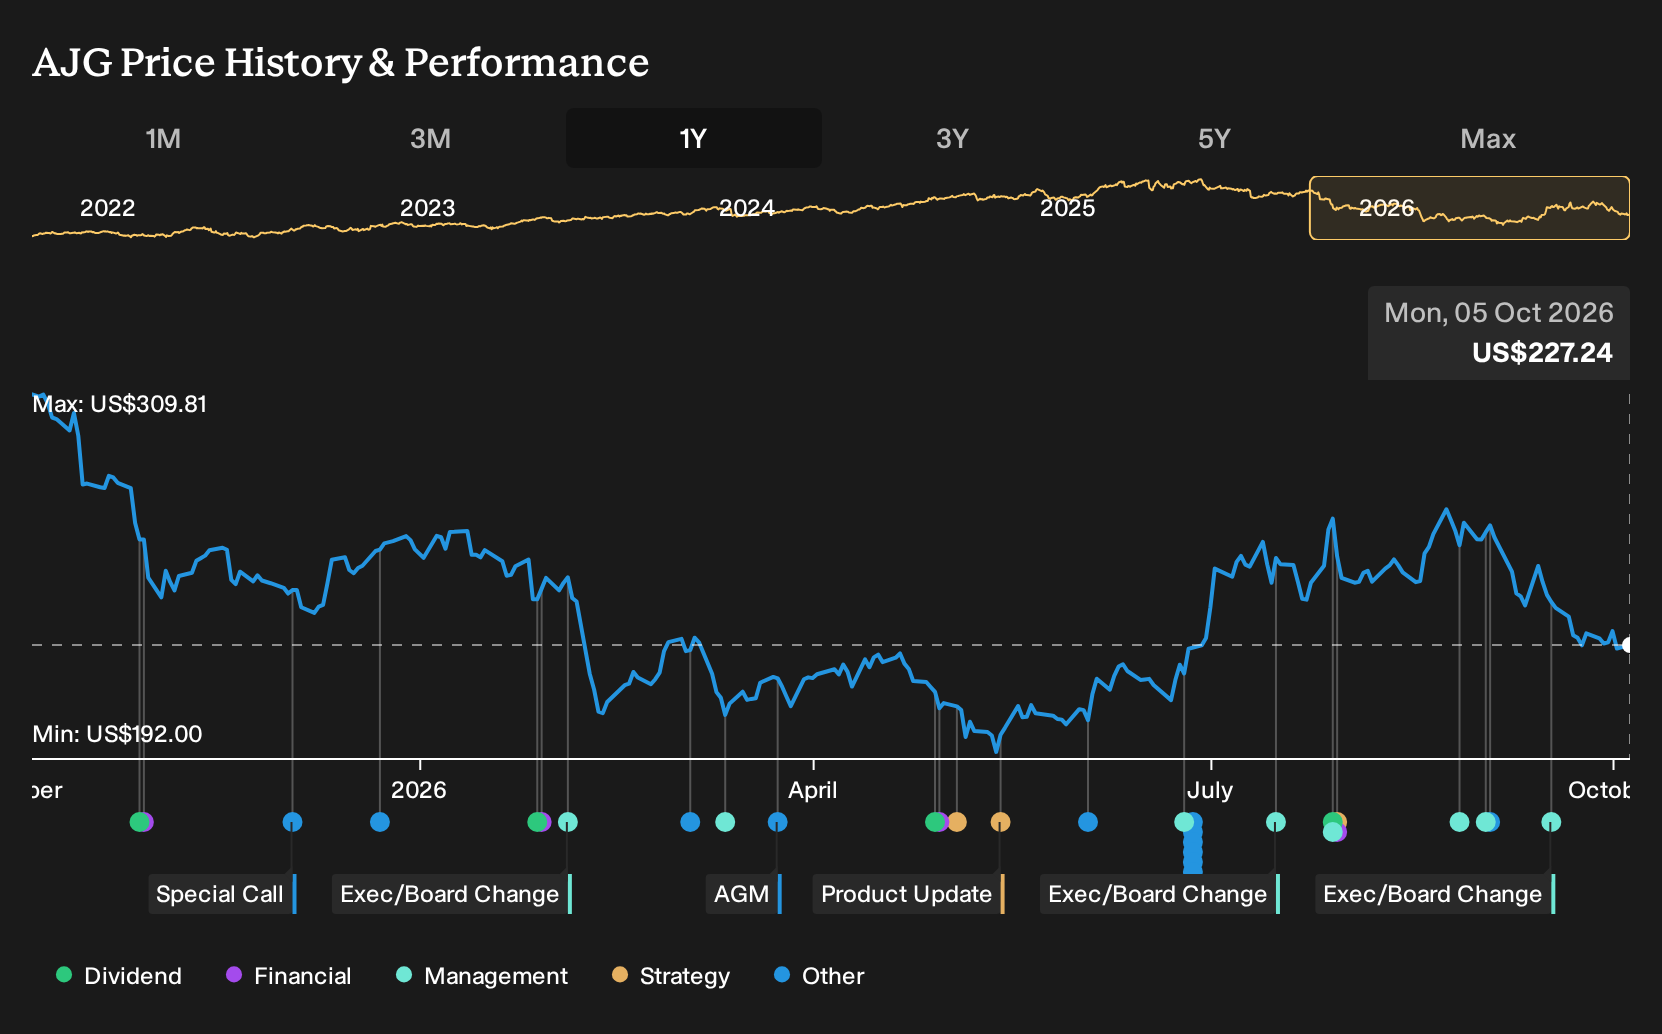
To own Arthur J. Gallagher, you need to be comfortable with a broker and risk manager that leans heavily on recurring fee income, M&A and a long term efficiency program. The recent quarter showed strong 24.3% revenue growth and a small earnings beat, so the sharp 11.8% share price drop looked more like a reset in expectations than a change in the operating story.
For the next year, the key swing factor is whether management can keep organic growth steady while integrating deals such as AssuredPartners and pushing AI and automation projects. The main vulnerability still sits in property pricing pressure and the risk that planned cost savings and synergies arrive more slowly than investors expect. If that happens, the impact of this quarter on the broader thesis remains modest.
With no fresh corporate announcements tied directly to this earnings release, the most relevant reference point is still Arthur J. Gallagher’s previously outlined efficiency and M&A plans. Management has talked about using AI, digitization and automation to trim production, support and back office costs over several years, alongside a sizeable acquisition pipeline and the AssuredPartners integration.
Those older commitments frame how to read this quarter. Strong reported growth suggests the underlying franchise continues to add business, while the revenue miss and share price reaction put more pressure on execution of cost programs and deal synergies. For investors, the focus now falls on whether future updates show measurable progress on workflow standardization, AI driven savings and the AssuredPartners synergy targets rather than just headline top line expansion.
Arthur J. Gallagher's current earnings are about US$1.6b, with analysts forecasting earnings of US$3.0b by 2029 and projecting revenue of US$20.5b in that same year. This narrative implies yearly revenue growth of 10.6% and an earnings increase of roughly 87.5% from earnings today to the 2029 consensus level.
Uncover why Arthur J. Gallagher's fair value indicates a 28% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
You can read Arthur J. Gallagher very differently if you lean into the bullish catalyst of aggressive M&A. The most optimistic analysts were pencilling in US$21.8b of revenue and US$3.7b of earnings by 2029, versus the consensus US$20.5b and US$3.0b. That more upbeat script has not yet absorbed this latest earnings surprise or the 11.8% share price drop, so it is best treated as one of several viewpoints to stress test rather than a finished answer.
Explore 3 other Arthur J. Gallagher fair value estimates, including one that suggests potential upside of up to 45% from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Arthur J. Gallagher research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Arthur J. Gallagher. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Arthur J. Gallagher's overall financial health at a glance.
Looking For More Investment Ideas Beyond Arthur J. Gallagher?
If the Arthur J. Gallagher story has sharpened your thinking but you want a broader watchlist, the Simply Wall St Screener can help you build a roster of companies that better match your risk tolerance and income goals.
- If capital preservation is front of mind, start with companies that have steadier profiles using the 31 resilient stocks with low risk scores to spot potential candidates.
- If value is your priority, sift through businesses that pair solid balance sheets with attractive valuations using the 27 high quality undervalued stocks to see what else stacks up.
- If income matters most to you, focus on payout strength and stability by using the 7 dividend fortresses to find higher yielding options that may fit your portfolio.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com