
Energy Transfer (ET) Stock Could Be Undervalued As Earnings Stay In Focus
Energy Transfer has handed shareholders a powerful ride over the past few years, and that kind of track record naturally pushes investors to ask whether the current share price still lines up with what its earnings can support. With the stock last closing at US$20.72, the core issue is whether that tag reflects what the pipeline operator is actually generating in profit today.
- Over the past 5 years, Energy Transfer has delivered a total return of 210.6%, which now puts the focus squarely on whether past gains have already baked its earnings power into the price.
- The partnership relies on long term fee based contracts and heavy infrastructure spending. These can shape both the stability of its earnings stream and the pace at which any retained cash flow adds to future profit.
- The analysts covering Energy Transfer have run their own numbers. See what analysts think Energy Transfer's shares could be worth.
For investors, the debate is whether Energy Transfer's current valuation is justified by the earnings that underpin the stock today.
If you want to stress test this same earnings based valuation question beyond Energy Transfer, line it up against other candidates in the 27 high quality undervalued stocks.
Is Energy Transfer a Bargain on Earnings?
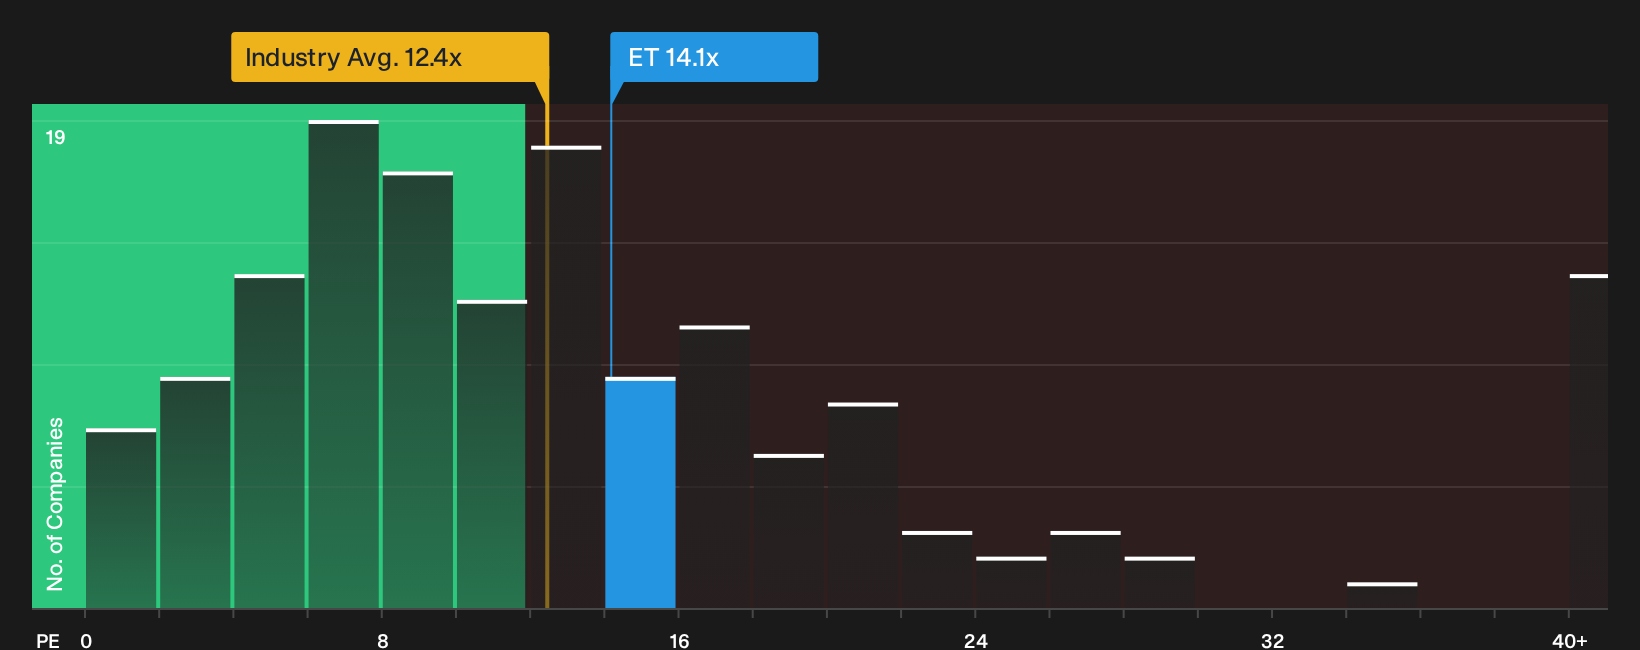
The P/E ratio suits Energy Transfer because earnings remain a key anchor for how investors judge a capital heavy pipeline operator. At roughly 14.1x, Energy Transfer trades below the Oil and Gas industry average of about 12.4x and also below the broader peer group on roughly 18.4x. That puts the stock in an interesting middle ground where it does not screen as the most expensive option in the sector, but also does not sit at the low end of the range either.
The fair value framework suggests a higher P/E would be in line with what Energy Transfer might command given its business profile, which means the current 14.1x points to the units pricing in a discount on this measure. For you as a unitholder or potential buyer, the key question is whether the partnership's earnings quality and risk profile justify that lower tag or whether the gap signals room for a higher earnings multiple if sentiment changes. Explore the numbers behind Energy Transfer's P/E valuation.
The Energy Transfer Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the P/E puzzle on Energy Transfer leaves off by spelling out what kind of future for earnings, growth and profitability would need to play out for the current unit price to look materially higher or lower. Rather than relying on a single multiple or one model output, each scenario lays out the assumptions behind its estimate of value so you can compare those inputs with Energy Transfer's reported results as they come through.
One of the top community narratives on Energy Transfer: 16% undervalued
"Recent long term customer commitments on multi billion dollar projects are now supported by more than 6 Bcf/d of contracted pipeline capacity…"
Discover why this Narrative puts Energy Transfer at 16% undervalued.
One more thing about Energy Transfer that is easy to miss
Everything so far has focused on what Energy Transfer looks like today, but professional analysts have sketched out where they expect profits and cash generation to head over the next few years. This gives you a separate yardstick to compare with the current market view. Explore where analysts expect Energy Transfer to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com