
Somnigroup International (SGI), Why Is The Bedding Giant Drawing Fresh Attention?
Somnigroup International (SGI) drew fresh attention after its recent name change from Tempur Sealy International, a rebranding that puts renewed focus on the bedding group’s Mattress Firm, Tempur-Pedic, Sealy and Stearns & Foster operations.
For investors tracking the price, Somnigroup International’s share price has drifted lower in recent months, with a 30-day share price return down 10.85% and year to date down 29.81%. However, the three year total shareholder return is up 55.64% and the five year total shareholder return is up 46.45%, which suggests longer term holders have still seen gains despite the recent pullback.
Scan beyond Somnigroup International and see how other bedding and consumer brands are priced right now by checking our hand picked 27 high quality undervalued stocks list.
Somnigroup International’s slide over the past year could hint at doubts about its bedding brands or simply a reset in market mood. The valuation work starts with separating those two stories.
Most Popular Narrative: 33% Undervalued
Against the last close of $62.29, the most followed narrative for Somnigroup International places fair value at $93.44, so the debate shifts to whether the underlying drivers justify that gap.
The integration of Mattress Firm is already generating meaningful sales and cost synergies, with $100 million in annual net cost synergies projected and sales synergies ahead of schedule. These operational improvements are set to expand EBITDA and enhance net margins moving into 2026 and beyond.
See why 6 investors see Somnigroup International as 33% undervalued.
Result: Fair Value of $93.44 (UNDERVALUED)
Still, the story can change quickly if consumer demand for big ticket bedding weakens further or if Somnigroup International struggles to capture the planned synergies from Leggett & Platt.
Find out about the key risks to this Somnigroup International narrative.
Another View On Somnigroup International’s Valuation
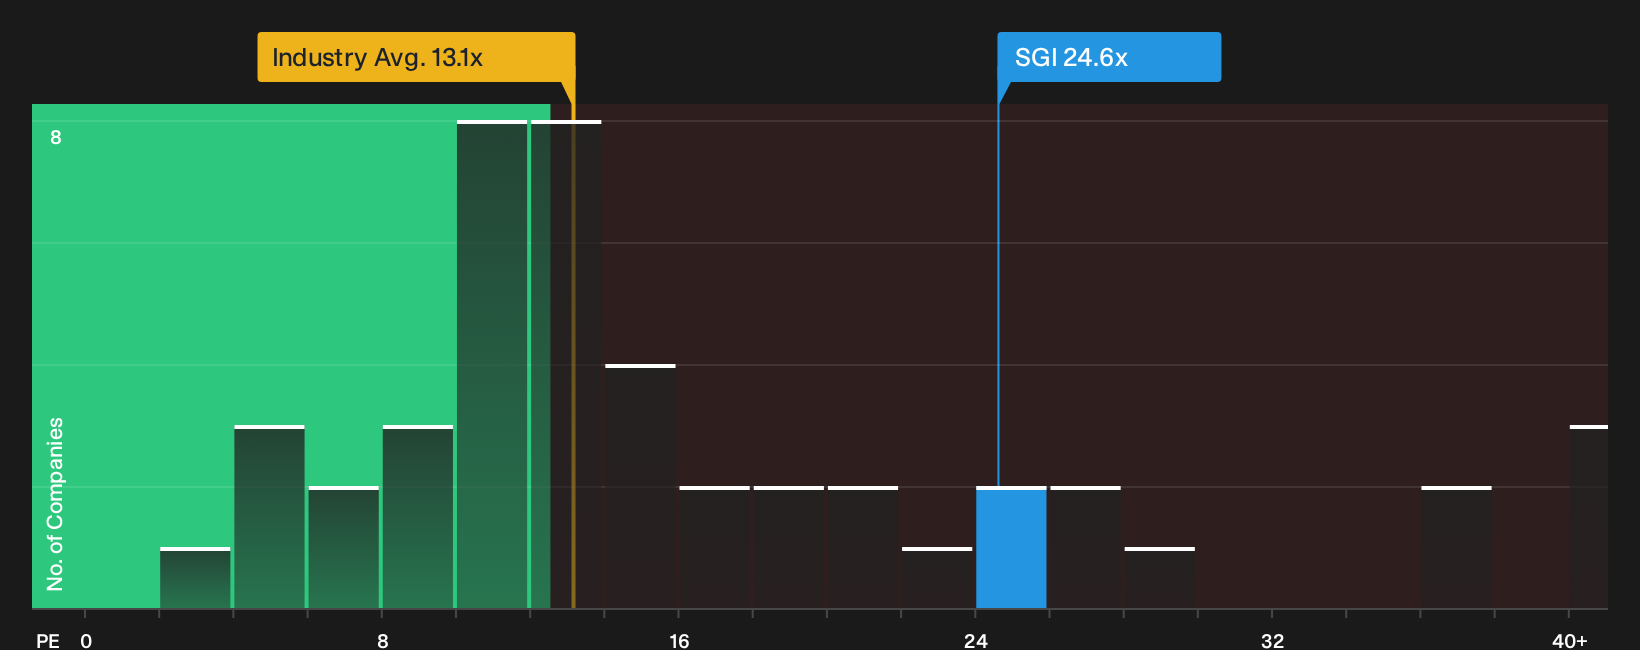
On simple earnings multiples, Somnigroup International looks far less forgiving. The stock trades on a P/E of 24.6x, compared with 13.1x for the wider US Consumer Durables group and 15.7x for closer peers. Yet the fair ratio sits near 25x, which implies the current tag already bakes in a lot of optimism and leaves less room for error if the story wobbles.
That mix of a premium P/E against sector and peer averages, but a P/E that is close to the fair ratio, raises a harder question. Is this a quality premium that can hold, or is it valuation risk in disguise for anyone buying Somnigroup International on today’s earnings base?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals rarely simplify a decision, and Somnigroup International is no exception. Move quickly from headline impressions to the underlying detail that matters most to you and see the full balance of 4 key rewards and 1 important warning sign.
Looking for more Somnigroup International investment ideas?
If Somnigroup International has sharpened your focus on pricing power and resilience, do not leave potential opportunities on the table. Put that curiosity to work across the wider market using targeted screeners that surface clear, numbers driven ideas aligned with your approach.
- Target consistency by reviewing companies built around strong balance sheets and fundamentals through our list of solid balance sheet and fundamentals (25 results).
- Spot potential value gaps by scanning our hand picked collection of 27 high quality undervalued stocks that pair quality fundamentals with appealing pricing.
- Unearth fresh prospects before the crowd by checking a focused group of 19 high quality undiscovered gems that already show solid underlying strength.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com