
Insmed (INSM) Reaffirms Outlook As Its Undervalued Narrative Faces A Fresh Test
What triggered fresh attention on Insmed stock
Insmed (INSM) just paired a planned CFO transition with a reaffirmed 2026 revenue outlook for BRINSUPRI and ARIKAYCE, giving investors a fresh information point on both leadership continuity and projected product sales.
The CFO transition and reaffirmed guidance follow a sharp pullback in Insmed’s share price, which is down 17.8% over 30 days and 41.4% year to date, even though the 3-year total shareholder return is more than triple its level three years ago.
Capitalize on the volatility around Insmed by scanning a hand picked set of 19 high quality undiscovered gems that also focus on rare disease and early stage therapies.After a 41.4% year to date slide and a reaffirmed revenue outlook for its key therapies, Insmed now sits at a crossroads. Is most of the upside still ahead, or did it already arrive earlier in the story?
Most Popular Narrative: 47% Undervalued
Against a last close of $103.83, the most followed Insmed narrative pegs fair value near $197, which frames a wide valuation gap that investors now weigh against execution risk around its respiratory portfolio.
The anticipated U.S. launch of brensocatib in bronchiectasis in the third quarter of 2025 is a major catalyst, expected to significantly increase revenue once it hits the market and starts generating sales late in Q3. The upcoming Phase II data for TPIP in PAH by mid-2025 and brensocatib in CRS without nasal polyps by the end of 2025 are key clinical milestones that could enhance future revenue streams if positive.
See why 21 investors see Insmed as 47% undervalued.
Result: Fair Value of $197.14 (UNDERVALUED)
Still, if FDA timelines slip or payer pushback limits brensocatib access, Insmed’s current upside narrative could unravel faster than many models assume.
Find out about the key risks to this Insmed narrative.
Another Look At Insmed’s Valuation
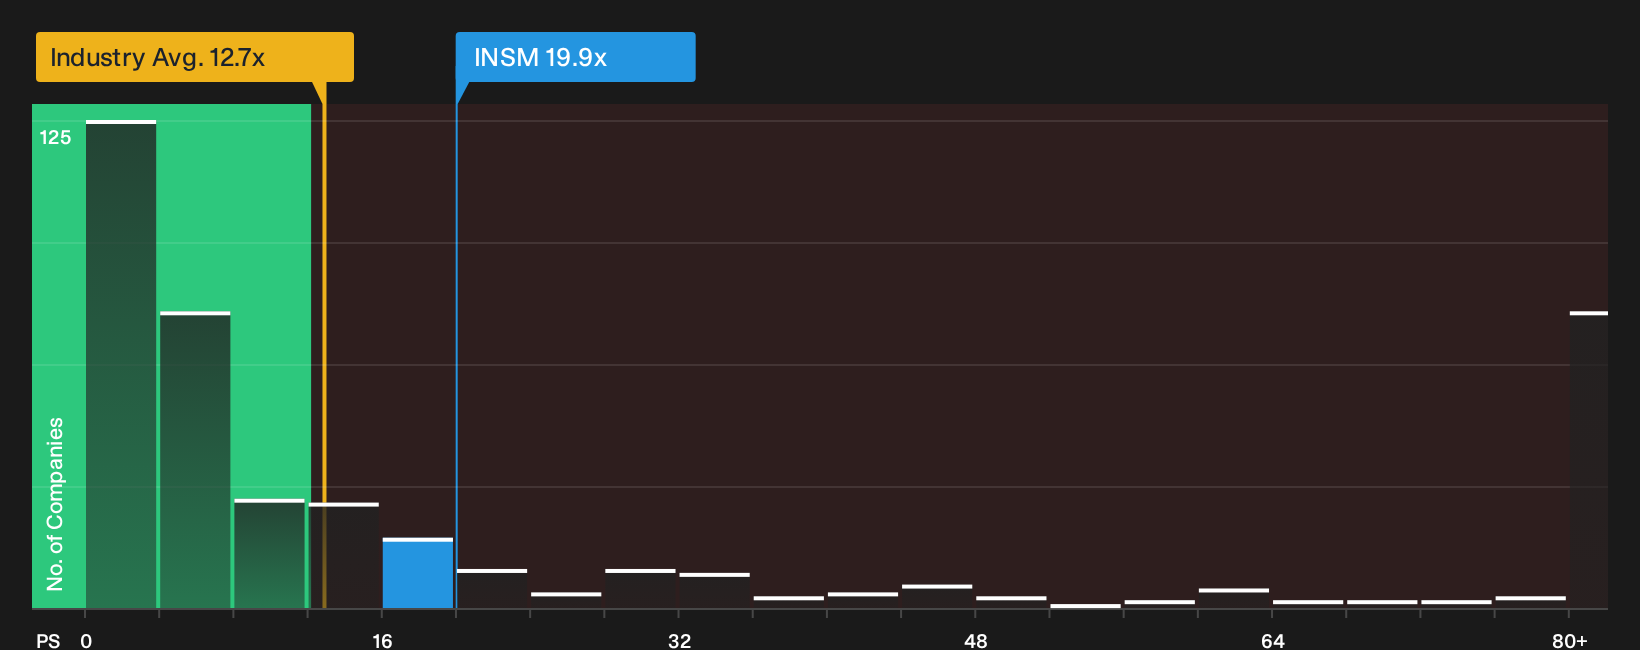
The first fair value story paints Insmed as heavily undervalued, but the price tag investors actually pay in the market tells a different story. The stock trades on a P/S of 19.9x, compared with 12.7x for the wider US biotech group and 7.4x for closer peers.
Even against a fair ratio of 17.4x, Insmed sits on a richer multiple, which suggests less room for error if revenue or margins fall short of expectations. With that kind of gap, is the crowd leaning too hard into the upside scenario, or are multiples still catching up to the narrative?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages around Insmed can pull you in either direction, so move quickly, review both the concerns and the potential upside, then weigh the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Insmed?
If Insmed has your attention, do not stop there. Broader context across sectors can help you judge whether today’s opportunity really stacks up.
Use the Simply Wall Street screener to spot other stocks right now, so you are not relying on a single Insmed outcome to shape your portfolio.
- Target resilient potential by zeroing in on companies with sturdy finances and proven fundamentals through a curated list of solid balance sheet and fundamentals (25 results).
- Chase value opportunities by surveying a focused 27 high quality undervalued stocks that bring strong business quality together with appealing pricing.
- Prioritize stability and sleep better at night by scanning a hand picked 31 resilient stocks with low risk scores that aim to keep drawdowns in check.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com