
Veracyte (VCYT) Could Be 16% Undervalued After New Decipher ASTRO Data
Veracyte (VCYT) is back in focus after new data on its Decipher Prostate Genomic Classifier were presented at the ASTRO 2026 meeting, which linked test scores to androgen deprivation therapy benefit.
Veracyte’s latest Decipher data landed against a backdrop of a US$47.67 share price and noticeable swings in recent months, with a 1 month share price return of 12.09% after a 90 day share price decline of 15.06% that tempers the near term momentum.
New presentations at ASTRO and fresh Level 1B1 evidence around Decipher arrive while the 1 year total shareholder return of 37.73% and 3 year total shareholder return of about 2x suggest that investors who remained invested through past volatility have experienced materially stronger outcomes than short term traders focused only on recent price moves.
Elevate your research on Veracyte by scanning a curated group of oncology and biotech peers with resilient balance sheets using our list of solid balance sheet and fundamentals (25 results).Veracyte now combines fresh Decipher evidence with a US$47.67 share price and a sharp 30 day rebound. The key question is whether that clinical traction is already fully reflected in the valuation.
Most Popular Narrative: 16% Undervalued
Veracyte's most followed narrative points to a fair value of $56.55 against the recent $47.67 close, framing the current share price as meaningfully below that estimate while tying the story directly to its cancer diagnostics portfolio and cash generation profile.
Broad and accelerating adoption of advanced genomic and noninvasive cancer diagnostics, combined with growing cancer incidence and aging populations, are steadily expanding the potential patient pool. This directly supports sustained double-digit volume and revenue growth across Veracyte's core product lines (notably Decipher and Afirma). Pipeline momentum with five major product launches and a pivotal clinical study (OPTIMA) completing in the next 18 months positions Veracyte to further diversify revenue, drive cross-selling, penetrate new markets (e.g., MRD in bladder cancer, Prosigna for breast cancer), and significantly expand addressable markets, supporting long-term topline acceleration.
See why 13 investors see Veracyte as 16% undervalued.
The narrative applies a 7.16% discount rate to those long-term cash flows and arrives at a fair value that is about 16% above the last close. This puts a lot of weight on continued execution in Afirma, Decipher and the broader pipeline while also acknowledging reimbursement and regulatory risks flagged by analysts.
Result: Fair Value of $56.55 (UNDERVALUED)
Still, Veracyte’s heavy reliance on Afirma and Decipher, along with ongoing reimbursement and pricing pressure, could quickly challenge the view that the shares are currently undervalued.
Find out about the key risks to this Veracyte narrative.
Another View on Veracyte’s Valuation
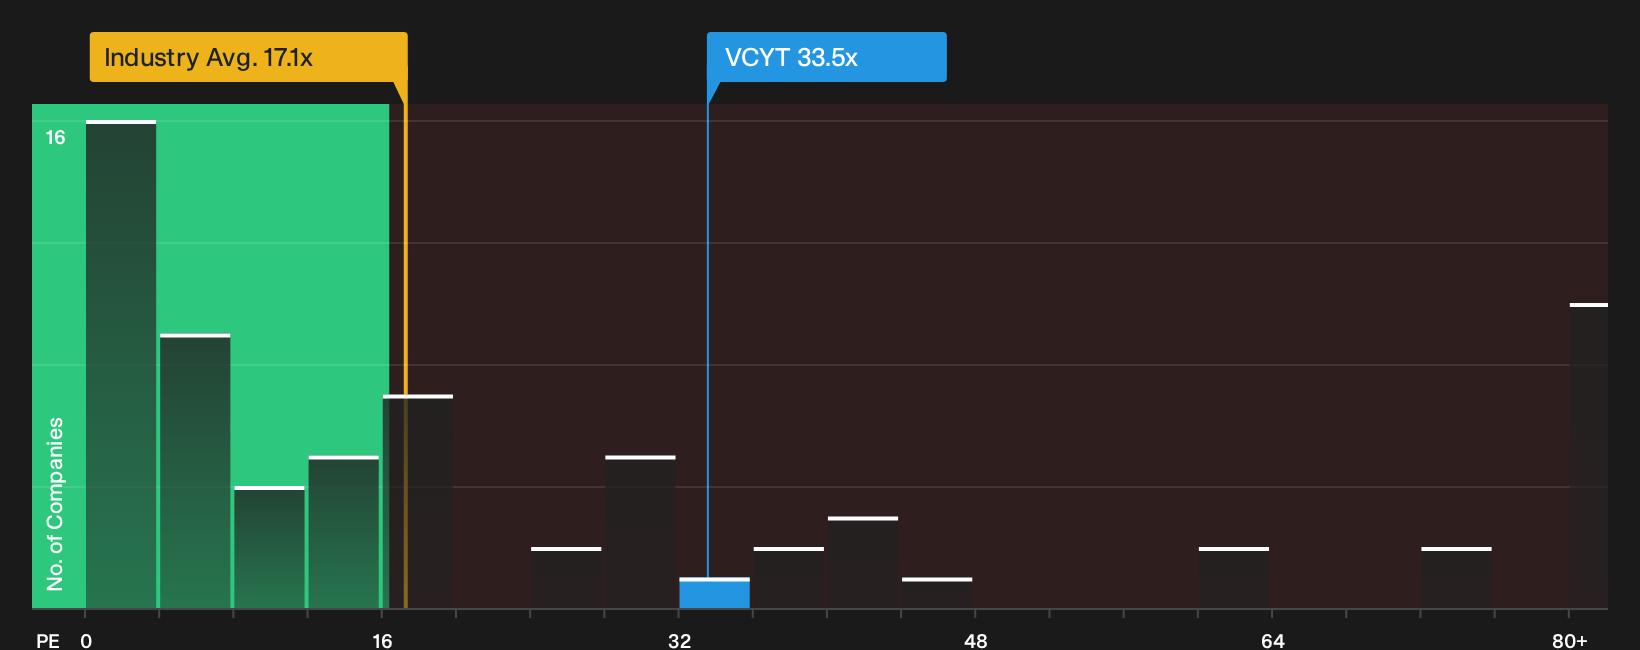
On a simple earnings multiple, Veracyte looks far less forgiving than the SWS DCF model suggests. The stock trades on a P/E of 33.5x, which is almost double the US Biotechs average of 17.2x and above the fair ratio of 17.8x that the market could gravitate toward over time.
That kind of gap can either reflect genuine confidence in Veracyte’s pipeline and cash generation, or leave holders exposed if sentiment cools and the multiple compresses. Which side of that trade-off do you think fits your own risk tolerance and time horizon?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages in the data so far? Act while the information is fresh, review both sides of the story, then weigh the 4 key rewards and 1 important warning sign.
Looking for more Veracyte style investment ideas?
If you stop with Veracyte, you might miss other opportunities. Cast a wider net now and let quality filters do the heavy lifting for you.
- Target resilient balance sheets and steady fundamentals by scanning our list of solid balance sheet and fundamentals (25 results).
- Hunt for strong businesses trading below their estimated worth with the 27 high quality undervalued stocks.
- Focus on stability and income potential by reviewing our 7 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com