
Why On Semiconductor Is Betting Big on AI Power and What Its $5.7 Billion Bet Means for ON Stock
Earlier this year, On Semiconductor (ON) agreed to buy Synaptics (SYNA), a company known for human interface and sensing chips. Soon after, an unexpected third party provided a competing offer.
When the dust settled, the deal took a different shape. Onsemi's CEO insists it changed in his shareholders' favor.
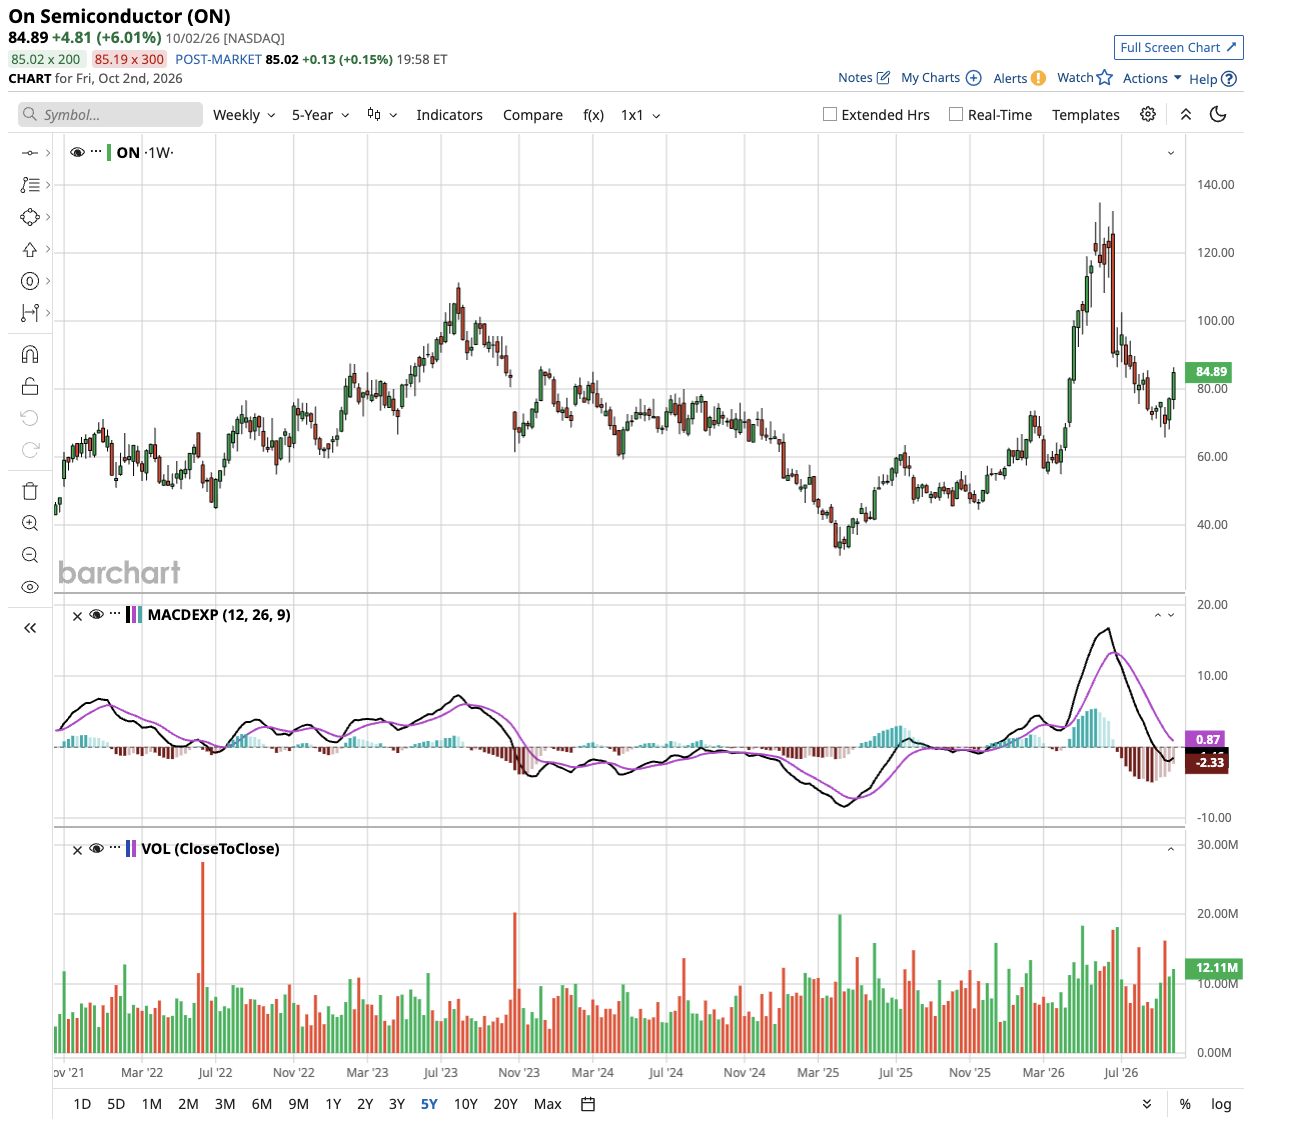
Why ON Stock is Betting Big on AI Power
To understand why Onsemi wants to acquire Synaptics, you have to go back to the company's investor day on Sept. 16. CEO Hassane El-Khoury opened with a big claim. "It is the era of AI," he told analysts. He explained that AI is running into physical limits on compute, memory, and power. Onsemi wants to own the power piece. "We solve power," he said.
Achyut Shah, president of Onsemi's Power Solutions Group, said the AI data center business will more than double in 2026. He expects it to grow from about $500 million this year to more than $2.5 billion by 2030.
Chief Financial Officer Thad Trent laid out the bigger picture:
- Revenue growth: 12% to 14% a year through 2030, reaching just under $11 billion.
- Gross margin target: 53%, which Trent called "a milestone," not "a destination."
- Free cash flow: More than $3.5 billion by 2030, more than double current levels.
Those projections leave Synaptics out entirely. Trent said Onsemi expects Synaptics to grow more than 15% a year with gross margins above 55%.
Valued at a market cap of $33 billion, ON stock is down 37% from all-time highs. Is the ongoing pullback an opportunity to buy a growth stock at a discount?
New Synaptics Deal Reshapes ON Stock Story
Under the revised agreement, Onsemi will pay $123 per share in cash for Synaptics, according to a joint company statement. That puts the total value at about $5.7 billion, down from roughly $7 billion under the original deal.
The rewrite followed an "unsolicited competing proposal" from a third party, which the companies did not name. The bigger change is how Synaptics shareholders get paid. At the investor day, Gary Mobley of StoneX described the original deal as an "all equity acquisition." Now it is all cash.
In a stock deal, sellers receive shares of the buyer. The value of that payment rises and falls with the buyer's stock price until the deal closes. "We believe the revised merger agreement represents a more financially attractive transaction for our shareholders," El-Khoury said in the statement.
Onsemi expects the deal to add to its adjusted earnings per share immediately after closing. Synaptics' board approved the new terms unanimously after reviewing them with its financial and legal advisers.
"Our Board has been singularly focused on delivering the best outcome for our shareholders, and today's amended agreement reflects that commitment," said Synaptics CEO Rahul Patel. He added that the cash structure offers "value certainty at a meaningful premium as compared to current value."
How Onsemi Plans to Pay for Synaptics
Onsemi will pay for the purchase with cash on hand plus borrowed money. Morgan Stanley (MS) has provided fully committed debt financing. The amended agreement has no closing condition tied to Onsemi's financing, so the deal cannot fall apart if Onsemi fails to line up the money.
The timeline has not changed. Both companies still expect to close by mid-2027. The U.S. Federal Trade Commission has already approved the deal. Regulators in other countries are still reviewing it, and Synaptics shareholders must vote.
What the Deal Means for ON Stock Price
Onsemi had already promised $200 million in annual run-rate synergies within the first 18 months after closing.
Now management sees more upside. According to the statement, Onsemi expects extra gains from revenue synergies and from moving part of Synaptics' production into its own factories. Those benefits should show up after that first 18-month stretch.
Trent hinted at this in September. "We believe over the long term, there's actually more synergies here on the manufacturing side," he said.
The CEO also sees Synaptics as a steady source of cash. He said its businesses "generate strong and predictable cash flows," giving the combined company "a durable funding engine to accelerate its connected compute capabilities."
Shareholders should keep one tradeoff in mind. At the investor day, Trent said Onsemi plans to return 100% of free cash flow to shareholders after investing in the business. The company bought back $4.2 billion of stock between 2023 and 2026 and still has $5.3 billion left on its buyback authorization.
As the deal is paid in cash and partly with debt, some of the capital will now be allocated to fund the acquisition. Still, management believes paying less, in cash, for a faster-growing business is worth it.
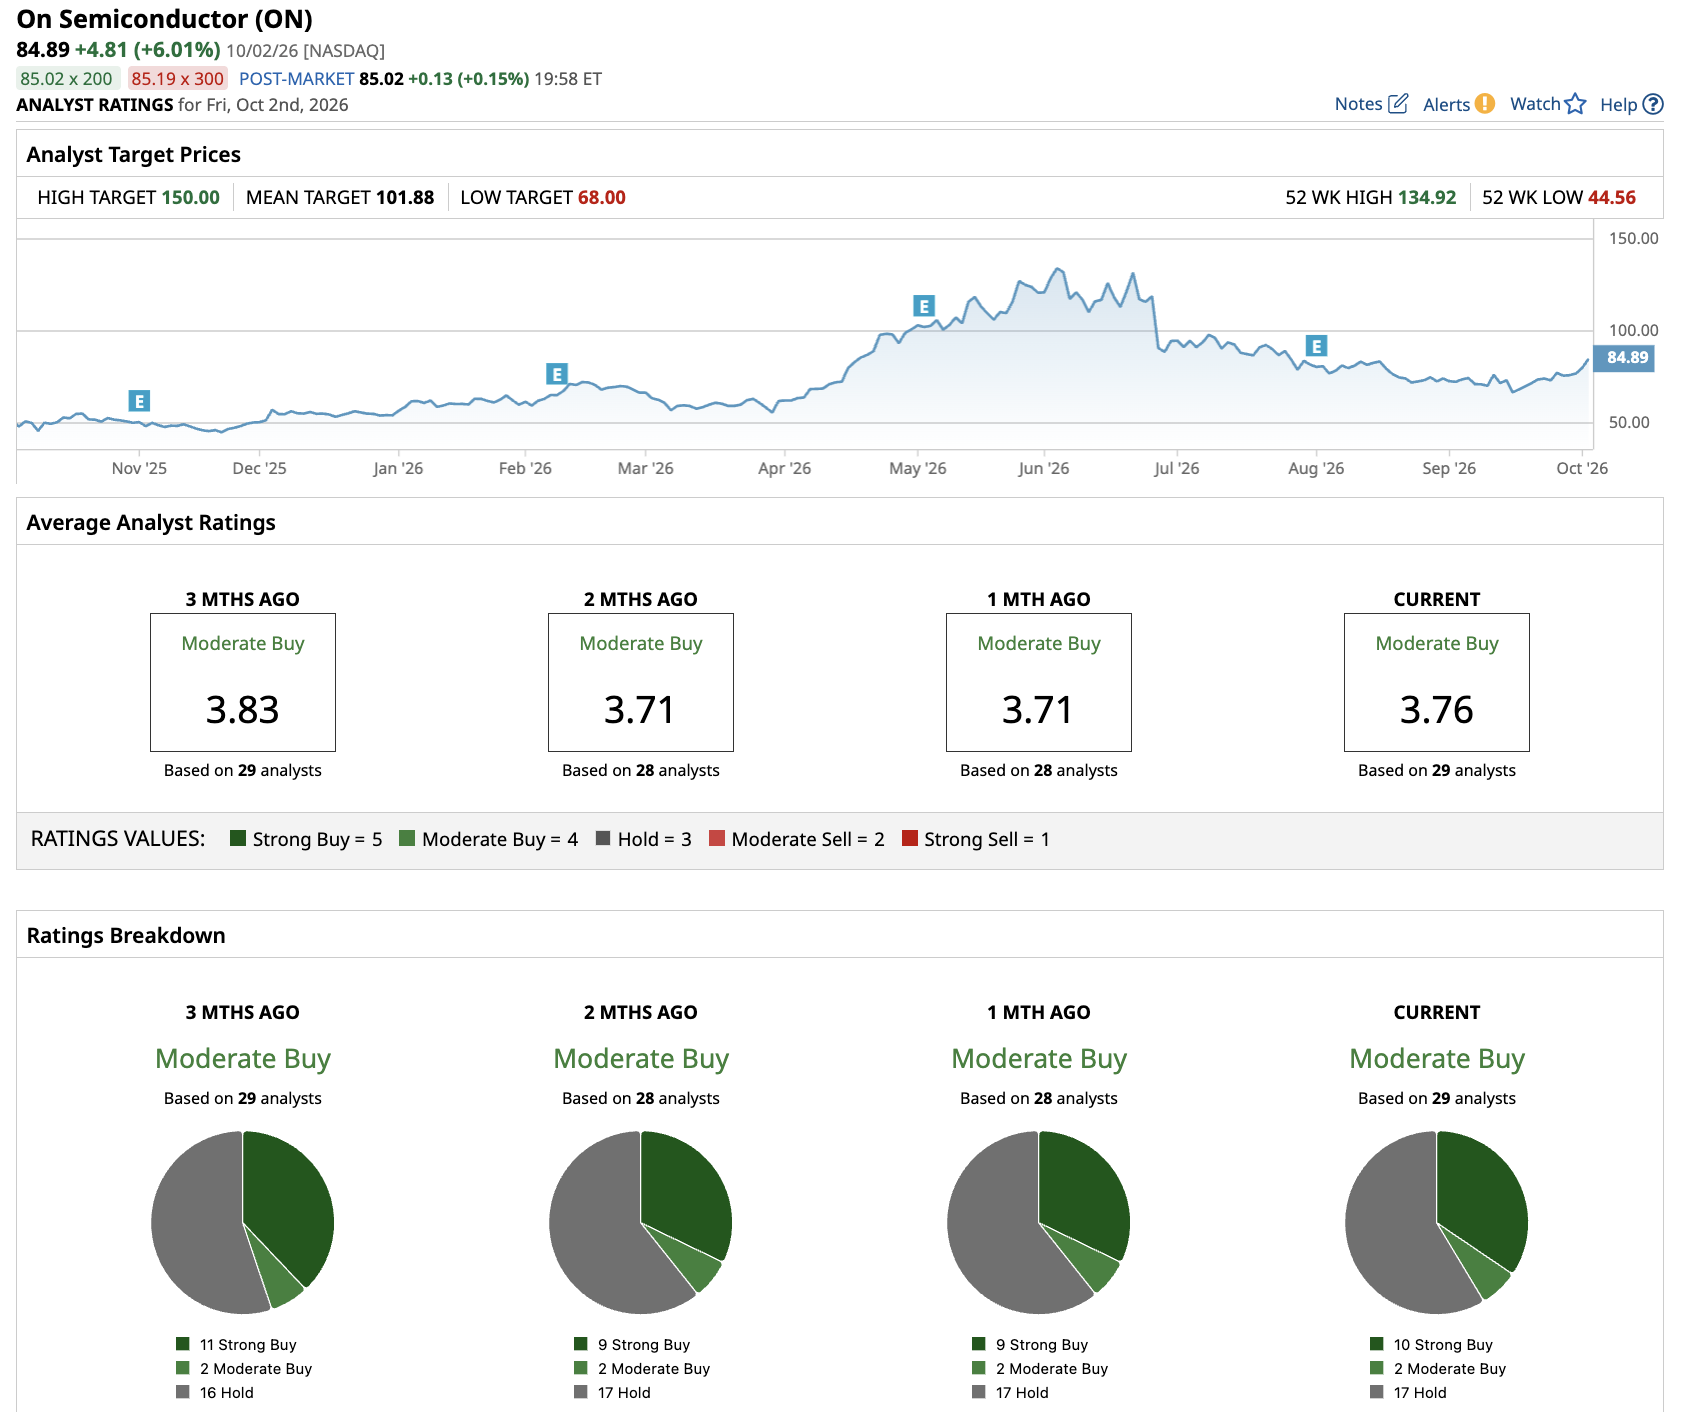
Out of 29 analysts covering ON stock, 10 recommend “Strong Buy”, two recommend “Moderate Buy”, and 17 recommend “Hold”. The average ON stock price target is $102, above the current price of $85.
On the date of publication, Aditya Raghunath did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.