
Did Earnings Beat Just Shift Americold Realty Trust's (COLD) Investment Narrative?
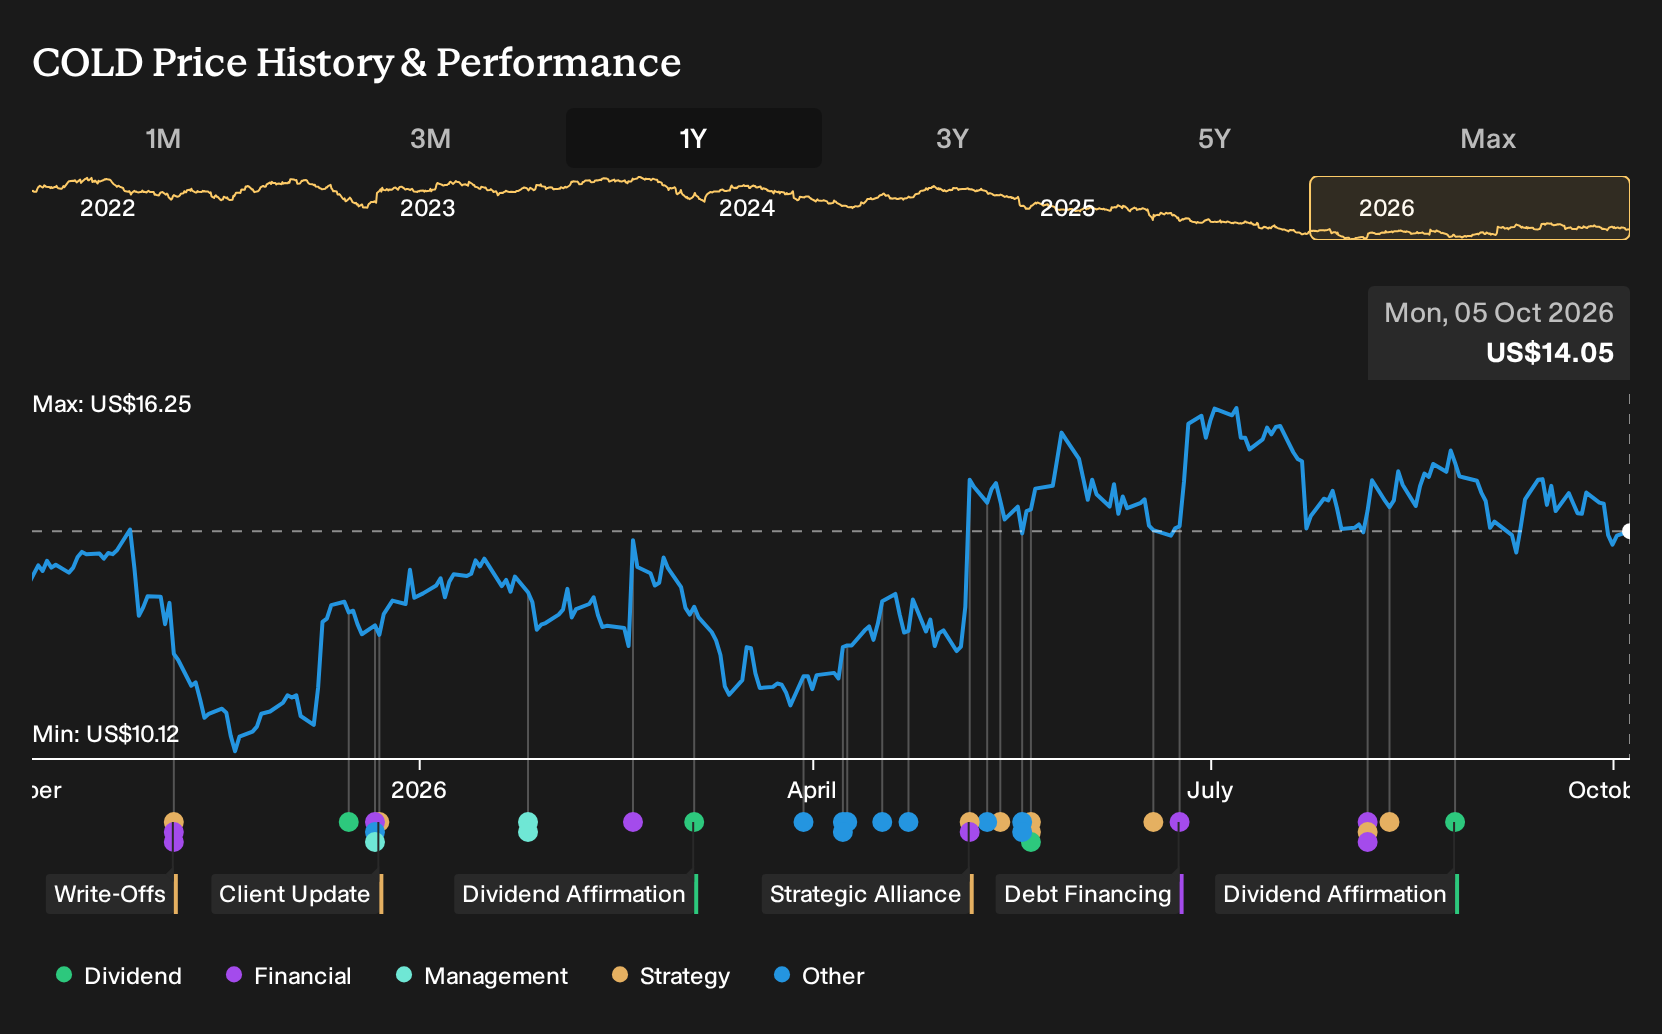
- Americold Realty Trust reported Q2 2026 AFFO per share of $0.35, ahead of expectations, and entered a $1.3b joint venture with EQT while continuing to exit weaker facilities.
- Management raised full-year AFFO guidance despite expected dilution from the new venture, which signals confidence in occupancy levels, pricing, and recent market share gains.
- This article will examine how Americold Realty Trust's raised AFFO guidance reshapes the investment narrative built around cold-storage demand and leverage.
Compare Americold Realty Trust's balance sheet moves with a curated group of companies using a list of solid balance sheet and fundamentals (25 results) as a starting universe for further ideas.
Americold Realty Trust Investment Narrative Recap
An investor in Americold Realty Trust needs to believe cold storage remains essential infrastructure and that a scaled network can translate steady occupancy and pricing into improving cash generation over time. The raised AFFO guidance after Q2 suggests current operations are holding up, with market share wins and contract structures supporting near term stability.
The biggest short term swing factor remains occupancy and customer inventory behavior. Any renewed softness in volumes or pricing could pressure AFFO despite recent progress. The key risk still sits on the balance sheet. Elevated leverage and external borrowing leave little room for operational missteps if demand weakens again.
The new $1.3 billion joint venture with EQT is the announcement that most directly links to this quarter’s story. Americold Realty Trust aims to use the structure to lighten the balance sheet while keeping operational control of key logistics assets, which is important given the business is still working through prior heavy investment.
This joint venture also ties directly into the current catalysts. Capital recycling and exiting weaker facilities concentrate resources into higher quality properties that rely on multiyear fixed commit contracts and value added services. Execution risk remains. Integrating partners, meeting service levels, and hitting AFFO targets now need to progress in parallel.
Americold Realty Trust's current analyst narrative points to US$2.8b in revenue and US$1.0b in earnings by 2029, based on revenue rising at 2.5% per year and earnings moving from a loss of US$111.7m today to that level over the same period.
Uncover why Americold Realty Trust's fair value indicates a 16% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
The most optimistic analysts focus on Americold Realty Trust’s potential margin lift from automation rather than the balance sheet. Before this Q2 update, the bullish group was pencilling in revenue of about US$3.0b and earnings of US$32.8m by 2029. That is a very different story from consensus, and both views may shift as this new joint venture is digested.
Explore 3 other Americold Realty Trust fair value estimates, including one that suggests potential upside of up to 49% from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Americold Realty Trust research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Americold Realty Trust. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Americold Realty Trust's overall financial health at a glance.
Looking for more Americold Realty Trust sized ideas?
If the Americold Realty Trust story has sharpened how you think about balance sheets, cash generation, and long term contracts, use that same lens on a broader set of companies with the Simply Wall St Screener.
- If capital preservation comes first for you, start with a group of steadier businesses screened as 31 resilient stocks with low risk scores, which may suit a more defensive style.
- If value is your priority, use a universe of 27 high quality undervalued stocks as a way to surface companies where current pricing sits below fundamental estimates.
- If you want to spot earlier stage opportunities with room to mature, scan through 9 elite penny stocks with strong financials that still meet basic quality and financial filters.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com