
Is Coinbase Global (COIN) Undervalued As Governance Questions Meet Its Crypto Growth Story?
Coinbase Global (COIN) disclosed that Chief Accounting Officer Jennifer Jones plans to retire, and she will remain in her role until a successor is appointed. Investors now have fresh governance and continuity questions to consider.
Recent moves around Coinbase Global help explain how investors are weighing that transition risk. The share price has climbed 18.11% over the past 90 days, even though the year-to-date share price return is down 20.42% and the 1-year total shareholder return has declined 49.91%. At the same time, regulatory progress on derivatives clearing and the expanded Citi partnership point to shifting expectations around growth potential and operational risk.
Scan other crypto and blockchain plays reacting to the same regulatory and infrastructure themes as Coinbase Global through a curated set of 18 cryptocurrency and blockchain stocks.
Bulls see Coinbase Global’s derivatives approval and Citi deal as proof the business is earning a higher multiple, while bears focus on losses and governance risk. Which story do the current valuation markers actually support next?
Most Popular Narrative: 24% Undervalued
Against Coinbase Global’s last close of $188.22, the most followed valuation story points to a fair value of about $247.39, framing today’s price as a discount rather than a premium.
I think Coinbase is best understood as a leveraged bet on long-term crypto adoption, rather than a normal operating business with smooth, predictable growth.
What matters most is not whether next year looks clean, but whether crypto becomes a meaningfully larger asset class over time. If that happens, Coinbase should benefit through higher trading activity, higher asset values on the platform, and growth in its custody and subscription businesses.
See why 24 investors see Coinbase Global as 24% undervalued.
According to QuanD, this thesis leans heavily on crypto adoption over a multi year window, which shapes both revenue potential and margin assumptions. The narrative uses a discount rate of 8.07% and assumes Coinbase Global can reach materially higher earnings power as the crypto asset class matures.
Net income is currently in loss territory at $987.77m, yet the same storyline expects the business to move into profit over the next three years. Earnings are forecast to grow 67.04% each year, while revenue growth is expected at 11.8% per year, which is slower than the 13.8% forecast for the broader US market.
That gap between the growth forecast and the higher implied fair value hinges on margin expansion and operating leverage in areas like custody, derivatives and subscriptions. Management is also working with a relatively new executive bench, with an average management tenure of 0.3 years. In contrast, the board itself is experienced and mostly independent.
Investors weighing this 24% undervalued narrative against the recent 1 year share price decline of 49.91% need to decide how much conviction they have in crypto volumes, pricing cycles and Coinbase Global’s ability to convert that activity into durable profitability.
Result: Fair Value of $247.39 (UNDERVALUED)
Still, the Coinbase Global story can break if crypto trading activity stays muted for years or if regulators tighten rules on key products.
Find out about the key risks to this Coinbase Global narrative.
Another View: Coinbase Global Through Its Sales Multiple
The fair value story that pegs Coinbase Global at $247.39 leans on long term crypto adoption. A different lens looks only at what investors currently pay for each dollar of sales. On that score, the picture turns less generous and raises fresh questions for anyone leaning on the 24% undervalued thesis.
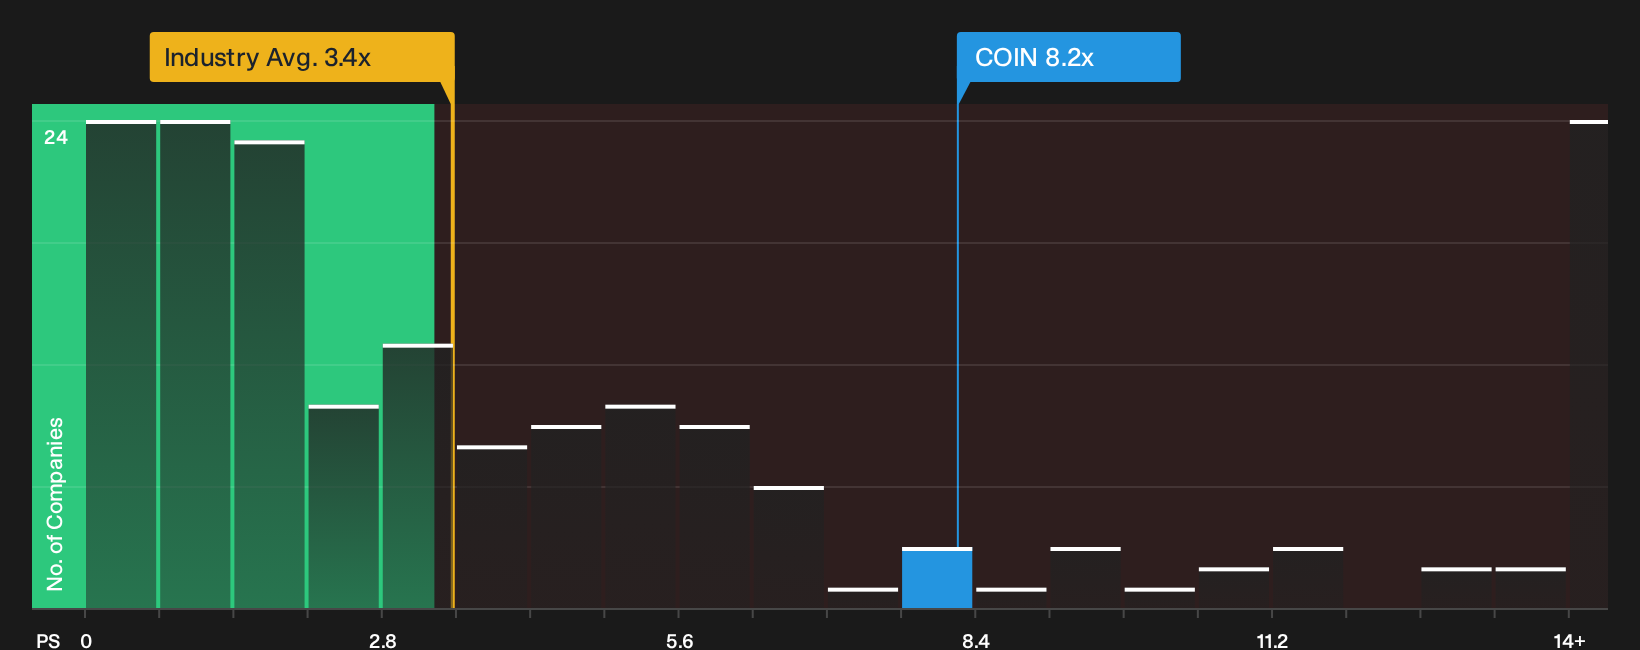
Coinbase Global trades on a P/S ratio of 8.2x. The broader US Capital Markets group sits closer to 3.4x, while the fair ratio is estimated at 4.1x and peers average an even richer 10.2x. That gap suggests valuation risk if sentiment moves toward the fair ratio, but some relative support if the peer premium holds. Which reference point do you consider more relevant when pricing this stock?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment on Coinbase Global is clearly divided, so use that tension as a signal to move fast. Interrogate the numbers yourself and pressure test both sides of the argument using the 1 key reward and 1 important warning sign.
Looking for more investment ideas beyond Coinbase Global?
Do not stop at Coinbase Global alone. Broaden your watchlist with fresh ideas that match your goals so you are not relying on a single story.
- Target potential mispricing by reviewing a curated set of companies that screen as quality opportunities through the 27 high quality undervalued stocks.
- Strengthen portfolio resilience by focusing on businesses with healthier finances using the list of solid balance sheet and fundamentals (25 results).
- Spot early stage opportunities with strong fundamentals before the crowd pays attention by scanning the 19 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com