
IPG Photonics (IPGP) Showcases CROSSBOW At Land Forces 2026, Is The Stock Still Cheap?
IPG Photonics (IPGP) is putting its defense hardware in front of military buyers this week, using the Land Forces 2026 show in Perth to highlight its CROSSBOW high energy laser systems.
These CROSSBOW updates land at a time when IPG Photonics shares are trading at about $83.60, with a 7-day share price return of 8.25% and a 30-day gain of 7.18% that contrasts with a 1-year total shareholder return that has declined 5.2% and a 5-year total shareholder return that has fallen 47.09%. This suggests recent momentum is improving after a tougher multi year stretch.
Scan other defense and industrial tech plays showing fresh momentum with our curated list of 89 robotics and automation stocks alongside IPG Photonics' CROSSBOW rollout.
For IPG Photonics, a short burst of gains sits against years of weaker shareholder returns and improving recent earnings. Is this latest swing about a sturdier business, or sentiment finally snapping back toward optimism on the stock’s valuation?
Most Popular Narrative: 33% Undervalued
At a last close of $83.60 against a widely followed fair value estimate of about $124.14, IPG Photonics is framed as materially undervalued, and that gap is being linked directly to how earnings and margins might evolve over the next few years.
New growth initiatives in medical (e.g., thulium lasers for urology), semiconductor, and micromachining end-markets are gaining early traction, diversifying revenue streams and supporting higher margins over time as these higher-value verticals scale. Recent product innovations like the CROSSBOW directed energy system, validated with multiple unit deliveries and key partnerships (e.g., Lockheed Martin), open up opportunities in defense and critical infrastructure, supporting both revenue acceleration and improved operating leverage.
See why 4 investors see IPG Photonics as 33% undervalued.
Result: Fair Value of $124.14 (UNDERVALUED)
Still, geopolitical friction around tariffs and softer materials processing demand could easily blunt the bullish IPG Photonics narrative if those pressures persist.
Find out about the key risks to this IPG Photonics narrative.
Another View: What IPG Photonics’ P/E Is Signaling
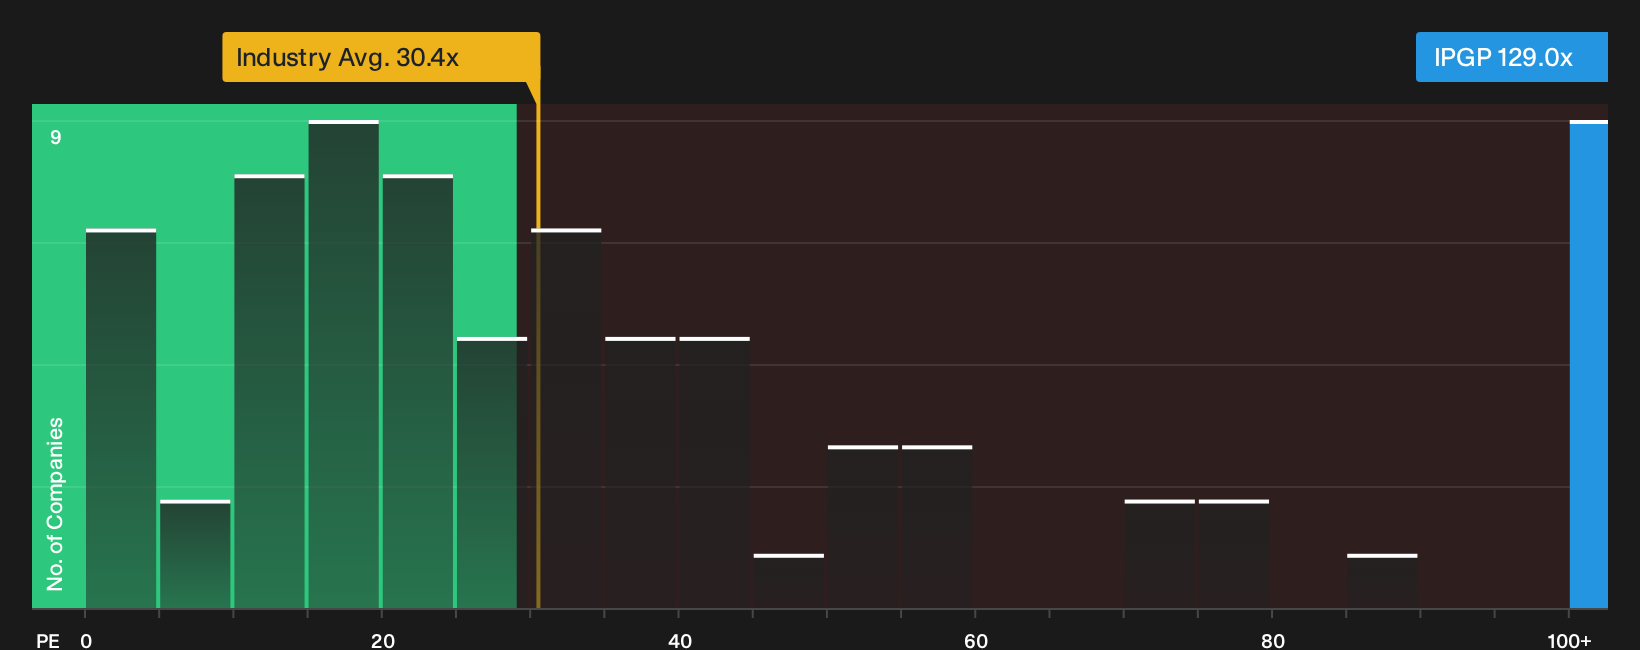
IPG Photonics might screen as undervalued against a $124.14 fair value, yet the current P/E of about 129x tells a very different story. That multiple is far above the US Electronic industry at 30.3x, the peer average at 36.7x, and even the 66x fair ratio the market could move toward, which would mean meaningful valuation risk if sentiment cools.
For a closer look at what that kind of gap can mean in practice, including how much optimism may already be embedded in the current tag, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around IPG Photonics can feel confusing, so move quickly and look at the full picture yourself by weighing 2 key rewards and 1 important warning sign.
Looking for more IPG Photonics sized ideas?
If you stop with IPG Photonics, you risk missing fresh opportunities where quality, value, and resilience line up more cleanly for your portfolio decisions.
- Target potential upside by hunting for quality companies trading below their estimated worth through the 27 high quality undervalued stocks.
- Support an income focus by scanning for payers with higher yields using the 7 dividend fortresses.
- Prioritize resilience by zeroing in on financially sturdy businesses with the list of solid balance sheet and fundamentals (25 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com