
Alphabet (GOOGL) Faces Gemini Lawsuits, Is Fair Value Closer To $203 Or $485?
Alphabet (GOOGL) is now facing multiple securities class actions that focus on alleged misstatements around its Gemini 3.5 Pro AI model, including claims of disappointing training results and delays to the product’s launch.
Recent headlines around Gemini 3.5 Pro and these class actions arrive after a mixed stretch for Alphabet’s stock. The company has posted a 9.94% year to date share price return but a 4.27% decline over the past 90 days, while the 1 year total shareholder return of 41.35% and 3 year figure of 153.34% point to stronger momentum over longer periods.
Spot opportunities that are not tied to Alphabet's legal overhang by scanning a curated set of AI focused stocks through our 38 AI small caps.Alphabet’s share price has cooled over the past three months even as its multi year return stays strong, and the Gemini lawsuits now hang over the story. Does that set up a reasonable entry today, or a case for patience while the valuation resets?
Most Popular Narrative: 71% Overvalued
Alphabet last closed at $346.47, while the most followed narrative on Simply Wall St pegs fair value near $202.62. This frames the Gemini lawsuits against a stock that some commentators already see as expensive.
"On the middle road the shares are worth $272.54 in three years, $313.86 in five, and $395.49 in ten. Against $356.13 today, that is down about twenty four percent, down about twelve percent, and finally up about eleven percent. Read the last column again. Eleven percent in total after a decade. Call it one percent a year, for owning what may well be the best business of this generation, through ten years of headlines and lawsuits and product cycles."
See why 246 investors see Alphabet as 71% overvalued.
Result: Fair Value of $202.62 (OVERVALUED)
Still, the thesis that Alphabet is 71% overvalued could be shaken if legal outcomes on antitrust and Gemini, or AI infrastructure returns, turn out differently than expected.
Find out about the key risks to this Alphabet narrative.
Another View on Alphabet’s Valuation
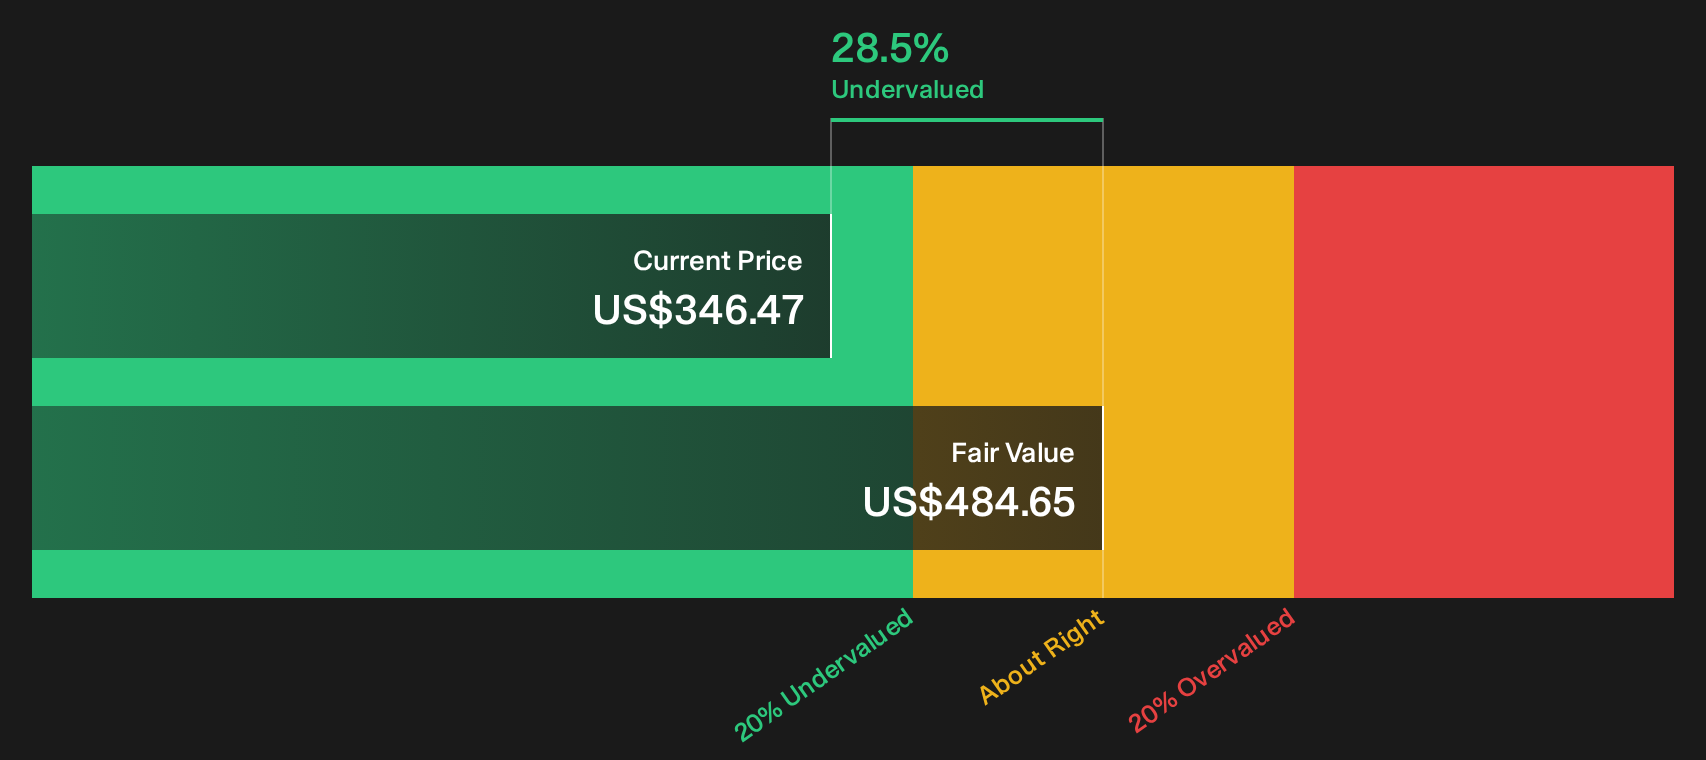
The narrative around Alphabet leans heavily on future cash flows and scenario analysis, yet the current SWS DCF model presents a different perspective. At $346.47 the stock is described as trading below an estimated future cash flow value of $484.65, which implies undervaluation rather than a stretched price. Which story should an investor lean on when both are built from detailed assumptions?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
If the split views on Alphabet leave you unsure, that is the point. Act quickly, review the data on both sides, and weigh the 4 key rewards and 2 important warning signs.
Looking for more ideas beyond Alphabet?
Alphabet may be front of mind today, but your next compelling opportunity could sit somewhere very different on the market map.
- Target resilient returns by focusing on companies that have held up well in tougher conditions, starting with 31 resilient stocks with low risk scores.
- Pursue quality at a sensible price by scanning for companies with strong fundamentals that trade below intrinsic value through 27 high quality undervalued stocks.
- Strengthen your income stream by zeroing in on reliable payers using the 7 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com