
Constellation Energy (CEG) Shares Just Moved, So What Is Driving Attention?
Constellation Energy (CEG) drew fresh attention after announcing a long-term agreement with Amazon tied to the Calvert Cliffs Clean Energy Center, supporting more than US$3b of planned infrastructure investment in Maryland.
The Amazon agreement lands at a tricky moment for Constellation Energy’s shareholders. The stock is up 3.93% on a 1 day share price return to US$267.62 and has a 90 day share price return of 9.45%. However, it is still down 26.93% on a year to date share price return, with the 1 year total shareholder return declining 24.86%. This follows a very large 3 year total shareholder return of 141.43%, which indicates that recent momentum has cooled while the longer run story remains much stronger.
Scan other potential beneficiaries of the nuclear build out by reviewing our curated list of 19 nuclear energy infrastructure stocks alongside Constellation Energy’s latest agreement with Amazon.
Constellation Energy’s share price has jumped on the Amazon news, while longer-term returns have cooled. Do you press in after the bounce, or wait and hope valuation gives you a cleaner entry?
Most Popular Narrative: 23.5% Undervalued
Against a last close of $267.62, the most followed Constellation Energy narrative anchors fair value at $350. The gap between those two numbers is what the long term thesis tries to explain.
The market is underappreciating how scarce true 24/7 carbon-free baseload has become just as AI data centers and electrification drive the sharpest sustained rise in U.S. power demand in decades. Most investors still treat CEG as a “utility with nuclear exposure.” It is better understood as the owner of the largest, highest-quality fleet of scarce, dispatchable zero-carbon generation that hyperscalers cannot easily replicate or replace.
See why 22 investors see Constellation Energy as 24% undervalued.
Result: Fair Value of $350 (UNDERVALUED)
Still, the Constellation Energy story depends on tight nuclear operations and cooperative regulators, and setbacks on either front could quickly undermine that 23.5% undervalued narrative.
Find out about the key risks to this Constellation Energy narrative.
Another View: Constellation Energy On Earnings Multiples
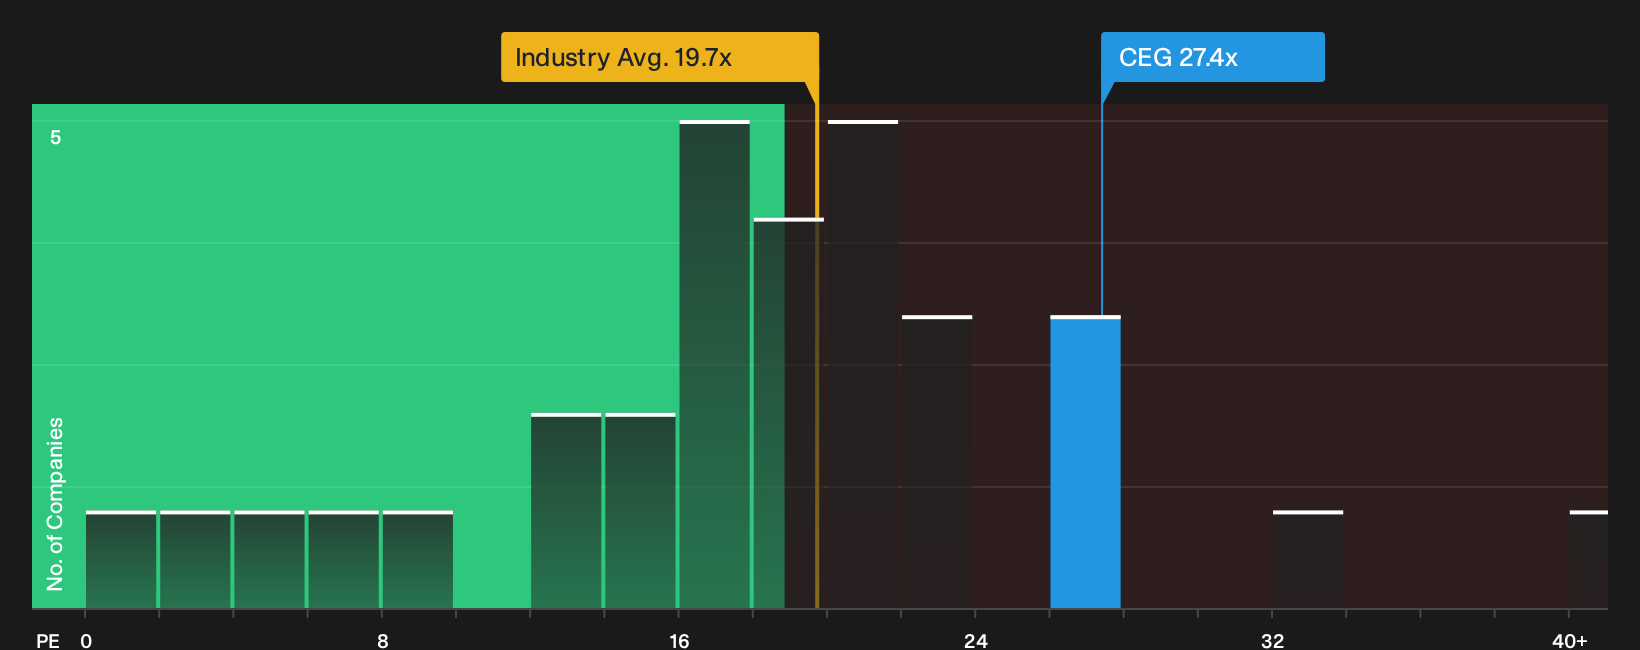
That 23.5% undervalued story leans on fair value estimates, but the P/E picture is less forgiving. Constellation Energy trades at 27.4x earnings compared with 18.9x for peers and 19.7x for the wider US Electric Utilities group. The fair ratio sits at 30x, which suggests some headroom yet still keeps valuation risk squarely on your radar.
For investors weighing that premium against the fair ratio, the key question is whether CEG’s nuclear and data center exposure justifies paying up today or waiting for sentiment to reset. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around Constellation Energy is clearly split, so move quickly to review the full picture for yourself and weigh both sides of the argument. Start by checking the 4 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Constellation Energy?
If Constellation Energy is already on your radar, do not stop there. Broader idea flow can sharpen your judgement and keep your watchlist fresh.
- Target stability first and see which businesses qualify as 31 resilient stocks with low risk scores to anchor the more volatile parts of your portfolio.
- Hunt for quality at a discount by reviewing the 19 high quality undiscovered gems before these opportunities get crowded.
- Strengthen your downside protection and scan the list of solid balance sheet and fundamentals (25 results) so you are not the last to react when conditions change.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com