
UK Stocks With Estimated Value Opportunities For Savvy Investors
The United Kingdom's stock market has recently faced challenges, with the FTSE 100 and FTSE 250 indices experiencing declines amid weak trade data from China, highlighting concerns about global economic recovery. In this environment, identifying undervalued stocks can be crucial for investors looking to capitalize on potential growth opportunities, especially those that may not be as heavily impacted by external economic pressures.
Top 10 Undervalued Stocks Based On Cash Flows In The United Kingdom
| Name | Current Price | Fair Value (Est) | Discount (Est) |
| Stelrad Group (LSE:SRAD) | £1.45 | £2.47 | 41.4% |
| Smiths News (LSE:SNWS) | £0.762 | £1.46 | 47.8% |
| Smith & Nephew (LSE:SN.) | £10.045 | £17.49 | 42.6% |
| Property Franchise Group (AIM:TPFG) | £4.175 | £7.49 | 44.2% |
| Premier Foods (LSE:PFD) | £1.867 | £3.13 | 40.3% |
| PayPoint (LSE:PAY) | £6.405 | £10.72 | 40.2% |
| LSL Property Services (LSE:LSL) | £2.48 | £4.64 | 46.5% |
| Gamma Communications (LSE:GAMA) | £10.92 | £20.18 | 45.9% |
| Distribution Finance Capital Holdings (AIM:DFCH) | £0.746 | £1.37 | 45.6% |
| Autotrader Group (LSE:AUTO) | £4.606 | £7.69 | 40.1% |
Here's a peek at a few of the choices from the screener.
Property Franchise Group (AIM:TPFG)
Overview: The Property Franchise Group PLC operates in the United Kingdom, focusing on residential property franchising, licensing, and financial services, with a market cap of £266.41 million.
Operations: The company's revenue is derived from three main segments: £12.65 million from licensing, £25.40 million from financial services, and £49.23 million from property franchising.
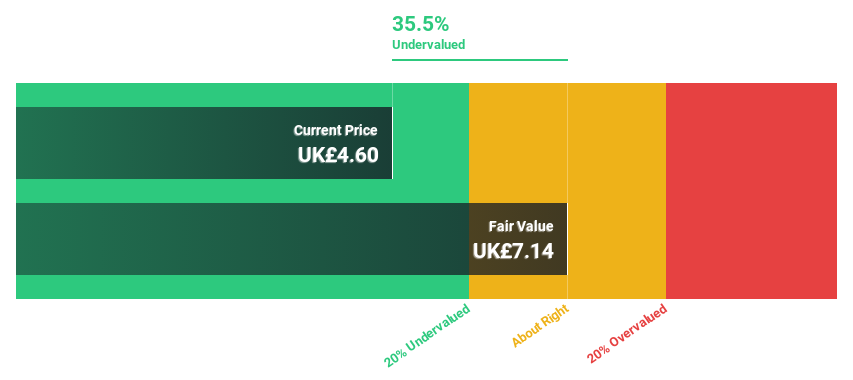
Estimated Discount To Fair Value: 44.2%
Property Franchise Group is trading at £4.18, significantly below its estimated future cash flow value of £7.49, indicating it may be undervalued based on cash flows. Despite a 10% dividend increase to 7.7 pence per share, the company's earnings growth forecast of 7.66% annually lags behind the UK market average of 11.1%. Recent earnings showed sales growth but a decline in net income, highlighting potential challenges in sustaining profitability amidst slower-than-market growth expectations.
- Our growth report here indicates Property Franchise Group may be poised for an improving outlook.
- Delve into the full analysis health report here for a deeper understanding of Property Franchise Group.
Jupiter Fund Management (LSE:JUP)
Overview: Jupiter Fund Management Plc is a publicly owned investment manager with a market cap of £828.51 million.
Operations: The company generates revenue of £490.40 million from its Investment Management Business segment.
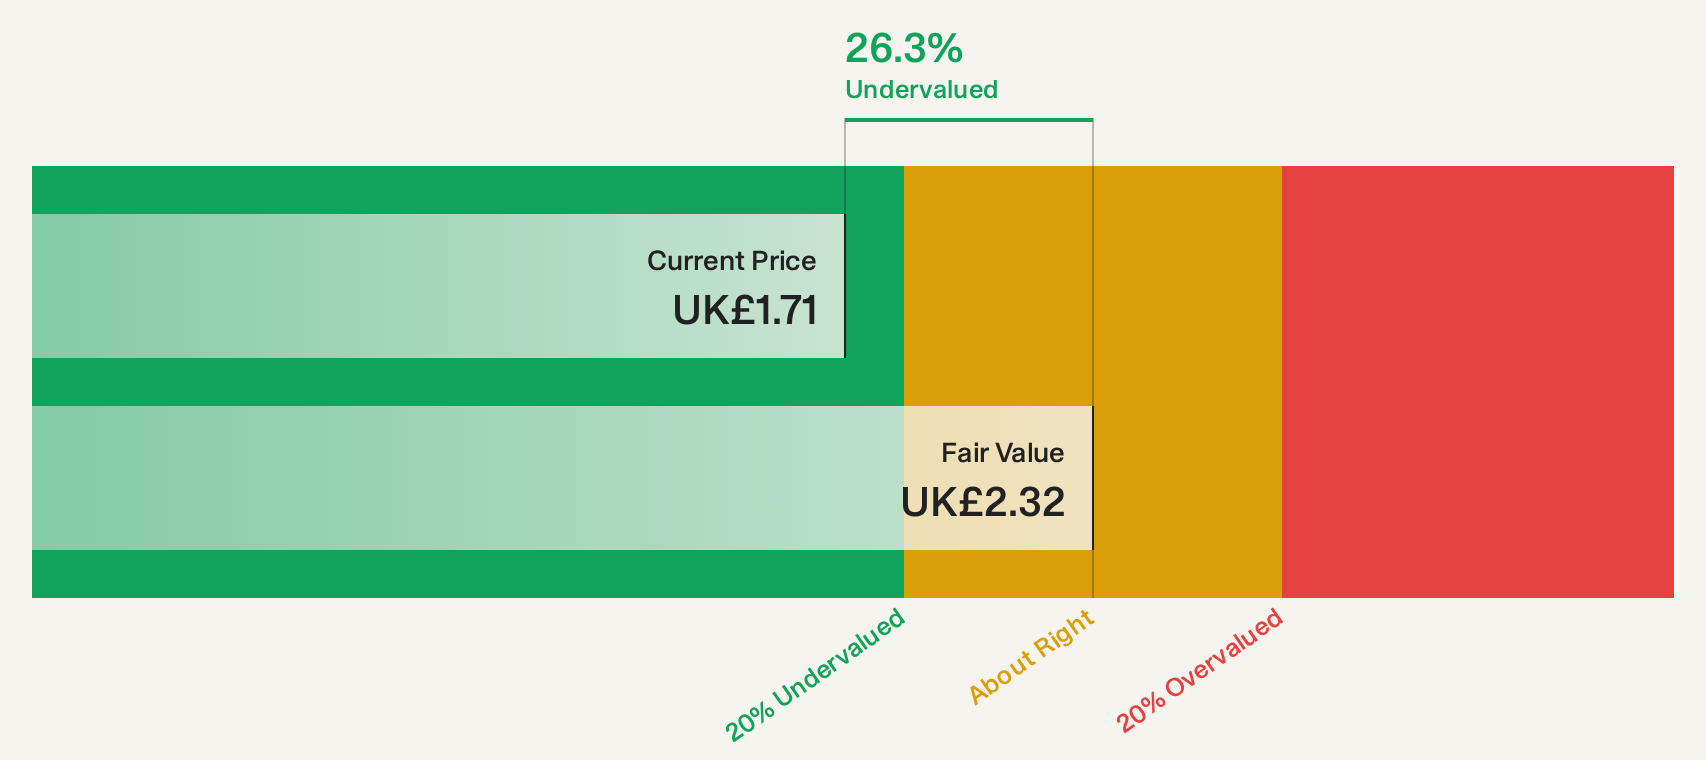
Estimated Discount To Fair Value: 25.5%
Jupiter Fund Management is trading at £1.66, below its estimated future cash flow value of £2.23, suggesting undervaluation based on cash flows. Recent earnings showed a revenue increase to £213.3 million and net income growth to £25.1 million for the half-year ended June 2026. Despite this growth, forecasts indicate declining earnings and revenue over the next three years, alongside an unstable dividend track record, posing potential challenges for sustained profitability.
- The growth report we've compiled suggests that Jupiter Fund Management's future prospects could be on the up.
- Click to explore a detailed breakdown of our findings in Jupiter Fund Management's balance sheet health report.
Luceco (LSE:LUCE)
Overview: Luceco plc, with a market cap of £310.24 million, designs, manufactures, and delivers residential and commercial electrification products and systems across the United Kingdom, Europe, the Americas, the Middle East, Africa, and the Asia Pacific.
Operations: The company's revenue is derived from three main segments: LED Lighting (£80.60 million), Portable Power (£72.40 million), and Wiring Accessories (£135.30 million).
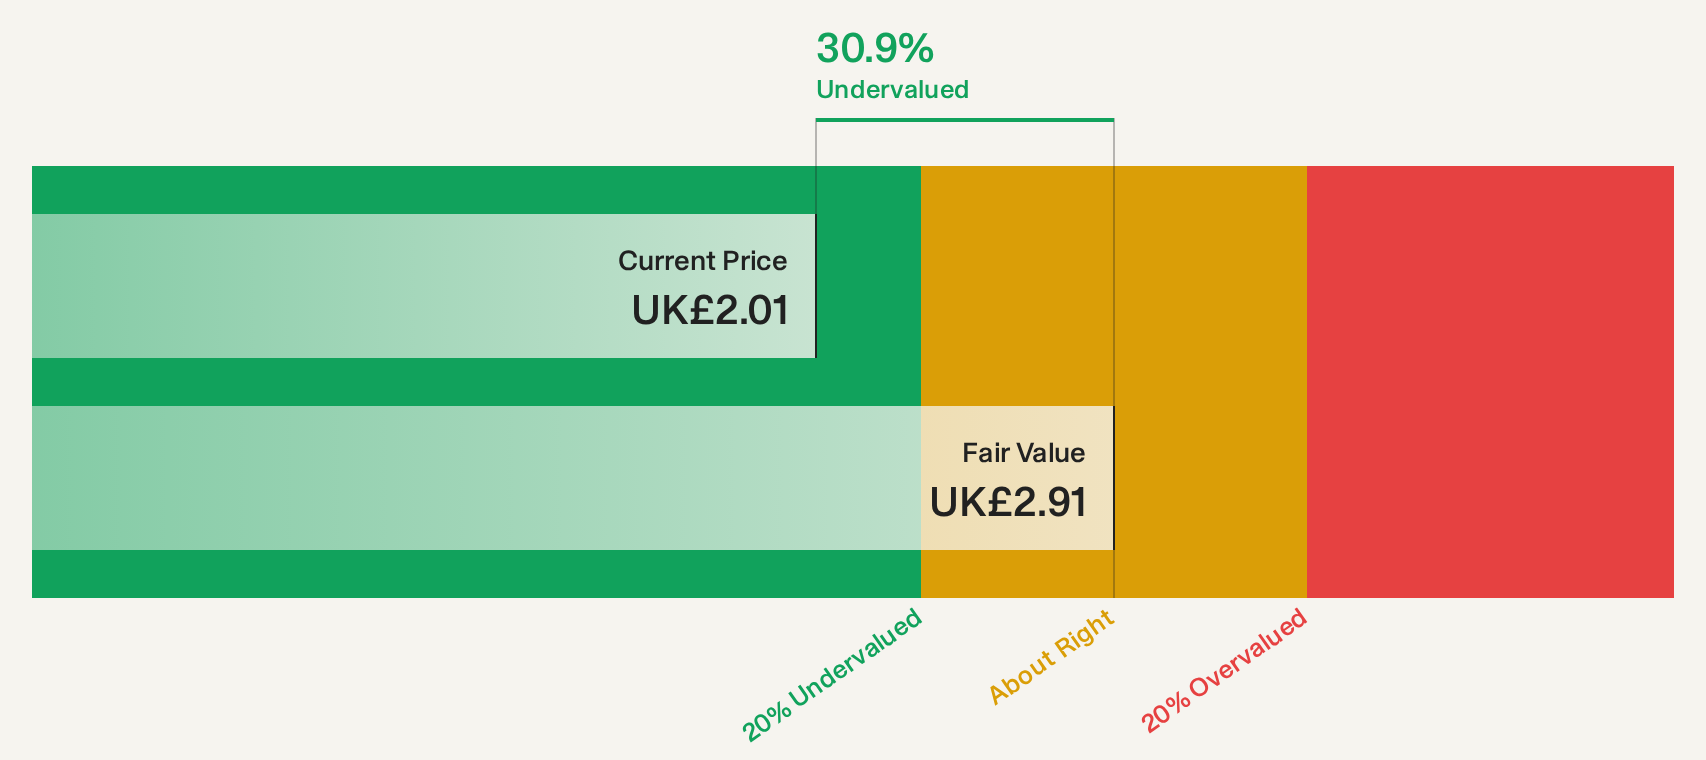
Estimated Discount To Fair Value: 28.1%
Luceco is trading at £2.08, below its estimated future cash flow value of £2.89, reflecting potential undervaluation based on cash flows. Recent earnings showed sales growth to £142.6 million and net income of £6.9 million for H1 2026, with earnings per share rising slightly from the previous year. Despite a high debt level and significant insider selling recently, Luceco's revenue and earnings are forecast to grow faster than the UK market averages.
- Insights from our recent growth report point to a promising forecast for Luceco's business outlook.
- Unlock comprehensive insights into our analysis of Luceco stock in this financial health report.
Make It Happen
- Dive into all 28 of the Undervalued UK Stocks Based On Cash Flows we have identified here.
- Have a stake in these businesses? Integrate your holdings into Simply Wall St's portfolio for notifications and detailed stock reports.
- Join a community of smart investors by using Simply Wall St. It's free and delivers expert-level analysis on worldwide markets.
Interested In Other Possibilities?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Diversify your portfolio with solid dividend payers offering reliable income streams to weather potential market turbulence.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com