
Asian Value Stocks Trading Below Estimated Worth In October 2026
In October 2026, the Asian markets have been navigating a complex landscape characterized by fluctuating oil prices and heightened bond yields, which have contributed to investor caution. Amid these challenges, identifying undervalued stocks can be an effective strategy for investors seeking opportunities in a market where economic indicators suggest potential growth. Understanding the intrinsic value of stocks relative to their current trading price is crucial in such an environment, as it allows investors to capitalize on discrepancies between market perception and actual worth.
Top 10 Undervalued Stocks Based On Cash Flows In Asia
| Name | Current Price | Fair Value (Est) | Discount (Est) |
| Shanghai Flyco Electrical Appliance (SHSE:603868) | CN¥31.09 | CN¥61.62 | 49.5% |
| Nissui (TSE:1332) | ¥1101.50 | ¥2180.59 | 49.5% |
| Kingnet Network (SZSE:002517) | CN¥16.01 | CN¥31.56 | 49.3% |
| Innodisk (TPEX:5289) | NT$1295.00 | NT$2530.08 | 48.8% |
| Ichikoh Industries (TSE:7244) | ¥545.00 | ¥1066.82 | 48.9% |
| Hainan Jinpan Smart Technology (SHSE:688676) | CN¥61.53 | CN¥121.78 | 49.5% |
| Foxconn Industrial Internet (SHSE:601138) | CN¥58.20 | CN¥113.22 | 48.6% |
| ENN Energy Holdings (SEHK:2688) | HK$48.70 | HK$96.84 | 49.7% |
| Double Medical Technology (SZSE:002901) | CN¥40.86 | CN¥79.59 | 48.7% |
| China Coal Energy (SEHK:1898) | HK$10.19 | HK$20.11 | 49.3% |
Let's take a closer look at a couple of our picks from the screened companies.
Luk Fook Holdings (International) (SEHK:590)
Overview: Luk Fook Holdings (International) Limited operates as an investment holding company involved in the sourcing, designing, wholesaling, trademark licensing, and retailing of gold and platinum jewelry and gem-set jewelry products in Hong Kong and internationally, with a market cap of approximately HK$12.63 billion.
Operations: The company's revenue segments include Retailing - Hong Kong, Macau and Overseas at HK$10.05 billion, Retailing - Mainland at HK$3.82 billion, Wholesaling - Mainland at HK$3.14 billion, Wholesaling - Hong Kong at HK$2.59 billion, and Licensing generating HK$996.90 million.
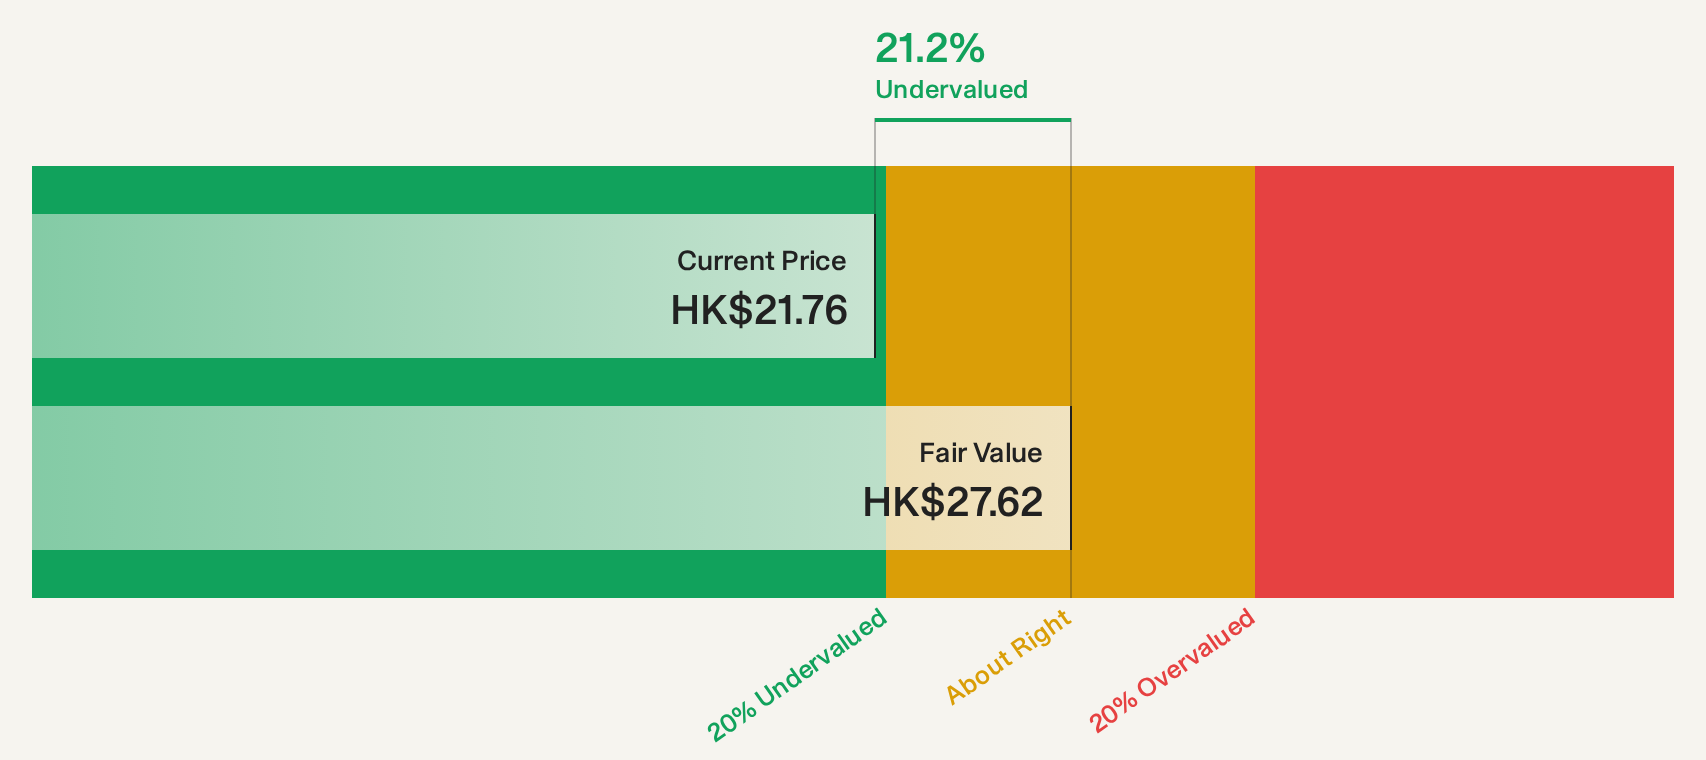
Estimated Discount To Fair Value: 22.4%
Luk Fook Holdings (International) appears undervalued based on cash flows, trading at HK$21.52 below its estimated future cash flow value of HK$27.72. Despite a forecasted revenue growth of 11.1% annually, which outpaces the Hong Kong market average, earnings are expected to grow slower at 9.6%. Recent sales figures show significant growth in investment gold products with retail sales volume rising by 32% year-on-year in the first quarter, enhancing its cash flow potential despite a dividend not fully covered by free cash flows.
- The analysis detailed in our Luk Fook Holdings (International) growth report hints at robust future financial performance.
- Click here and access our complete balance sheet health report to understand the dynamics of Luk Fook Holdings (International).
Sumitomo Chemical Company (TSE:4005)
Overview: Sumitomo Chemical Company, Limited operates in diverse sectors including Agro & Life Solutions, ICT & Mobility Solutions, Advanced Medical Solutions, Essential & Green Materials, and Sumitomo Pharma with a market cap of ¥966.06 billion.
Operations: The company's revenue is primarily derived from Agro & Life Solutions (¥532.45 billion), ICT & Mobility Solutions (¥586.54 billion), Advanced Medical Solutions (¥72.67 billion), Essential & Green Materials (¥688.65 billion), and Sumitomo Pharma (¥474.79 billion).
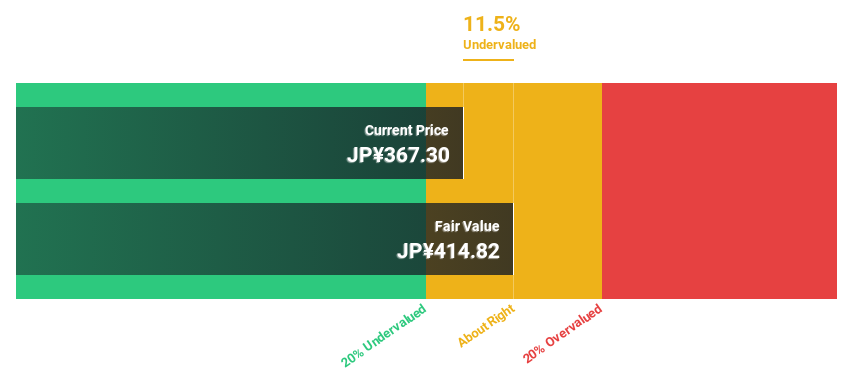
Estimated Discount To Fair Value: 30.7%
Sumitomo Chemical Company is trading at ¥583.2, below its estimated future cash flow value of ¥842.01, indicating it is undervalued based on cash flows. Despite a recent earnings surge with net income reaching ¥40.78 billion from a previous loss, forecasts show declining earnings and slower revenue growth compared to the Japanese market average. The company recently announced two unsecured bond offerings totaling ¥40 billion, highlighting ongoing financial restructuring efforts amidst an unstable dividend history.
- According our earnings growth report, there's an indication that Sumitomo Chemical Company might be ready to expand.
- Navigate through the intricacies of Sumitomo Chemical Company with our comprehensive financial health report here.
Zeon (TSE:4205)
Overview: Zeon Corporation operates in the elastomer materials and specialty materials sectors across Japan, North America, Europe, and Asia, with a market cap of ¥467.65 billion.
Operations: The company's revenue is primarily derived from the Elastomer Materials Business, which accounts for ¥223.77 billion, and the Specialty Materials Business, contributing ¥128.76 billion.
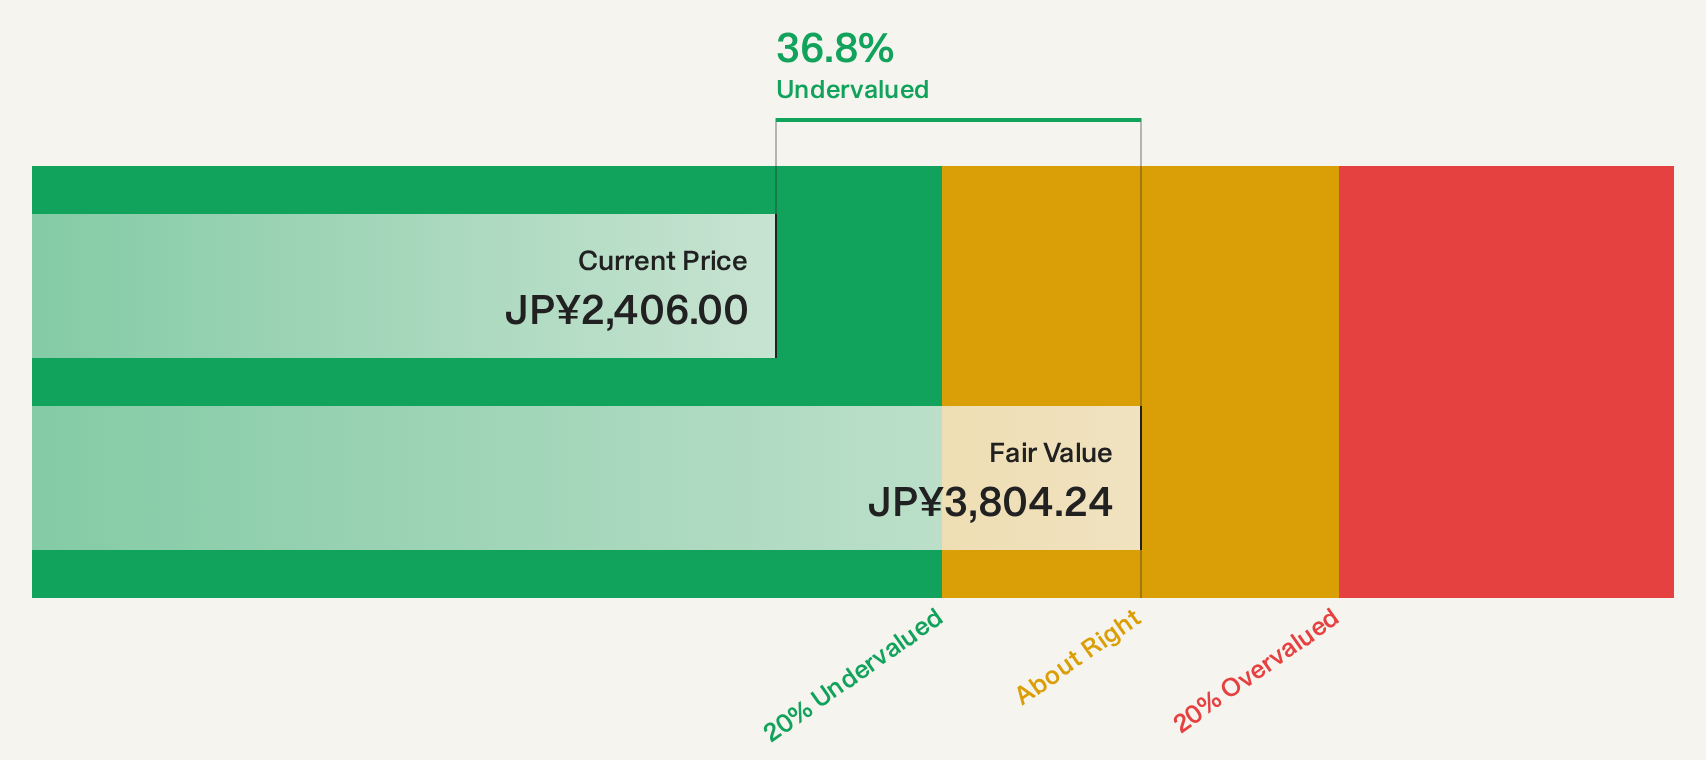
Estimated Discount To Fair Value: 35.8%
Zeon Corporation is trading at ¥2,444, significantly below its estimated future cash flow value of ¥3,805.94, highlighting its undervaluation based on cash flows. Recent earnings showed a strong increase in net income to ¥12.71 billion from the previous year's ¥7.51 billion. Despite this growth and good relative value compared to peers, forecasts indicate declining earnings over the next three years and slower revenue growth than the Japanese market average.
- Our growth report here indicates Zeon may be poised for an improving outlook.
- Get an in-depth perspective on Zeon's balance sheet by reading our health report here.
Key Takeaways
- Embark on your investment journey to our 164 Undervalued Asian Stocks Based On Cash Flows selection here.
- Are these companies part of your investment strategy? Use Simply Wall St to consolidate your holdings into a portfolio and gain insights with our comprehensive analysis tools.
- Join a community of smart investors by using Simply Wall St. It's free and delivers expert-level analysis on worldwide markets.
Want To Explore Some Alternatives?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Diversify your portfolio with solid dividend payers offering reliable income streams to weather potential market turbulence.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com