
LSL Property Services Stock And 2 British Undervalued Stocks
With the British government warned it is unprepared for food supply shocks, investors are being reminded how quickly essential services and cash flows can be tested when systems come under strain. When markets worry about resilience, cash generation and valuation gaps start to matter more. This article highlights three United Kingdom companies where projected cash flows look attractive relative to current prices, based on the Screener’s discounted cash flow work.
The three stocks below are a sample set, with the full screen surfacing 25 more companies with similarly cash rich stories that are not covered here. If you want to go straight to the broader opportunity set, use the Undervalued Stocks Based On Cash Flows screener to identify, compare, and analyze the highest conviction ideas aligned with your own criteria.
LSL Property Services (LSE:LSL)
LSL Property Services runs a capital light platform across mortgage advice, property surveying and franchised estate agency in the UK. Its £110.7 million Surveying & Valuation arm is a key source of recurring cash flows that underpin this cash based undervaluation theme. Financial Services brings in £48.2 million and Estate Agency £26.7 million, while the overall market cap sits near £244 million.
For value focused investors, LSL Property Services is interesting because a large part of its business revolves around repeat, fee based work where cash inflows can be modelled with reasonable confidence. This is exactly what this screener is trying to surface.
"Structural growth in the private rental sector, supported by LSL’s program of lettings book acquisitions for franchisees, is expanding high visibility, recurring income streams. This can smooth cyclicality in housing transactions and support group revenue resilience and net margins."
What matters from here is how one quiet assumption about future pricing power feeds through to that cash flow story.
That pricing power question is exactly what the full narrative for LSL Property Services unpacks. It shows where recurring cash flows could be accelerating or quietly stalling.
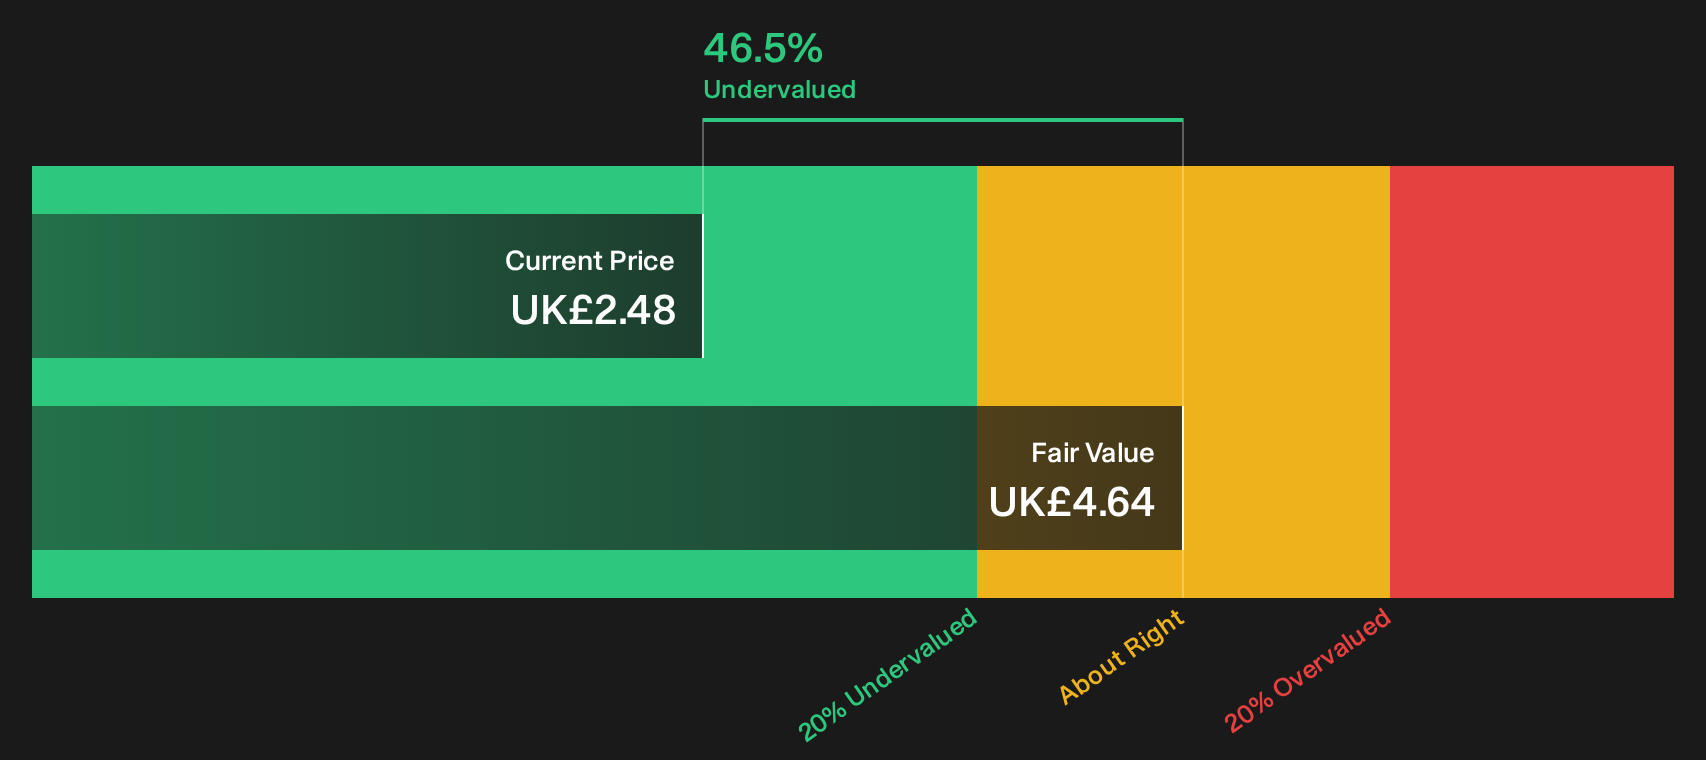
Smiths News (LSE:SNWS)
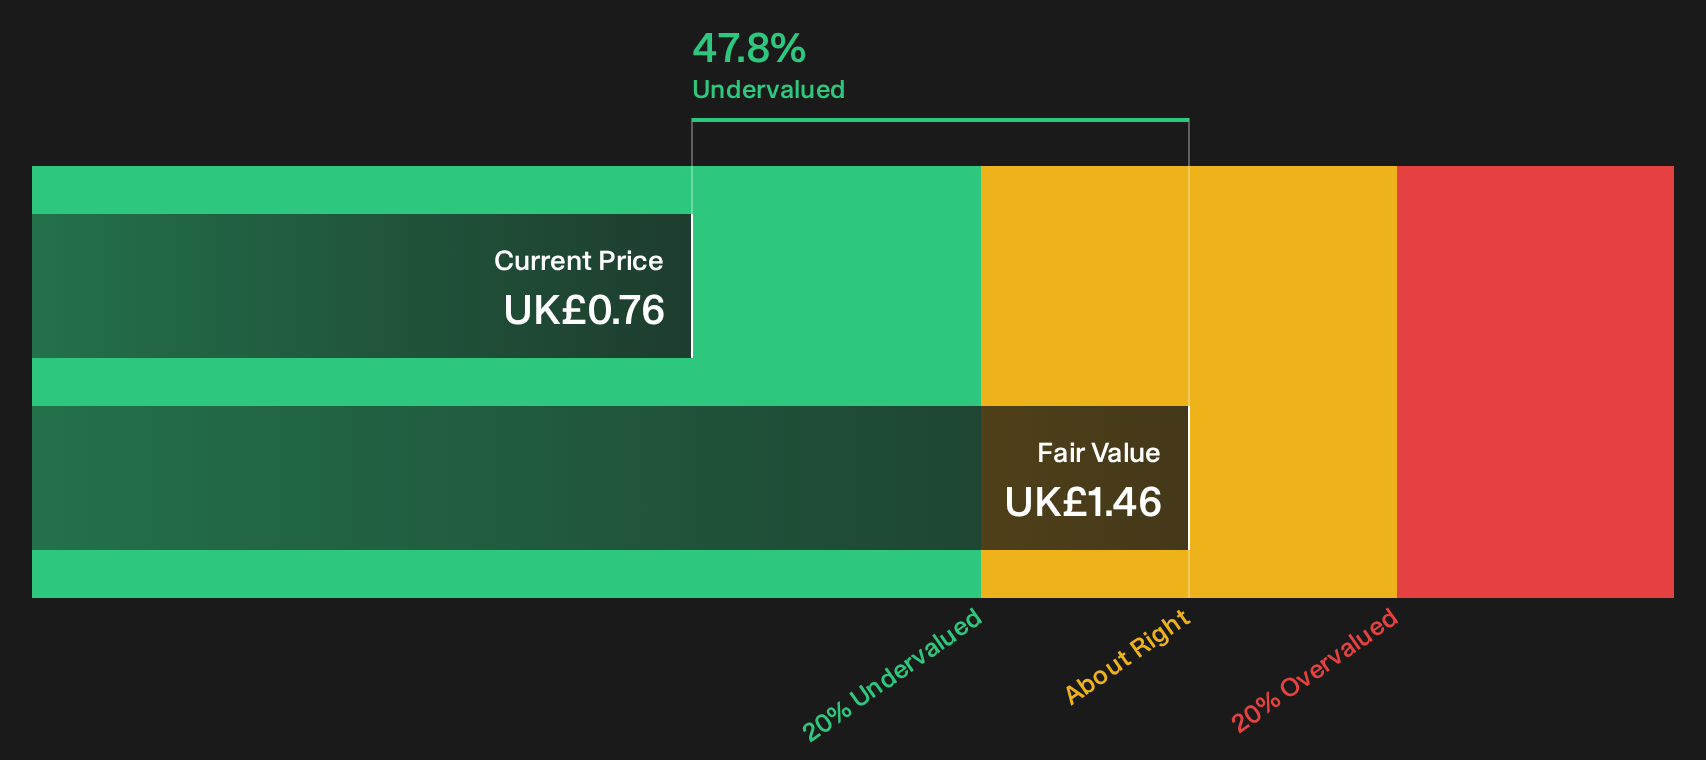
Smiths News runs a newspaper, magazine and retail product distribution network that generates recurring cash flows from long-term publisher and retailer contracts, supported by recycling and merchandising services. It produced about £1.04b of revenue from its distribution segment and has a market value near £184 million.
For this screener, Smiths News is interesting because those long-term UK distribution contracts create relatively visible cash inflows, while the shares trade on a low 6.8x P/E and about 48% below SWS’s DCF fair value. The appeal depends on how that contracted volume affects future margins if a single key assumption about earnings resilience changes.
If that earnings resilience assumption proves significantly wrong or right, the 2 key rewards and 2 important warning signs (1 is major!) could highlight where Smiths News is quietly decoupling.
Gamma Communications (LSE:GAMA)
Gamma Communications builds cloud-based voice and contact-centre subscriptions that fit squarely with this screener’s focus on recurring cash flows, with Enterprise bringing in £136 million and Germany SME £120.7 million. Other Europe adds £31.2 million, while the group’s market value is about £973 million.
For investors scanning for dependable cash generation rather than one-off wins, Gamma Communications links recurring cloud telephony subscriptions to a structural shift in how European businesses communicate, which is exactly where the discounted cash flow work finds most of the potential.
"The adoption of cloud-based communications in large European markets, especially Germany, which has significantly lower cloud penetration (<20%) than the UK, provides Gamma with long-term growth potential as German SMEs and enterprises migrate from legacy PBX to cloud platforms; this underpins recurring revenue expansion and sustained volume growth."
What really matters now is how one less visible pressure on future profitability shapes the cash returns that those subscriptions can actually support.
If that pressure on profitability is exactly what you want to unpack, read the full narrative for Gamma Communications to see where Gamma Communications’ cash engine could be accelerating or stalling.

Seeking Fresh Alternatives Before They Fly
Fresh ideas move first. Breakout stories gain momentum while data is still under the radar for now. Do not get caught dropping in late, get in early.
- Target steady cash machines by scanning the 1 dividend fortresses that aim to keep income flowing while prices are still adjusting and attention has not fully arrived.
- Chase rapid growth potential through the 3 AI small caps before enthusiasm spreads widely and valuations move beyond what disciplined buyers are willing to pay.
- Track early infrastructure momentum with the 39 power grid technology and infrastructure stocks while the energy transition theme is building beneath the surface and select operators remain mispriced.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com