
Is Global Payments (GPN) Undervalued On Its Worldpay Integration Story?
Global Payments (GPN) has drawn fresh attention after its recent trading swings, with the stock up 4.8% in the latest session but down 11.2% over the past month. Investors are reassessing what that volatility implies.
Recent trading has been choppy for Global Payments, with the latest 1-day share price return of 4.85% coming after a 30-day share price decline of 11.2%. The year-to-date share price return of 8.8% contrasts with a 1-year total shareholder return that is down 4.5%, highlighting improving short-term momentum alongside weaker longer-run results.
Scan beyond Global Payments and explore other payment and fintech stocks showing similar turbulence with our curated list of 27 high quality undervalued stocks.
Bulls point to Global Payments’ recent share rebound, improving short-term returns, and solid annual revenue and net income growth. Bears focus on weaker multi-year performance. Which story does the current valuation appear to reflect?
Most Popular Narrative: 21% Undervalued
Global Payments is trading at $82.18 against a widely followed fair value estimate of $104.39, so the market price lags the narrative by a wide margin.
The Worldpay acquisition and operational transformation program are creating scale benefits, cost efficiencies, and significant cross-selling opportunities (for example, selling Genius into Worldpay's merchant base). These are expected to boost earnings growth and margin expansion after integration.
See why 43 investors see Global Payments as 21% undervalued.
Result: Fair Value of $104.39 (UNDERVALUED)
Still, the Global Payments narrative can crack if the integration of Worldpay drags on profitability or if rising competition squeezes fees faster than analysts currently build into their models.
Find out about the key risks to this Global Payments narrative.
Another View on Global Payments Valuation
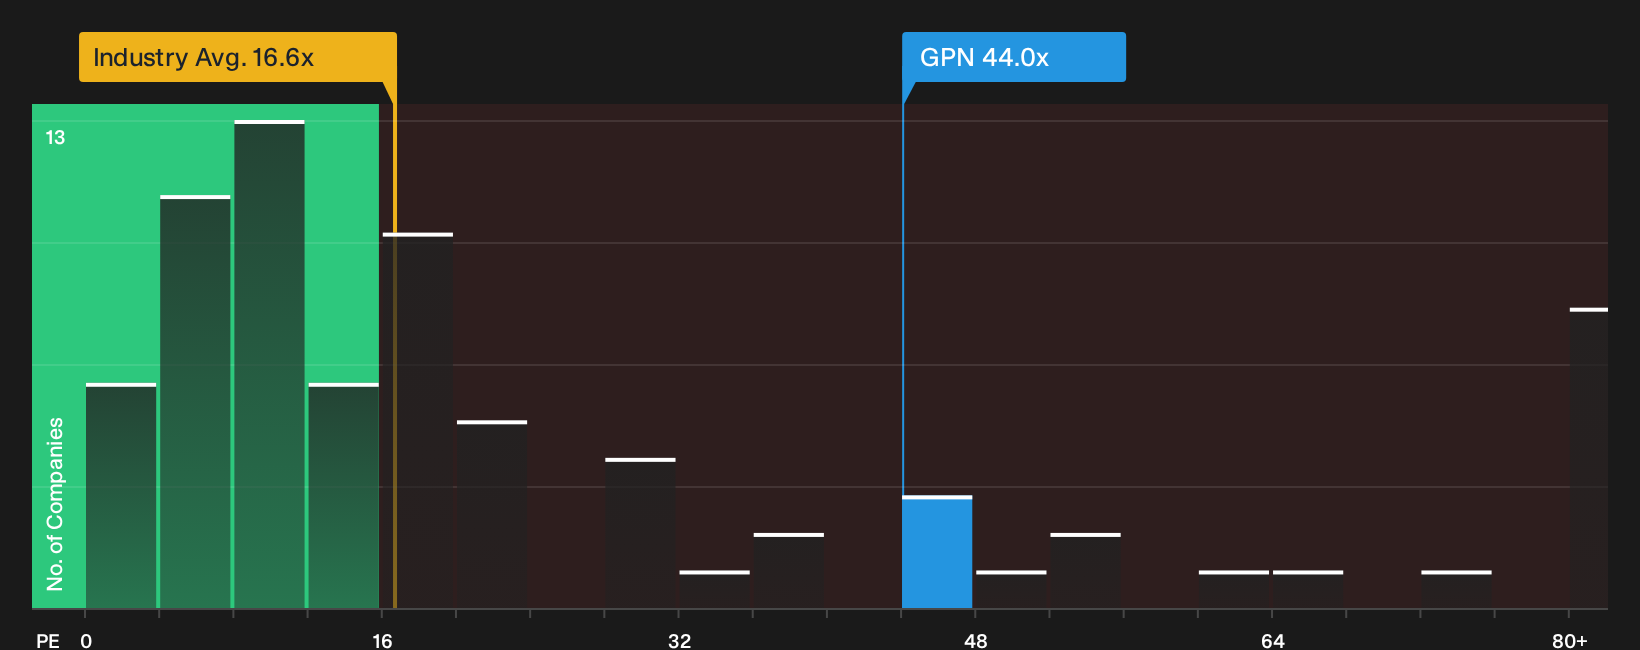
The fair value narrative presents Global Payments as 21% undervalued at $82.18 versus $104.39. The earnings multiple tells a different story. The stock trades on a P/E of 44x compared with 16.6x for the US Diversified Financial industry and 12.6x for peers, while the fair ratio is 30.2x. That gap suggests investors are already paying a premium, so the question is whether the story justifies that extra multiple.
For a closer look at how this pricing gap lines up with earnings power and peer comparisons, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Conflicted about whether Global Payments’ recent swings tell a bullish or cautious story overall? Act while the data is fresh and weigh both sides for yourself with 2 key rewards and 3 important warning signs.
Looking for more Global Payments investment ideas?
If Global Payments has you thinking harder about valuation and risk, do not stop with one stock. Use fresh screeners to spot other opportunities quickly.
- Spot potential bargains early by scanning companies that score as 19 high quality undiscovered gems before they attract wider attention.
- Prioritise resilience and sleep better at night by focusing on businesses in our 31 resilient stocks with low risk scores that score well on financial strength.
- Target quality balance sheets and solid fundamentals using the list of solid balance sheet and fundamentals (25 results) to narrow your watchlist to sturdier candidates.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com