
What Harmonic (HLIT)'s Comcast Recon Launch Means For Shareholders
- Harmonic reported that Comcast’s XMFR-based Recon monitoring platform is now available to broadband operators and that Lightcurve is using Harmonic’s cOS virtualized broadband system to deliver multi-gigabit service over existing coax in multi-dwelling units.
- The combination of Recon’s fiber diagnostics and Lightcurve’s software-led upgrade path highlights how Harmonic is pushing deeper into higher value, data-rich broadband operations rather than focusing solely on access hardware.
- We will look at how Harmonic's investment narrative is affected by the Recon monitoring rollout with Comcast and Lightcurve's cOS deployment.
Harmonic Investment Narrative Recap
For Harmonic, the core belief is that broadband operators will keep investing in smarter, more software centric networks, and that this will support demand for cOS, SaaS tools and data driven monitoring. The big near term swing factor is how quickly operators turn strong interest in next generation broadband into live projects and revenue, especially after a year of weaker margins.
The Comcast backed Recon rollout and Lightcurve deployment both speak to that same operational story, but the financial impact from these specific wins is not yet clear. Customer concentration around Comcast still matters. Any slowdown in large operator spending or pressure on pricing would remain the main risk to the Harmonic thesis.
The Recon launch with Comcast looks most relevant here because it shows Harmonic moving further into ongoing, data heavy broadband operations rather than one off access hardware deals. Continuous monitoring tied into cOS SensAI can deepen integration with existing customers and potentially support more recurring style software and services revenue over time.
That direction aligns with the key catalysts analysts focus on, such as higher margin SaaS, recurring contracts and AI driven automation. It also intersects directly with the risk that rapid technology shifts or open architectures make Harmonic less differentiated. Execution on Recon deployments, beyond Comcast and across more operators, will be an important proof point for that operational pivot.
Harmonic's current analyst story centers on revenue reaching $609.8 million and earnings of $92.1 million by 2029, based on a forecast 15.3% yearly revenue growth rate, with earnings expected to rise by about $83.6 million from $8.5 million today.
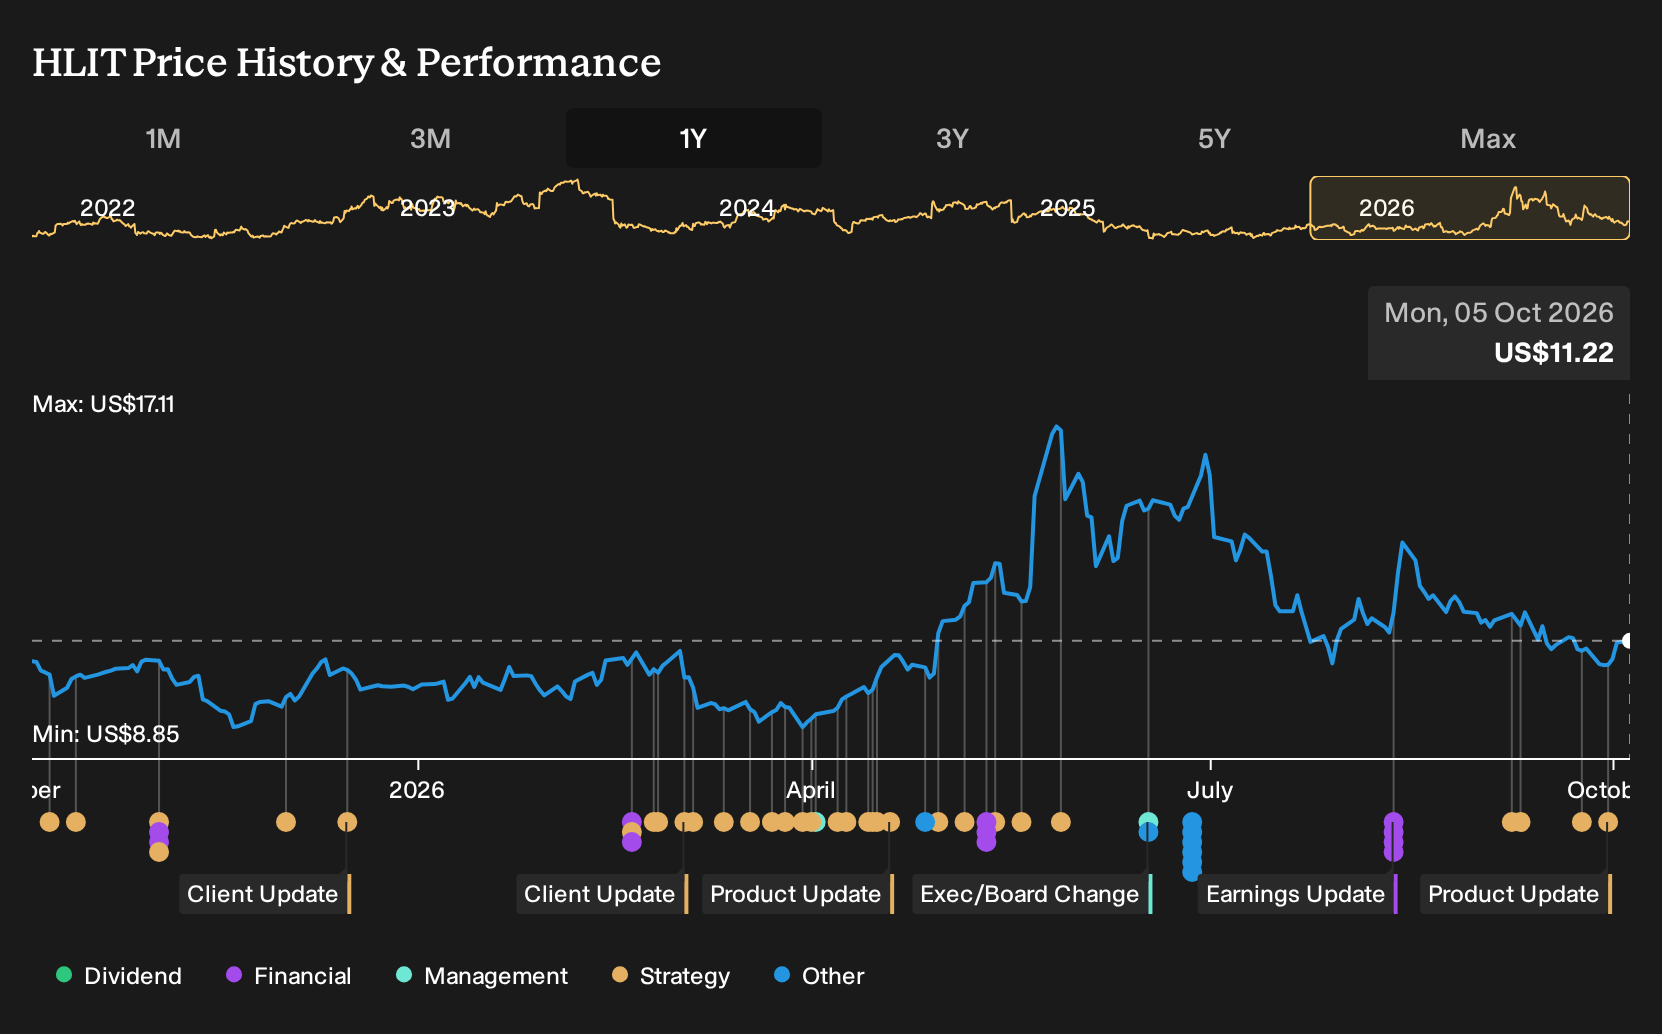
Uncover why Harmonic's fair value indicates a 36% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Some of the lowest Harmonic forecasts focus on customer concentration risk rather than broadband upside. Those analysts see revenue only reaching about US$571.0 million and earnings of roughly US$80.0 million by 2029. That is a more cautious story than consensus, and the new Recon and Lightcurve news could eventually shift either view.
Explore 3 other Harmonic fair value estimates, including one that suggests it could be worth just $14.09!
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Harmonic research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Harmonic. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Harmonic's overall financial health at a glance.
Looking For More Investment Ideas Beyond Harmonic?
Once you have a view on Harmonic, it often helps to line it up against other opportunities using a structured stock screener so you can see what else matches your risk, quality and income preferences.
- If capital preservation sits high on your list, start with a focus on resilience and balance sheet strength and scan a set of 31 resilient stocks with low risk scores that may better fit a steadier approach.
- If dependable cash returns appeal to you, consider income focused opportunities and review a pool of 7 dividend fortresses that might suit a yield driven plan.
- If you prefer to hunt where fewer investors are looking, broaden your watchlist with a collection of 19 high quality undiscovered gems that combine solid fundamentals with lower visibility.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com