
Macmahon Holdings (ASX:MAH) Extends Daisy Milano Contract, Is The Stock Already Fully Valued?
Macmahon Holdings contract extension and why it matters
Macmahon Holdings (ASX:MAH) has secured a two year A$98 million extension at Vault Minerals' Daisy Milano Gold Mine in Western Australia, keeping underground services in place until the end of October 2028.
Investors have already been pricing in a stronger story at Macmahon Holdings, with the share price delivering a 57.14% year to date return and a very large 3 year total shareholder return. The 4.50% 1 day share price gain points to fresh enthusiasm around the Daisy Milano extension.
Compare Macmahon Holdings' contract momentum with a hand picked 15 high quality undiscovered gems that may also be securing long term deals in critical mining and infrastructure projects.
Macmahon Holdings now has firm contracts, rising earnings and a share price that has already moved hard. The real tension is whether that operational strength is already fully reflected in today’s A$1.045 valuation.
Most Popular Narrative: 8% Undervalued
The prevailing narrative pitches Macmahon Holdings as modestly undervalued, with a fair value of A$1.14 against the last close at A$1.045. That gap is not huge, but the thesis leans heavily on how contract wins, acquisitions and project pipelines could keep cash flows supported over several years.
The global push for decarbonisation and increased demand for critical minerals such as copper, nickel, and gold is driving large, long-term project pipelines. This is positioning Macmahon to secure further high-value contracts and underpin strong multi-year revenue growth. Urbanisation and rising infrastructure requirements in Australia and emerging markets (e.g., Southeast Asia and Indonesia) continue to create significant civil and mining project opportunities. This supports expansion into new segments and geographies and offers increased revenue diversification and resilience.
See why 13 investors see Macmahon Holdings as 8% undervalued.
Result: Fair Value of A$1.14 (UNDERVALUED)
Still, the Macmahon Holdings story can change quickly if major contracts are not renewed, or if lower margin civil work, including Decmil, drags on profitability.
Find out about the key risks to this Macmahon Holdings narrative.
Another View on Macmahon Holdings valuation
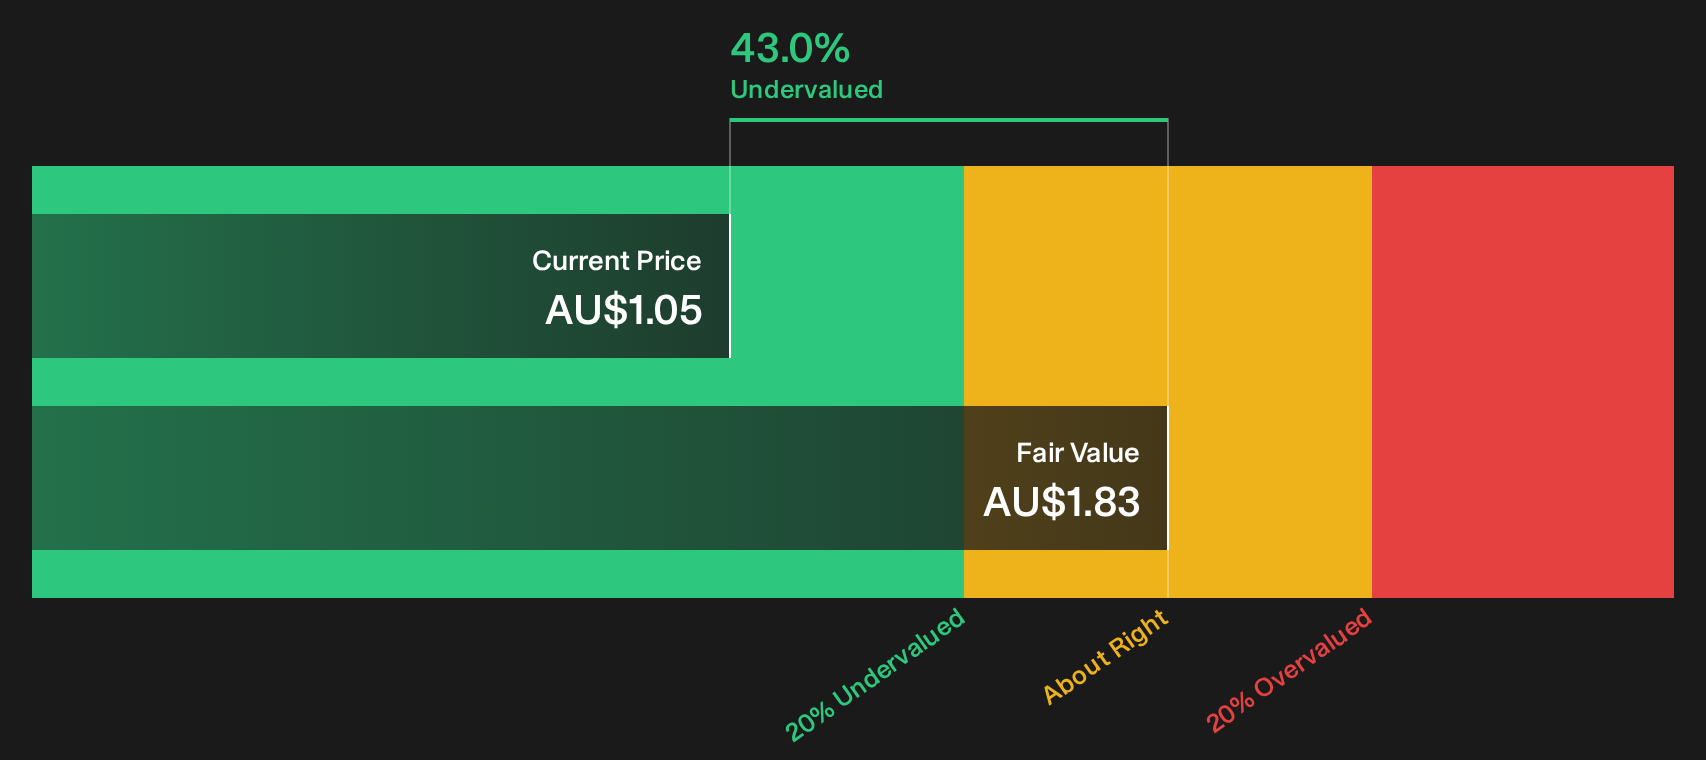
The SWS cash flow model points in a different direction for Macmahon Holdings. At A$1.05, the stock is assessed as trading about 43% below an estimated future cash flow value of A$1.83, which is a much bigger gap than the A$1.14 fair value narrative. Which signal do you trust more?
For a clearer sense of how that cash flow result is built, walk through the full calculation in the Look into how the SWS DCF model arrives at its fair value..
Next Steps
If this Macmahon Holdings story feels compelling on paper, move quickly to test the numbers, stress your own assumptions and weigh the 3 key rewards.
Looking for more investment ideas beyond Macmahon Holdings?
Macmahon Holdings may already be on your radar, but the wider market still holds plenty of overlooked opportunities that could sharpen your portfolio decisions.
- Scan for underappreciated quality by reviewing the 5 high quality undervalued stocks that combine strong fundamentals with prices that may not fully reflect their financial profile.
- Strengthen your income stream by checking the 3 dividend fortresses that pair higher yields with more robust payout histories and balance sheets.
- Dial back portfolio risk by focusing on the 7 resilient stocks with low risk scores where business stability and cleaner financials are front and center.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com