
Top 3 Cash Flow Stocks To Watch In October 2026
Global markets have been whipsawed by sharp moves in government bond yields, as major US allies sell Treasuries and borrowing costs climb. When money becomes more expensive, investors often reprice future profits quickly, which can leave cash generative businesses trading at surprisingly low valuations. This article highlights three companies where current prices appear out of step with their cash flow potential, all identified by our cash flow value screener.
The three stocks below are just a sample pulled from our cash flow value idea. The full screen surfaced 435 more companies with equally compelling narratives that are not covered here. If you want to go straight to the source and size up that wider opportunity set for yourself, head into the Undervalued Stocks Based On Cash Flows screener.
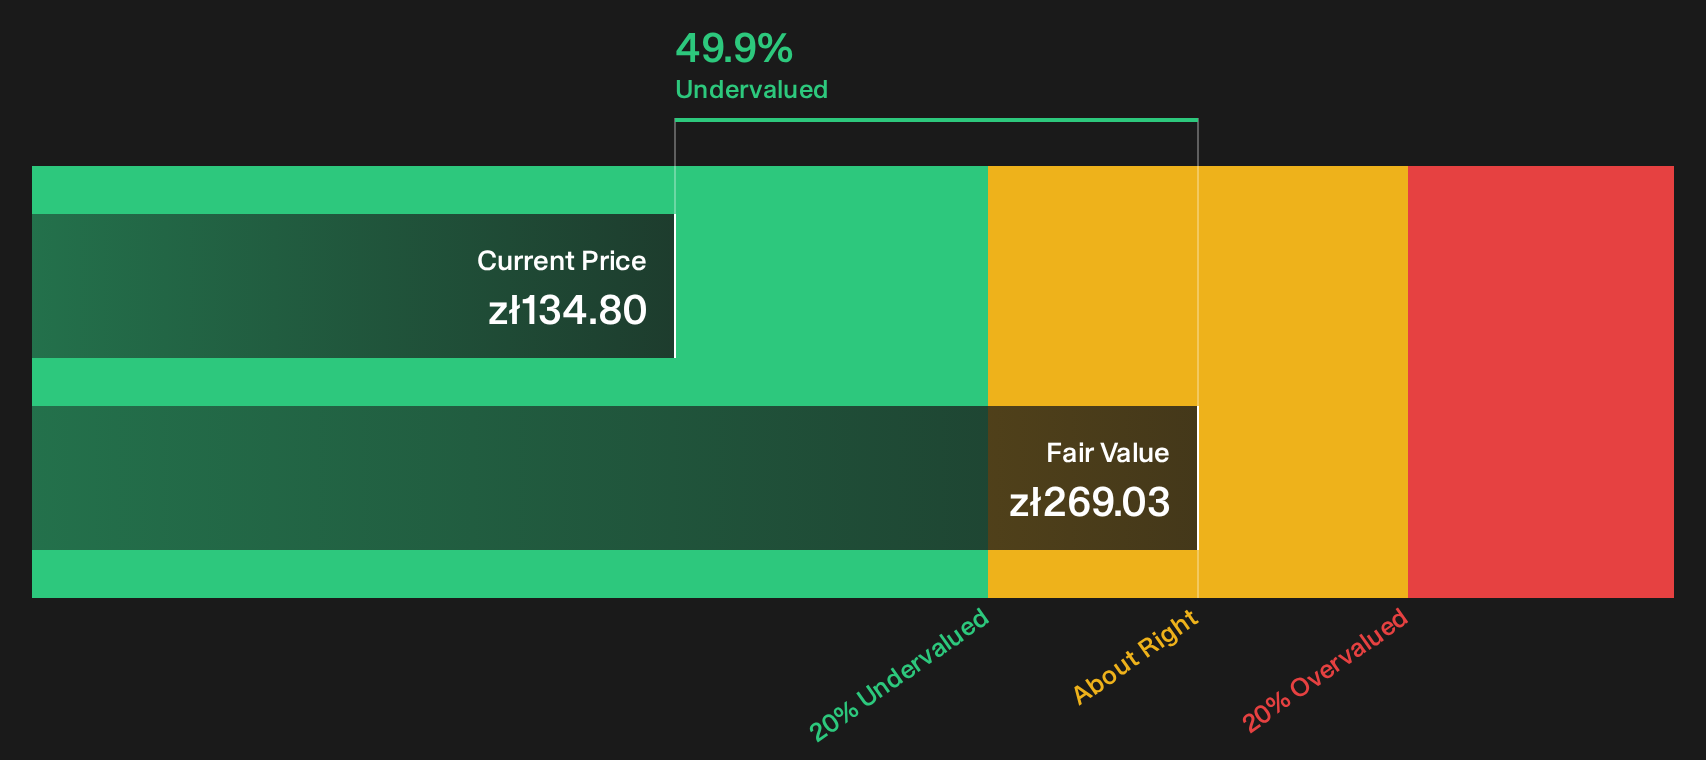
XTB (WSE:XTB)
XTB runs a brokerage platform that lets retail and institutional clients trade ETFs, currencies, commodities, indices, stocks and bonds. This activity feeds the recurring fee and spread income central to this cash flow focused screener.
XTB generates most of its income from Retail Operations, which produced about PLN 3.0b in revenue, compared with roughly PLN 64 million from Institutional Operations. The group is valued at around PLN 15.8b on the Warsaw market.
For value oriented investors, XTB matters because its trading and commission engine produces recurring cash flows that anchor the DCF work behind this screener, and recent execution has given that engine real scale.
"Customer acquisition costs could rise as competition from Interactive Brokers, Revolut, Trading 212 and others intensifies, while CFD revenue remains inherently cyclical."
What that ultimately means for XTB may hinge on whether one quiet pressure helps or hurts the economics of each new client over time.
That quiet pressure is exactly what the full narrative for XTB unpacks, showing how client economics could be shifting and where XTB’s model might still be underappreciated.
Broadcom (AVGO)
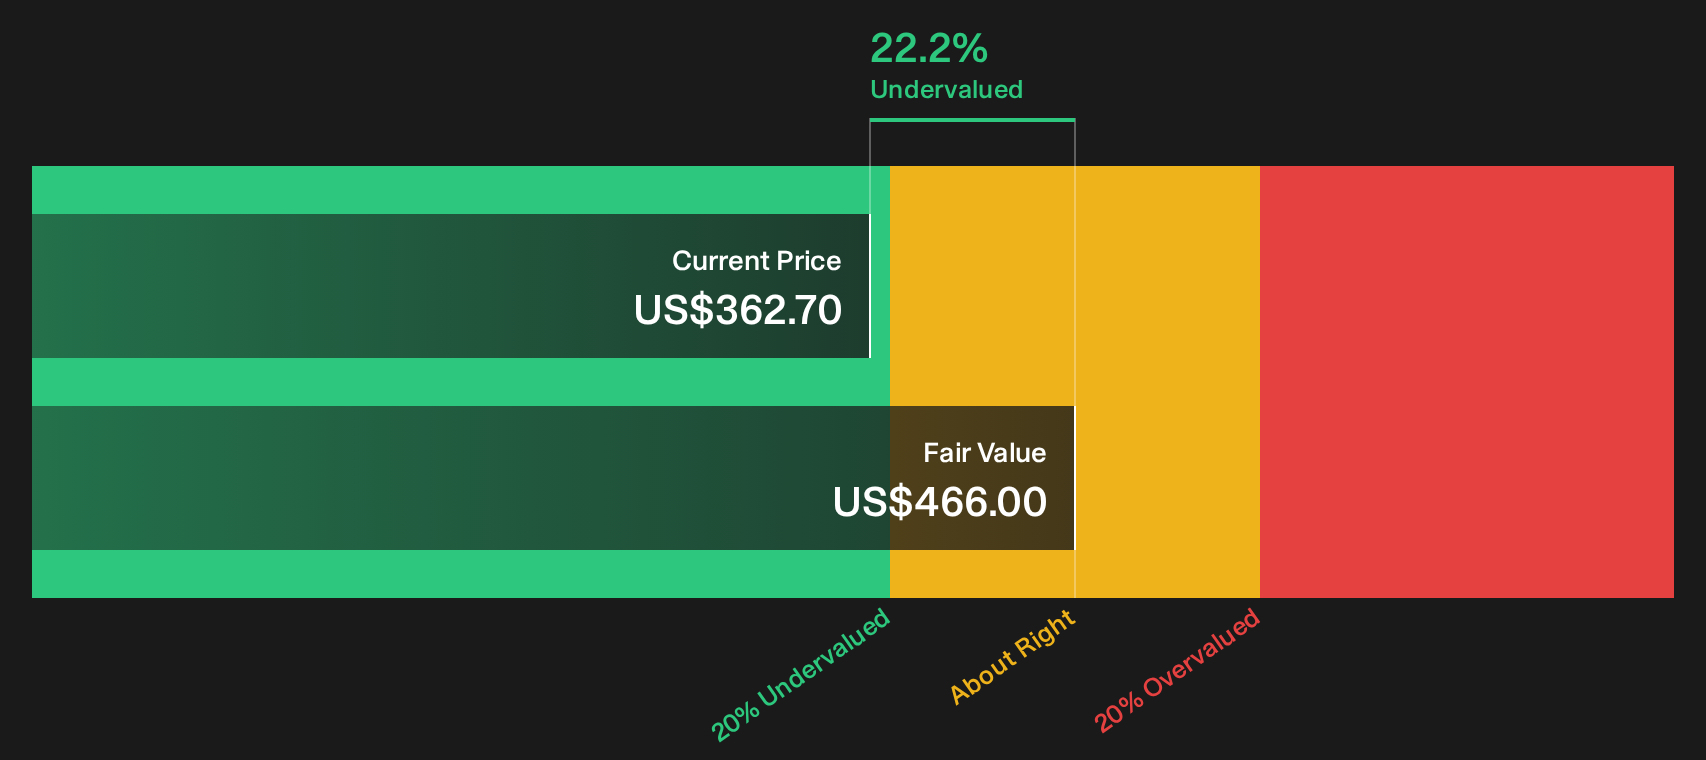
Broadcom blends a large chip business with a growing VMware-based software arm, and that second engine links it cleanly to a cash flow focused screen built around recurring, subscription-style income rather than one-off hardware demand.
Broadcom develops semiconductors and infrastructure software, earning about US$59.4b from Semiconductor Solutions and US$29.7b from Infrastructure Software, with a market value near US$1.70t.
"Broadcom is generating substantial free cash flow, expanding its custom silicon business, strengthening its position in networking, and integrating software assets that further diversify earnings."
The key question is what happens if a relatively quiet shift in how customers adopt private cloud and AI-ready software changes the balance of that cash engine.
If that shift is what really moves the needle, the full narrative for Broadcom shows how Broadcom’s cash engine could either accelerate or stall from this point.
Amazon.com (AMZN)
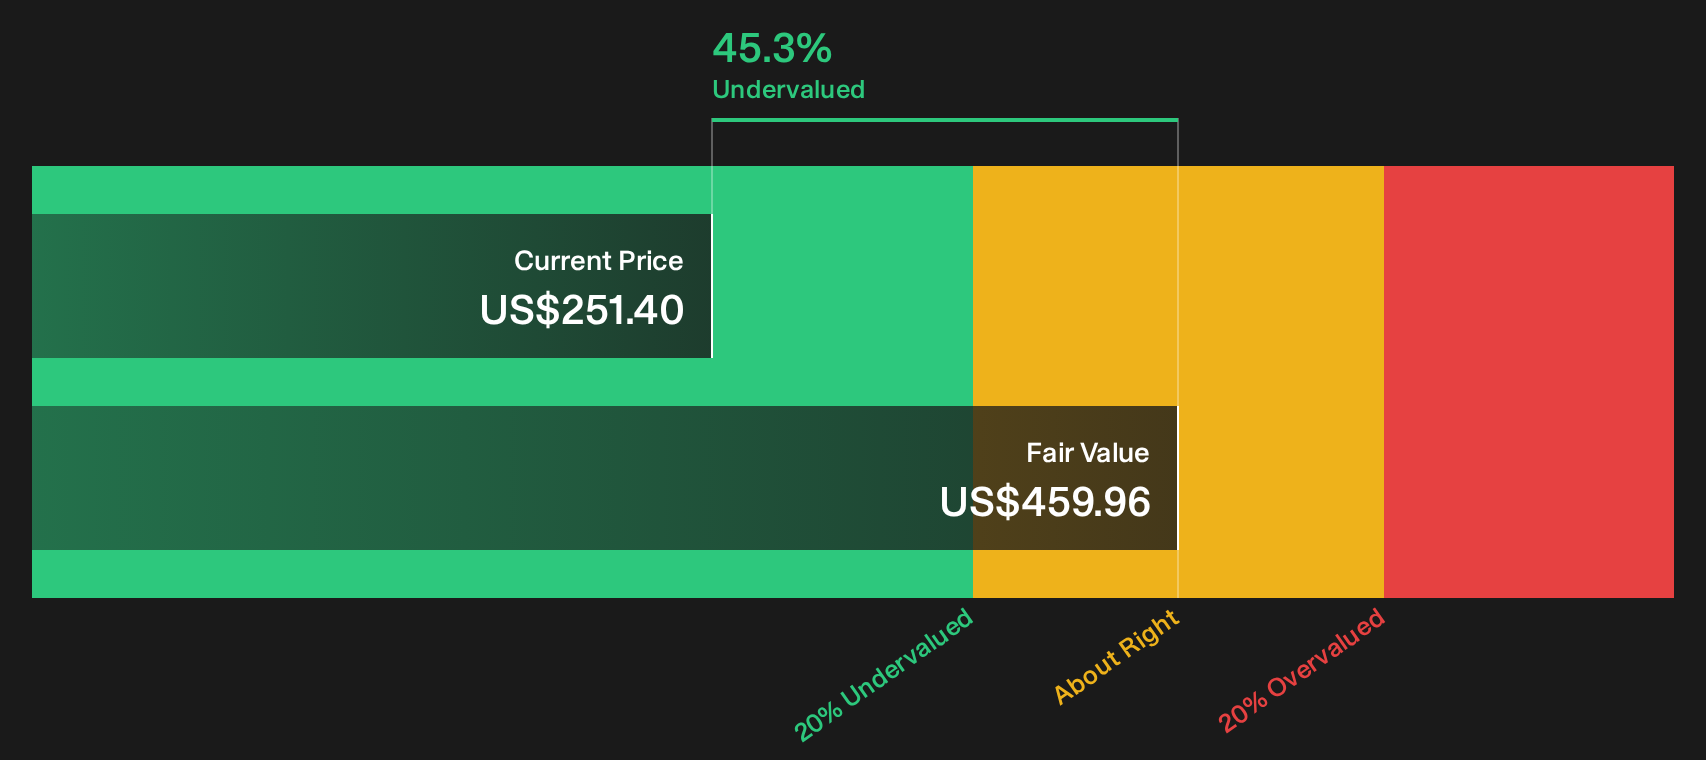
Amazon.com runs a global online shopping, media and advertising ecosystem. The AWS cloud division links it most directly to this cash flow focused screen by pairing high margin recurring services with the retail and subscription activity buyers already know.
Amazon.com generates about US$453.7b from North America, US$173.6b from International and US$148.4b from AWS, with a market value near US$2.7t.
For this screener, Amazon.com matters because AWS turns enterprise spending on compute, storage, databases and AI tools into recurring cash flows that feed long range valuation work, while the retail, advertising and Prime pieces shape how steady those inflows feel over time.
"AWS reaccelerated through 2025 with roughly 20% year-over-year growth, exiting the year with an annualized revenue base exceeding $130 billion."
This raises the question of what happens if a quiet shift in how those AI heavy workloads are funded and priced either stretches this margin story or squeezes it.
If that funding shift is what really matters, the full narrative for Amazon.com maps how Amazon.com’s cash machine could accelerate, stall, or quietly decouple from headline AWS growth.
Seeking Alternatives Before Momentum Flies?
Fresh ideas move first. Breakout stories can be spotted early while prices are still dropping or under the radar for now. Do not get caught watching. Act now.
- Catch high yield income opportunities before they are widely crowded by income hunters through the 162 dividend fortresses, which is built to spotlight resilient payouts with serious staying power.
- Track potential infrastructure momentum by scanning the 40 power grid technology and infrastructure stocks, which highlights grid technology players positioned around critical upgrade spending.
- Follow developments in AI-enabled workflows by reviewing the 127 healthcare AI stocks, featuring data-focused healthcare businesses applying algorithms to real world patient and hospital problems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com