
W. P. Carey (WPC) Stock May Be Below Fair Value On Earnings
W. P. Carey has delivered a solid 44.7% gain over the past 3 years, which puts the spotlight firmly on whether the current share price around US$63.93 is aligned with what its earnings can support. For anyone considering the stock today, the key issue is how that price squares with the income the real estate investment trust is actually generating.
- The 44.7% return over 3 years raises a straightforward question for holders and potential buyers alike: are you now paying a richer tag for each dollar of W. P. Carey earnings than before that run?
- The business model, built on rental income from a diversified portfolio of properties, can anchor the discussion on how reliable and repeatable its earnings power might be and how much investors are prepared to pay for that stream.
- Your read on W. P. Carey is one view; the desks covering it have another. See what analysts think W. P. Carey's shares could be worth.
The issue now is whether W. P. Carey's current valuation is appropriately grounded in its earnings profile or asking investors to stretch too far for that income stream.
If you want a broader benchmark for what you pay for income streams like W. P. Carey's, it can help to compare across 7 dividend fortresses.
Is W. P. Carey Still Cheap on Earnings?
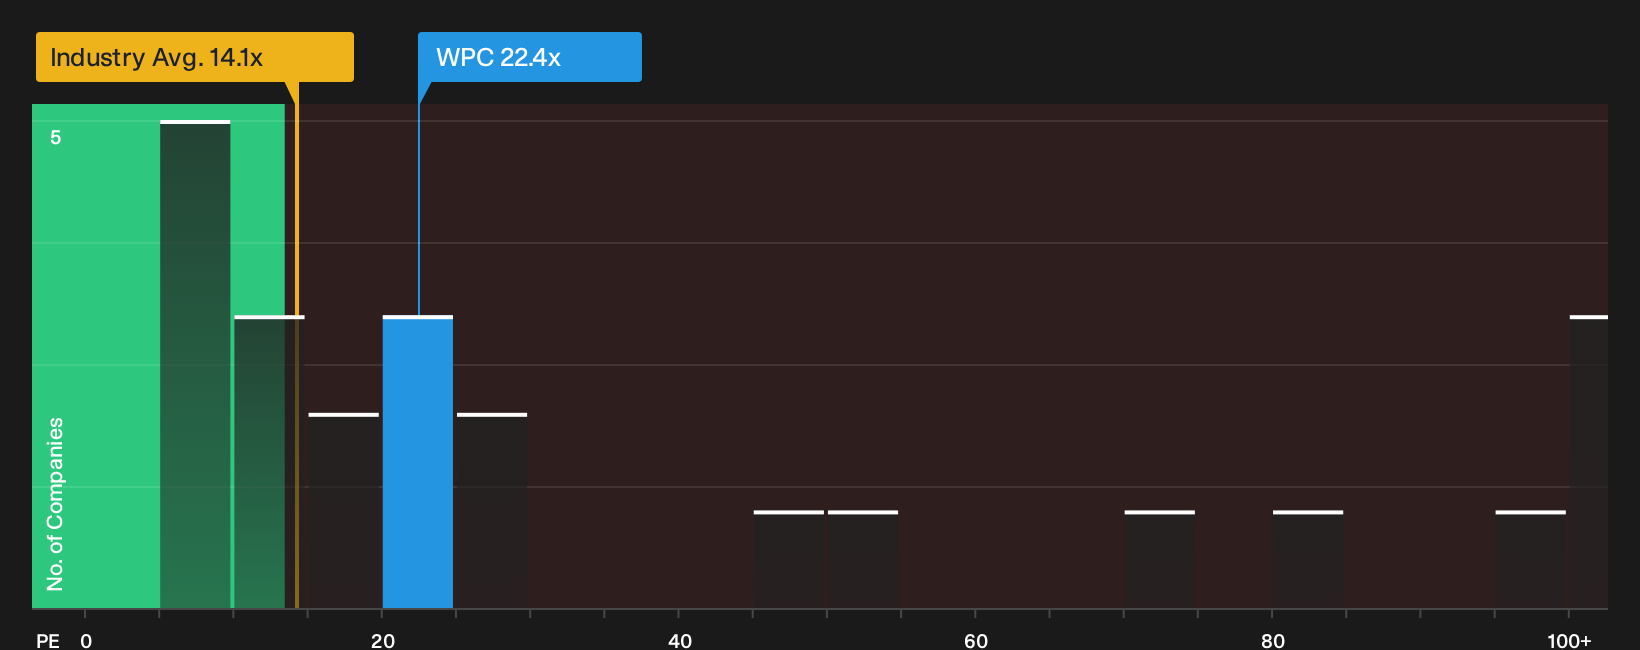
P/E is a useful lens for W. P. Carey because earnings are a central reference point for many REIT investors trying to judge what they are paying for each dollar of profit. At a current P/E of 22.4x, the stock trades meaningfully above the REITs sector average of about 14.1x, which signals a richer tag than the broader group. Against that, the peer set used for comparison sits on a far higher average multiple of 73.3x, so W. P. Carey shows up as lower priced than that specific basket of companies.
The tailored model that blends W. P. Carey specific factors such as its sector, scale and risk profile points to a higher P/E than where the shares change hands today. That gap means the current valuation screens as undervalued relative to what this framework would expect for the trust's earnings power. For anyone weighing the stock, the tension between a premium to the wider REITs sector and a discount to closer peers is worth factoring into how much you are prepared to pay for this income stream. Explore the numbers behind W. P. Carey's P/E valuation.
The W. P. Carey Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the valuation question for W. P. Carey leaves off by spelling out what would need to happen to future growth, margins and earnings for the share price to look meaningfully higher or lower than today. Each Narrative on W. P. Carey is framed as a thesis about the business that can be tracked over time, rather than a one off snapshot of estimated fair value, and these sit on Simply Wall St's Community page.
One of the top community narratives on W. P. Carey: 20% undervalued
"Current valuation implies the share price does not fully reflect the raised 2026 AFFO guidance, the prefunded investment pipeline of up to $2.1b, and the company’s shift toward long-lease industrial, warehouse and retail properties…"
Discover why this Narrative puts W. P. Carey at 20% undervalued.
For W. P. Carey, who is steering the ship really matters
Valuation only tells you what the market pays for W. P. Carey today. It does not show whether the people running it are rewarded in a way that truly lines up with your interests. See who runs W. P. Carey and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com