
Is Marvell Technology (MRVL) Expensive After Its AI Data Center Push And AT&S Deal?
Marvell Technology (MRVL) just paired fresh AI data center headlines with a cash signal, affirming a quarterly dividend of $0.06 per share alongside new 2nm optical interconnect showcases and an expanded AT&S substrate agreement.
The recent AI data center announcements and the expanded AT&S agreement have arrived alongside strong momentum in Marvell Technology’s shares, with a 30-day share price return of 21.80% and a year-to-date share price gain of 204.61%, contributing to a very large 3-year total shareholder return of 405.84%.
Spot emerging AI infrastructure momentum alongside Marvell Technology by scanning the hand picked 91 AI infrastructure stocks shaping the next leg of data center connectivity.After a 204.61% year to date surge and new AI infrastructure headlines, Marvell Technology now poses a harder question: Does the current price still leave enough potential upside to compensate for execution and cycle risk as expectations reset?
Most Popular Narrative: 94% Overvalued
According to the most followed Marvell Technology thesis, the fair value sits at $140, well below the recent $272.29 close. This puts the current debate squarely on how much optimism is already embedded.
Marvell has built something genuinely rare in semiconductors: a full-stack platform that covers custom chip design, high-speed optical interconnect, silicon photonics, and memory switching, all converging on the single biggest infrastructure build-out of the current decade.
NVIDIA's $2B investment is not a customer relationship. It is a vote of confidence from the world's most informed AI infrastructure buyer that Marvell's technology platform is the right foundation for the next generation of AI factories. Google's parallel conversations reinforce the same conclusion from a different ecosystem vector.
See why 74 investors see Marvell Technology as 94% overvalued.
Result: Fair Value of $140 (OVERVALUED)
Still, the story around Marvell Technology can crack if Amazon leans harder into Alchip for Trainium, or if hyperscaler AI capex slows more broadly.
Find out about the key risks to this Marvell Technology narrative.
Another View: SWS DCF Lens On Marvell Technology
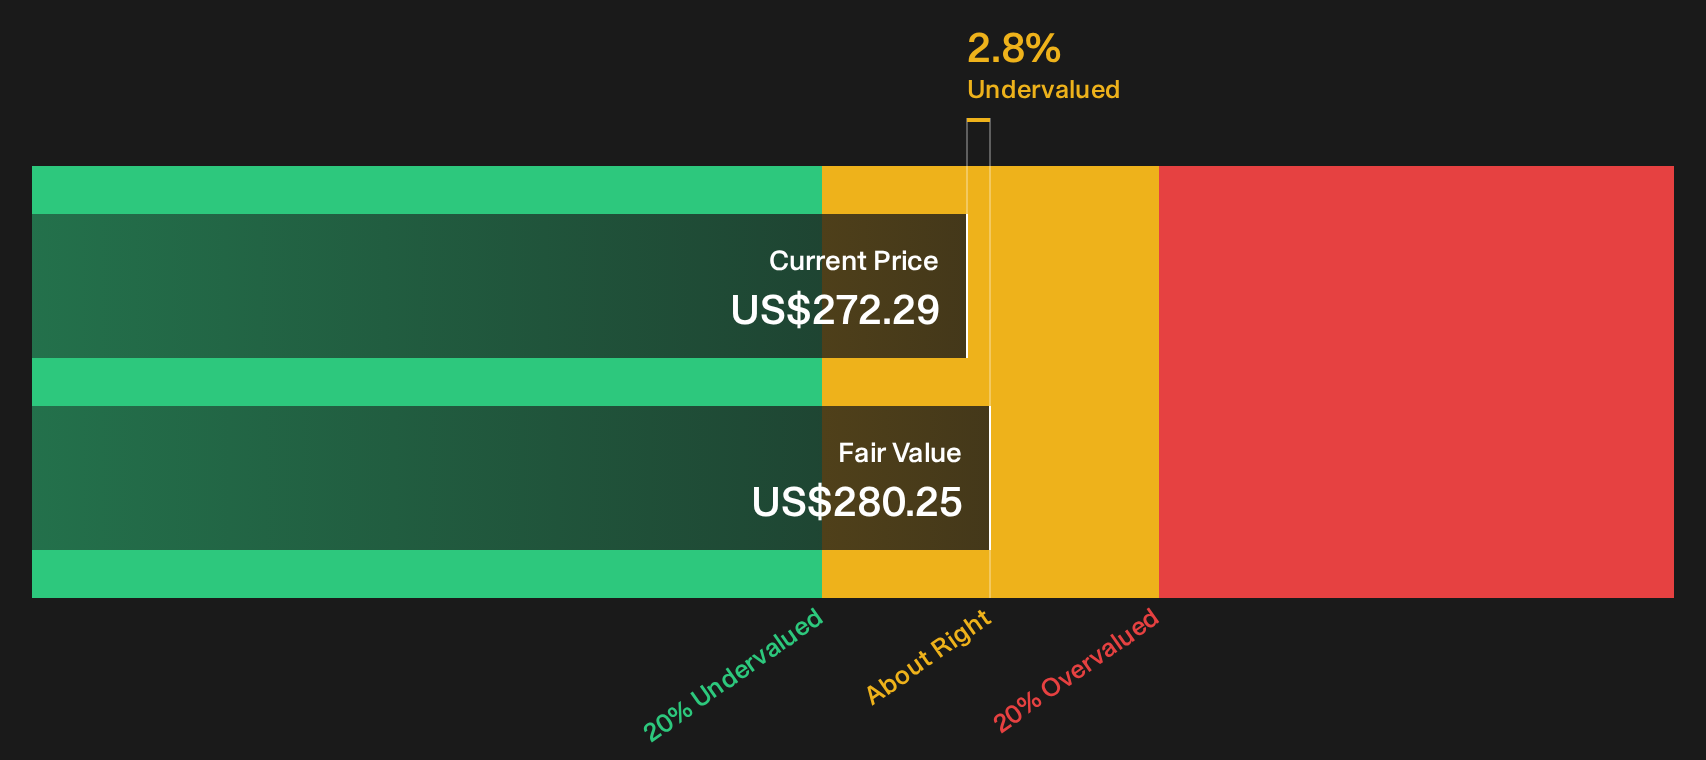
The fair value narrative around Marvell Technology looks very different when switching from user assumptions to the SWS DCF model. On this framework, MRVL at $272.29 sits roughly 2.8% below an estimated future cash flow value of $280.25, which labels the stock as slightly undervalued rather than heavily overvalued.
That gap between a $140 thesis and a $280.25 DCF output speaks to how much hinges on growth duration, margins, and discount rates. For an investor weighing those competing stories, the real question is which set of cash flow assumptions feels more realistic over the next few years.
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Marvell Technology for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 31 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
The split sentiment around Marvell Technology is clear, with elevated expectations sitting next to flagged risks and specific upside drivers that are still on the table. Act quickly, review the underlying numbers, and pressure test both sides of the argument for yourself, starting with 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Marvell Technology?
Do not stop at Marvell Technology. Use this momentum to refresh your watchlist with other targeted ideas that match your goals and risk tolerance.
- Target stability first and put resilience at the center of your watchlist with 31 resilient stocks with low risk scores.
- Hunt for quality at a discount by scanning the 31 high quality undervalued stocks that currently fit your return and risk preferences.
- Strengthen your income playbook and focus on cash payouts with a curated mix of 7 dividend fortresses designed for yield focused investors.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com