
Is Flywire (FLYW) Fully Priced On Sabrina Farmer's Board Appointment?
Flywire (FLYW) gained fresh attention after appointing Sabrina Farmer to its Board of Directors and Nominating and Corporate Governance Committee, a move that puts a seasoned technology operator closer to the company’s payment platform decisions.
Despite the boardroom upgrade, Flywire’s recent trading tells a mixed story, with the share price at $17.58 after a 7-day share price return of 1.62% but a 30-day share price return that fell 5.23%. The year-to-date share price return of 26.47% pairs with a 1-year total shareholder return of 30.51%, compared with a 3-year total shareholder return that declined 39.86% and a 5-year total shareholder return that declined 63.91%. This suggests near term momentum has improved even as long term holders have seen material value erosion.
Scan for other payment and software platforms with improving momentum and boardroom depth by checking our hand picked list of 19 high quality undiscovered gems alongside Flywire’s latest move.
Flywire appears to be a solid payments platform with global reach and fresh technical expertise joining the board. The real question is whether a business with these traits is already fully reflected in a US$17.58 share price.
Most Popular Narrative: 14% Undervalued
Against a last close of $17.58, the most followed narrative pegs Flywire’s fair value near $20.38, which suggests the market is not fully pricing in its growth and margin profile. That view leans heavily on sustained earnings expansion and improving profitability supported by a 7.2% discount rate.
Ongoing investment in proprietary technology, AI-driven automation and integration capabilities is yielding significant platform efficiencies (e.g., 25% operational cost improvements, 90% automated payment matching and 40% automated customer service), underpinning Flywire's ability to maintain or increase net margins and deliver stronger earnings leverage as scale increases.
See why 9 investors see Flywire as 14% undervalued.
Result: Fair Value of $20.38 (UNDERVALUED)
Still, Flywire’s story can change quickly if regulatory shifts hit its education clients or if rising competition in cross border payments compresses margins faster than expected.
Find out about the key risks to this Flywire narrative.
Another View On Flywire’s Valuation
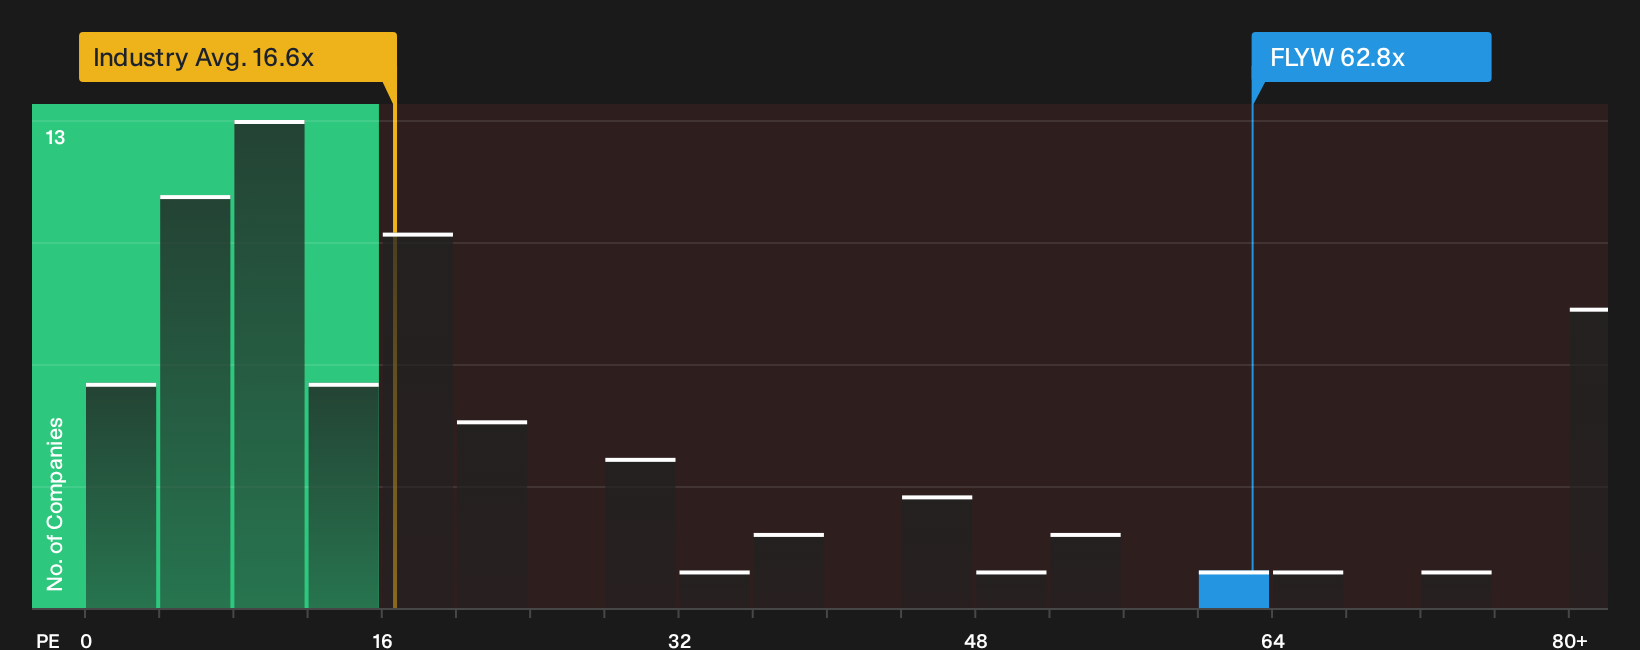
That 14% undervalued fair value near $20.38 is built on earnings forecasts and discount rates, but Flywire’s current P/E of 62.8x tells a very different story. The sector average sits at 16.6x, while a fair ratio closer to 21.3x suggests far less room if sentiment cools.
Investors weighing these conflicting signals may want to consider what the numbers imply under different earnings scenarios, then decide which interpretation appears more realistic over a full cycle.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages in the Flywire story so far. If you want a sharper view, pressure test the data, then weigh the 4 key rewards and 1 important warning sign.
Looking for more Flywire sized investment ideas?
If Flywire has your attention, do not stop at one opportunity. Use structured stock lists to widen your watchlist and avoid missing what fits your style.
- Target quality at a discount by scanning companies flagged as 31 high quality undervalued stocks that pair stronger fundamentals with prices that do not fully reflect them yet.
- Prioritize resilience and focus on stability by reviewing our 31 resilient stocks with low risk scores that screens for businesses with sturdier financial profiles and fewer red flags.
- Strengthen your income stream by focusing on 7 dividend fortresses that combine higher yields with more robust balance sheets and cash generation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com