
3 Penny Stocks With P E Under 11
Low interest rate hike odds after the recent weak US jobs report have pushed investors back toward smaller, cheaper stocks that can move quickly when the mood improves. That is where financially sound low‑priced shares come in. These are businesses trading under US$5 that still carry sensible balance sheets. This article walks through three such ideas from our financially fit penny stock universe and explains what sets each one apart.
The three stocks that follow are just a starting sample from this theme, and the full screen surfaced 3,496 more companies with equally compelling narratives that are not covered here. To identify, analyze, and focus on the highest conviction plays in this financially fit penny stock universe, head straight into the Financially Fit Penny Stocks screener.
Focus Point Holdings Berhad (KLSE:FOCUSP)
Focus Point Holdings Berhad runs a nationwide optical and eye care network in Malaysia, built around its Focus Point branded outlets and related clinics. The Optical segment produces about MYR273.9 million of its roughly MYR318.5 million in sales, with a smaller MYR41.2 million from Food and Beverage, and the stock’s market cap sits near MYR310.4 million.
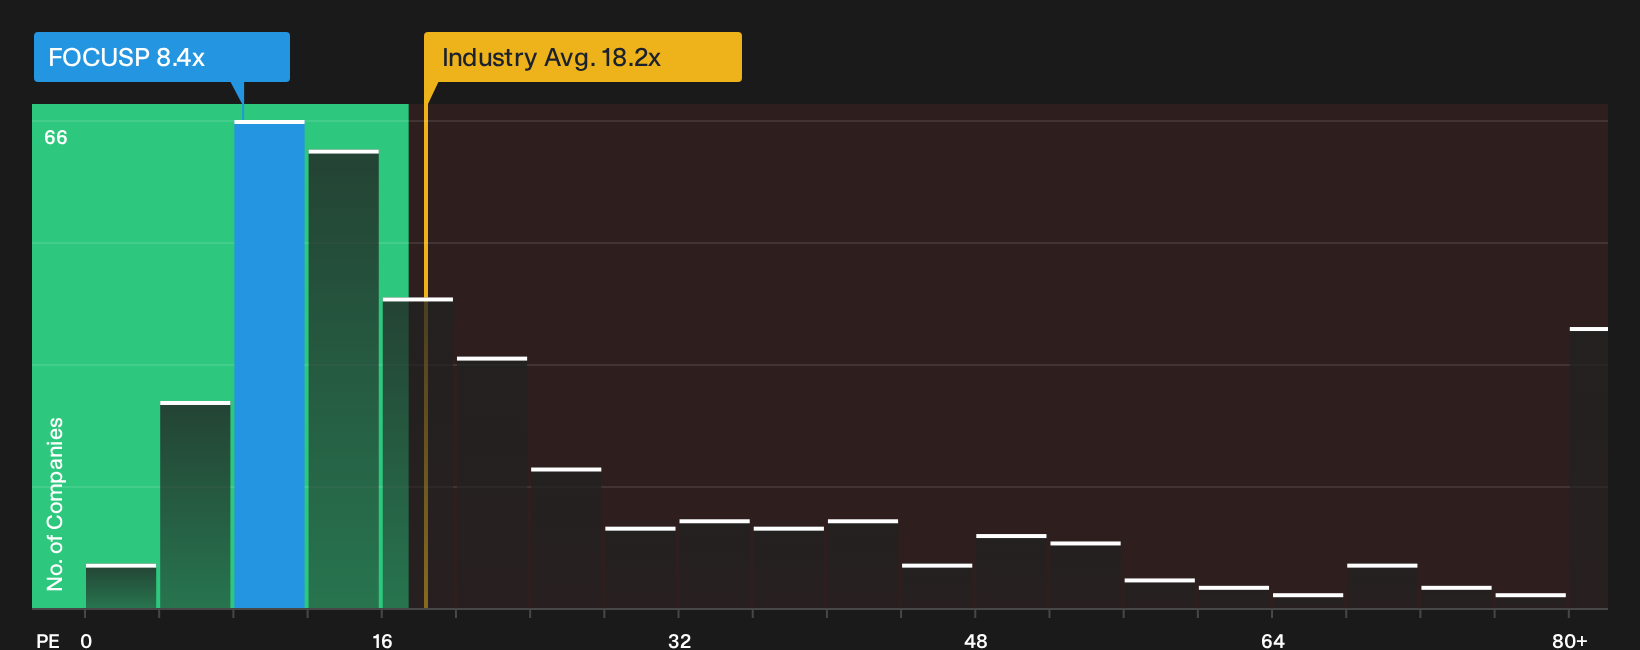
Focus Point fits the Financially Fit Penny Stocks theme through its everyday health service model, where optical retail and eye exams tend to be recurring needs rather than discretionary splurges. Solid profitability, an 8.4x P/E and ongoing dividends support that lower risk story, although the balance sheet and payout reliability still depend on how one unseen pressure plays out.
That pressure is worth unpacking through the 5 key rewards and 1 important warning sign to see whether Focus Point’s cash generation and dividend policy are starting to quietly decouple.
Angler Gaming (NGM:ANGL)
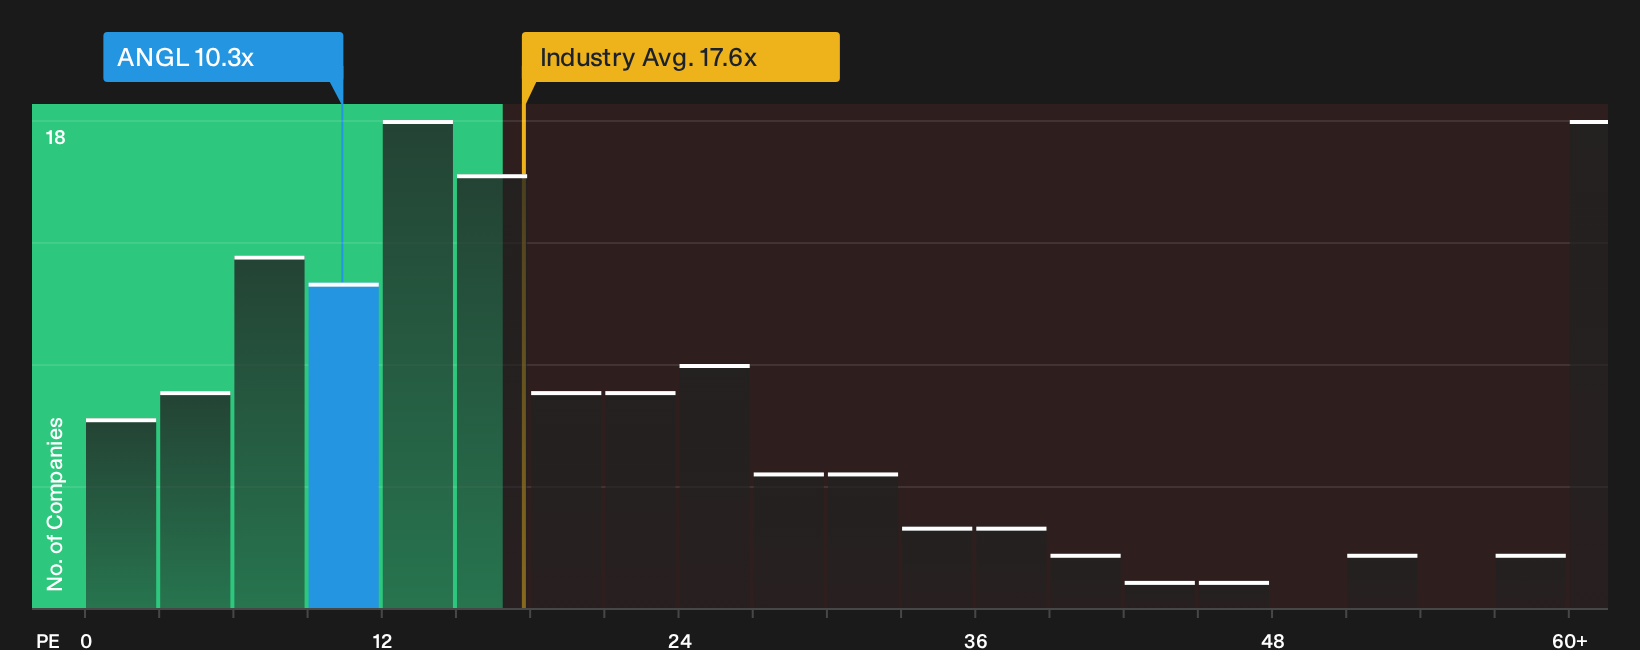
Angler Gaming invests in and supports internet casino operators, which directly ties into the Financially Fit Penny Stocks theme through its gaming investment and management focus rather than owning all operations outright. The group reports about €38 million from Casinos & Resorts and carries a market value of roughly SEK270 million.
Angler Gaming brings you exposure to online gambling platforms through a smaller, lower priced stock. Interest centres on whether the current trajectory holds if one pressure on its funding model shifts.
If that funding pressure is the real swing factor, the analysis report for Angler Gaming shows whether Angler Gaming’s casino exposure masks a cleaner story beneath the volatility.
Foresight Group Holdings (LSE:FSG)
Foresight Group Holdings manages infrastructure and private equity assets, while its venture capital and growth-capital funds back early-stage businesses that echo the Financially Fit Penny Stocks theme. Real Assets produce about £114.8 million and Private Equity about £50.1 million of revenue, with the group valued near £503.7 million.
Foresight Group Holdings gives you exposure to early-stage, growth-focused investing through a listed manager that is itself priced in penny-stock territory. This puts a lot of weight on how effectively it turns fund performance into lasting earnings power.
"The combination of public-to-private acquisitions (such as Harmony Energy Income Trust), performance-driven fund launches, and ongoing buybacks (where buybacks are outpacing share-based dilution) is set to deliver compounding EPS growth and potentially higher dividend per share increases as capital is recycled into accretive, high-ROIC strategies and return of capital accelerates."
What really shapes the payoff for investors is how one less visible pressure on future fee margins and earnings resilience ultimately plays out.
That hidden fee pressure is exactly what the full narrative for Foresight Group Holdings unpacks, showing where Foresight Group Holdings might be accelerating or stalling beneath the headline story.

Seeking Fresh Alternatives Before They Fly
Fresh breakout stories do not stay quiet for long. Momentum builds, prices move, and the clean entry points get caught quickly. Scan these under the radar ideas now and get in early.
- Spot cash rich contenders before the crowd by running the list of solid balance sheet and fundamentals (207 results) and focus your research on businesses with sturdier financial foundations.
- Track high yield opportunities with staying power using the 162 dividend fortresses and pinpoint income ideas while payouts and balance sheets still look aligned.
- Ride structural shifts in digital money early through the 17 cryptocurrency and blockchain stocks and narrow in on listed plays tied to cryptocurrency and blockchain themes.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com