
Hesai Group (HSAI) After Q2 Earnings Is The Growth Story Still A Bargain
Q2 FY26 earnings put Hesai Group in focus
Hesai Group (HSAI) moved back into the spotlight after releasing its Q2 FY26 results, reporting an 8.2% profit margin that gives investors fresh data on the LiDAR specialist’s current profitability.
The Q2 update lands after a tough stretch for Hesai Group’s equity, with the share price down 18.6% over the past month and 36.1% year to date, while the 1-year total shareholder return has declined 43.2%. However, the 3-year total shareholder return remains strongly positive at 56.9%, which hints that long term holders have still seen meaningful gains despite fading recent momentum.
Spot opportunities alongside Hesai Group by scanning a curated set of robotics and automation stocks through the 89 robotics and automation stocks.Hesai Group now trades well below both its recent levels and the analyst price target range, so the real puzzle is where fair value actually sits across that wide spread.
Most Popular Narrative: 47% Undervalued
Hesai Group last closed at $15.38, while the most followed narrative pegs fair value at about $28.97. This frames the recent share price weakness against a much higher modeled outcome built on shipment growth and margin assumptions.
The projection of 2025 LiDAR shipments reaching 1.2 million to 1.5 million units, with nearly 200,000 high-margin robotic LiDAR units, is expected to significantly boost revenue. Anticipated net revenues of RMB 3 billion to RMB 3.5 billion for 2025, driven by strong demand and mass market adoption, indicate potential growth in revenue.
See why 34 investors see Hesai Group as 47% undervalued.
Result: Fair Value of $28.97 (UNDERVALUED)
Still, Hesai Group faces significant pressure points, including heavy reliance on key customers and intense LiDAR pricing that could squeeze profitability if input costs rise.
Find out about the key risks to this Hesai Group narrative.
Another View on Hesai Group’s Valuation
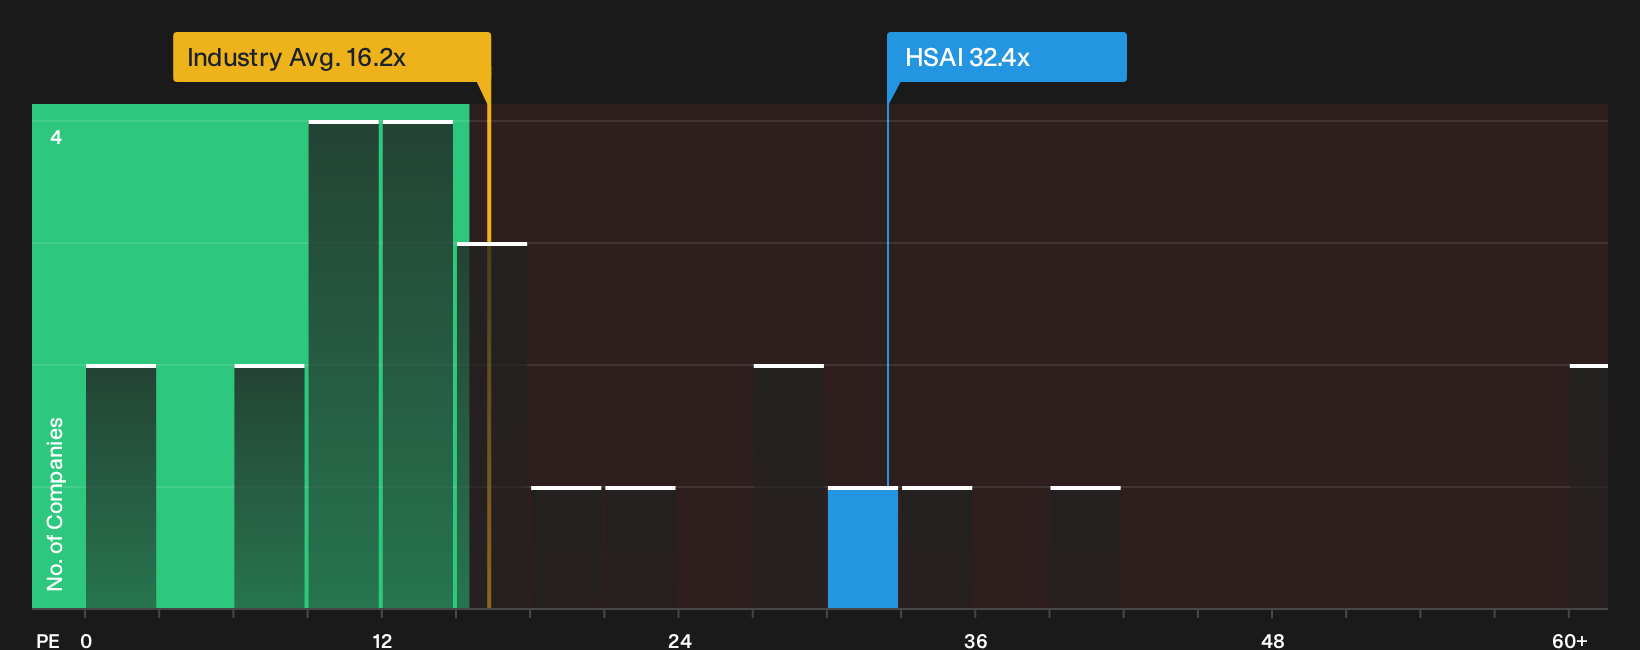
The first narrative leans heavily on future earnings and price targets. A different lens looks at what investors currently pay for each dollar of Hesai Group earnings. The stock trades on a P/E of 32.4x versus 16.2x for the US Auto Components sector and 14.2x for peers.
The Simply Wall St fair ratio is 30.1x, slightly below today’s multiple. That gap means the shares are priced above both the wider group and the modelled P/E that the market could move toward if expectations cool. The question for you is whether the growth story is strong enough to keep that premium intact.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Hesai Group can either feel paralysing or motivating, depending on how you approach them. Move quickly, stress test the assumptions yourself, then weigh up the 4 key rewards and 1 important warning sign.
Looking for more Hesai Group style ideas?
Hesai Group is only one piece of your opportunity set. Broadening your watchlist now keeps you ahead of where capital may move next.
- Target quality at a discount by scanning a fresh pool of potential bargains through the 31 high quality undervalued stocks.
- Focus on resilience first and filter for companies with sturdier finances using the list of solid balance sheet and fundamentals (25 results).
- Hunt for tomorrow's quiet winners by reviewing a curated 19 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com