
Tamboran Resources (ASX:TBN) Could Be 36% Undervalued Following Earnings And Auditor Warning
Why Tamboran Resources Earnings And Auditor Warning Matter Now
Tamboran Resources (ASX:TBN) has landed in focus after releasing full year results alongside a stark auditor warning about its ability to continue as a going concern, a combination that sharply concentrates investor attention.
The latest A$0.24 Tamboran Resources share price comes after a mixed stretch where the 30 day share price return declined 12.73%. However, the 90 day gain of 11.63% and year to date rise of 20% suggest momentum has been building over the medium term, while the 3 year total shareholder return of 74.71% contrasts with a weaker 5 year total shareholder return of 34.78%. This shows how sentiment has shifted as investors weigh narrower losses against the fresh going concern warning.
Compare Tamboran Resources with a hand picked group of energy names facing similar funding and execution tests through the 7 resilient stocks with low risk scores
Tamboran Resources trades at a steep discount to analyst targets after a recent share pullback. Is that a genuine mispricing, or a rational response to the going concern flag and ongoing losses?
Most Popular Narrative: 36% Undervalued
Tamboran Resources is framed as undervalued in the most followed narrative, with a fair value of A$0.38 against the A$0.24 last close. This comparison puts the spotlight on how quickly the Beetaloo project can move from concept to contracted gas sales.
Progress towards first gas from the Beetaloo Basin Pilot Area in the third quarter of calendar 2026, supported by an 88% complete compression facility and an APA owned pipeline in final commissioning, is expected to move Tamboran Resources from a pre revenue phase toward contracted gas sales. This is likely to affect revenue visibility and cash flow generation.
See why 4 investors see Tamboran Resources as 36% undervalued.
Result: Fair Value of A$0.38 (UNDERVALUED)
Still, the Tamboran Resources story can change quickly if project timelines slip or if fresh equity and debt funding is secured on tougher terms.
Find out about the key risks to this Tamboran Resources narrative.
Another View On Tamboran Resources Valuation
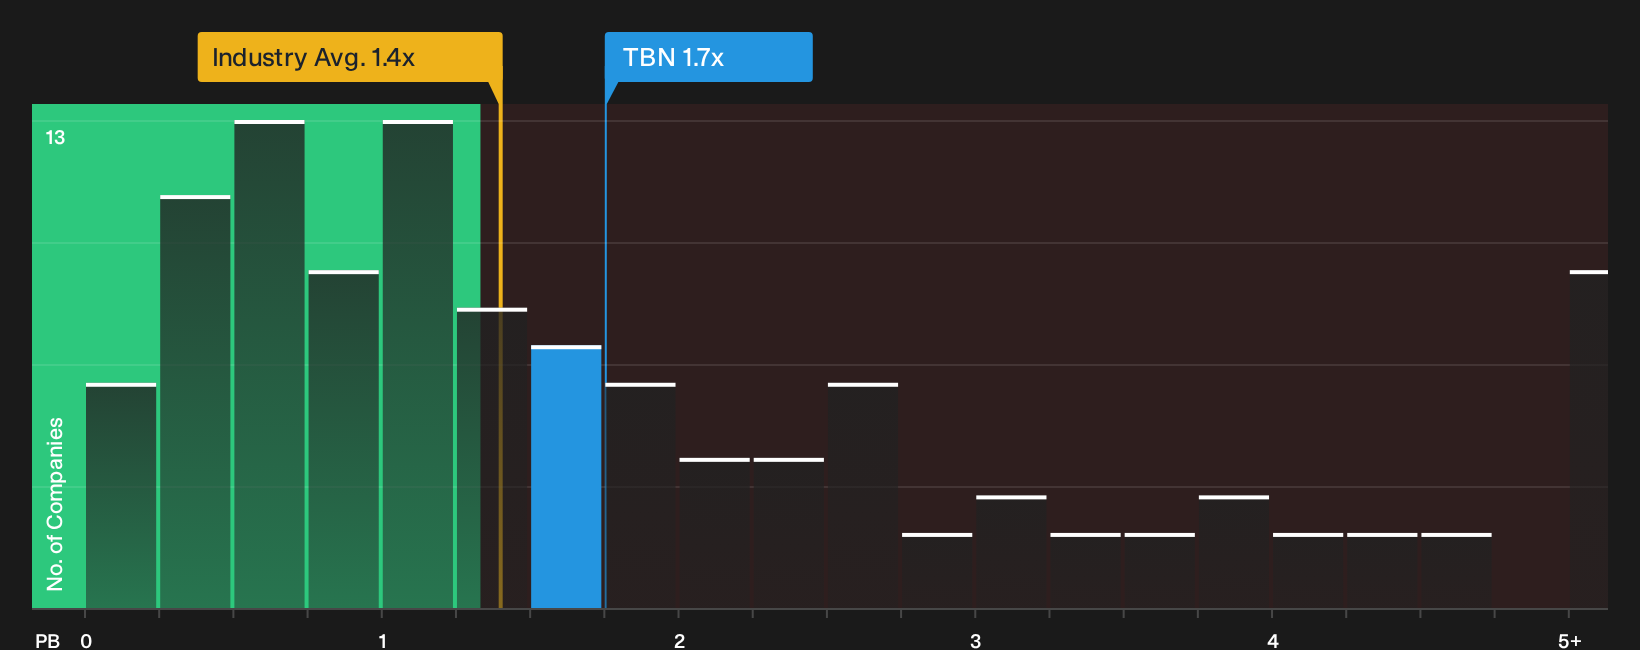
The first narrative paints Tamboran Resources as 36% undervalued against analyst fair value. A different lens tells a cooler story. On a P/B of 1.7x, the stock is described as expensive versus both the Australian Oil and Gas group at 1.4x and its peer average of 1.7x. That points to limited cushion if expectations reset.
Investors weighing these mixed signals may want to stress test their own assumptions on Beetaloo timing, funding costs and future returns before leaning on any single price target. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on Tamboran Resources can be confusing, so move quickly from reading to testing the numbers yourself. Weigh the trade off between downside risks and upside potential using the 1 key reward and 3 important warning signs
Looking For More Investment Ideas Beyond Tamboran Resources?
If Tamboran Resources has sharpened your thinking on risk and reward, do not stop there. Broader idea hunting can help you build a stronger portfolio.
- Spot potential high upside opportunities early by scanning the 11 elite penny stocks with strong financials that combine smaller market size with stronger financial footing.
- Strengthen your core holdings by reviewing the 5 high quality undervalued stocks that pair quality fundamentals with prices below estimated fair value.
- Dial back portfolio stress by assessing the 7 resilient stocks with low risk scores that focus on resilience when conditions become more challenging.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com