
Does Earnings Outlook Change The Bull Case For AZZ Stock (AZZ)?
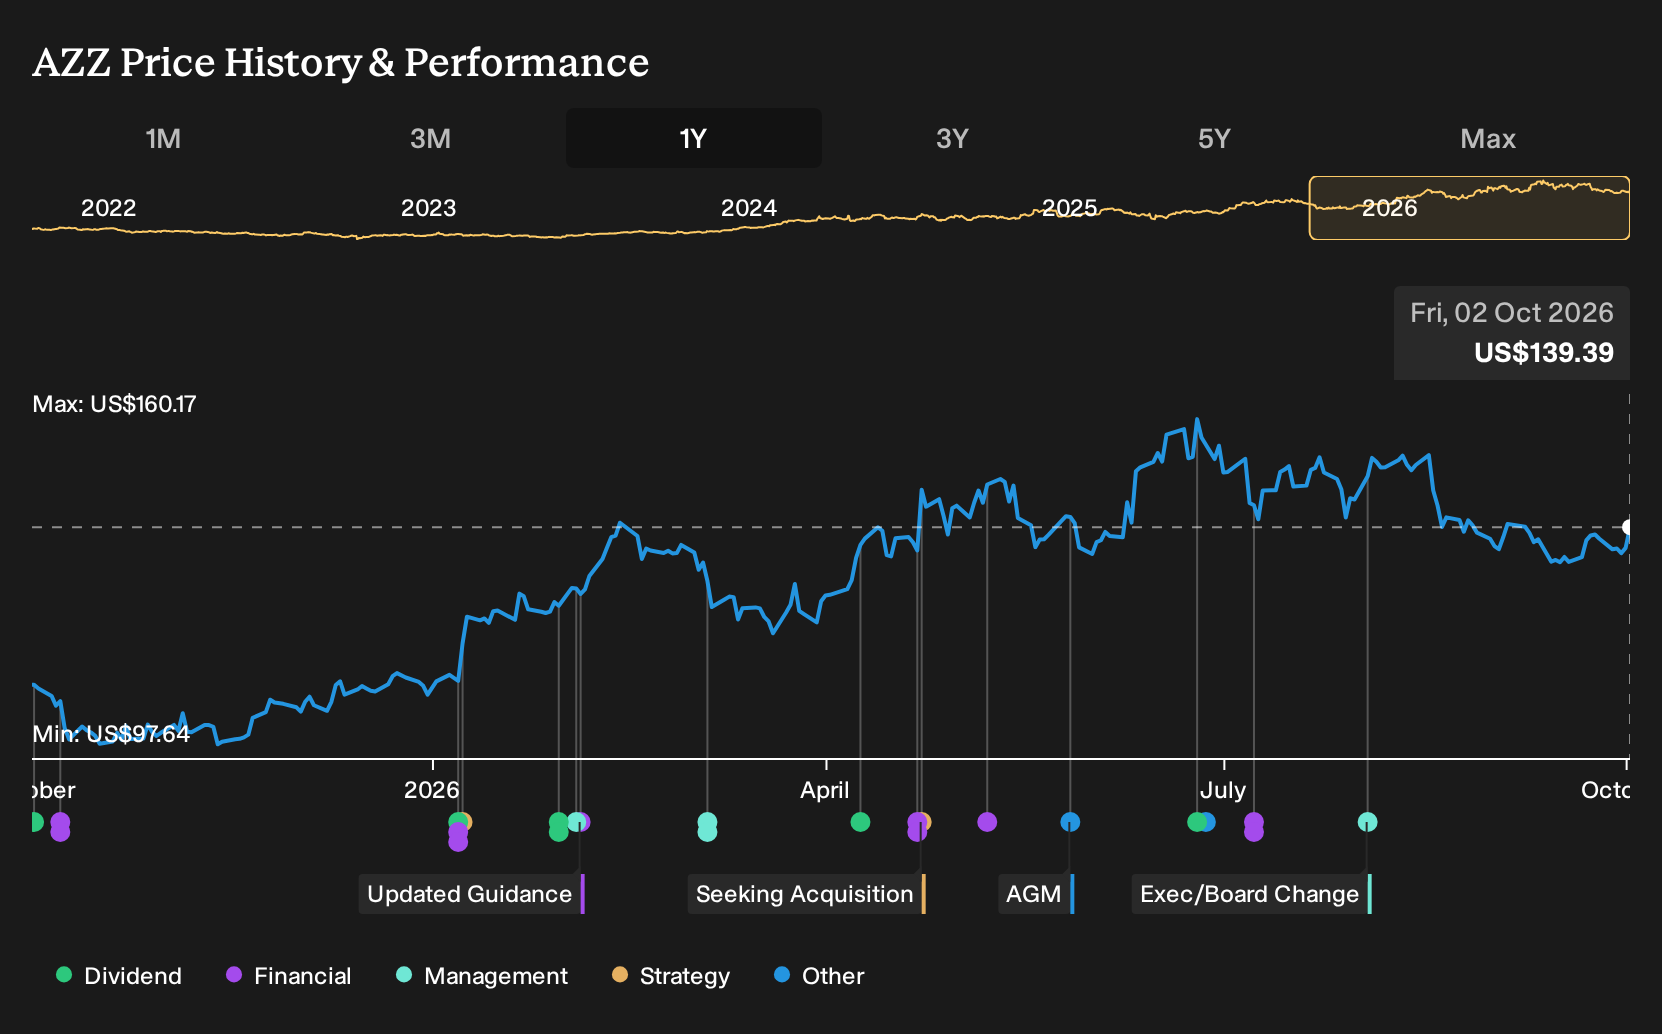
- AZZ recently experienced a share price move after analysts projected a 17.42% year-over-year EPS increase ahead of its October 13, 2026 earnings release, while its forward P/E ratio remained below the industry average.
- The combination of the expected earnings expansion and a valuation discount has drawn attention to how AZZ’s operating performance and capacity investments might influence future profitability and capital allocation.
- We will now see how AZZ's projected EPS growth and discounted forward P/E multiple could reshape the broader investment narrative around the business.
Compare AZZ's set up to a curated group of companies trading on similar earnings expectations and valuation gaps through our 31 high quality undervalued stocks.
AZZ Investment Narrative Recap
To own AZZ, you need to be comfortable with a fairly straightforward belief. The metal coatings and precoat operations keep running at solid utilization, new facilities such as the St. Louis plant move closer to full efficiency, and technology upgrades like the Digital Galvanizing System translate into steadier margins rather than surprise swings.
The immediate catalyst sits around execution when capacity ramps meet real demand. The projected 17.42% EPS lift near term focuses attention on whether lost production days from adverse weather, tariff swings, and cost pressure stay contained. If those issues resurface around earnings season, the impact on near term profitability could matter more than the headline growth rate.
There have been no fresh company announcements tied directly to this EPS revision story, which makes the existing expansion and efficiency plans the key backdrop. The Washington aluminum coil coating plant and the St. Louis greenfield facility remain central to how investors frame near term momentum and potential margin stability.
For you, the link between these projects and the current earnings excitement is execution quality. If the new lines hit expected throughput without major hiccups while material costs and competition stay manageable, the capacity build out, debt reduction focus, and technology spend give AZZ a clear set of operational levers. If delays, integration issues, or another run of weather related downtime show up, that same investment program could feel heavier in the short term.
How AZZ’s Long Range Forecast Ties Back To Today’s Setup
AZZ's narrative projects forecast revenue of US$1.9b and earnings of US$215.1 million by 2029. This assumes revenue growth of 5.2% per year and an earnings decline of US$102.2 million from current earnings of US$317.3 million.
Uncover why AZZ's fair value indicates a 16% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
One alternate angle on AZZ leans heavily on infrastructure and data center demand as a powerful catalyst. Before this EPS surprise, the most optimistic analysts already had revenue reaching about US$1.9b and earnings near US$212.9 million by 2029. That is a far richer story than consensus, and this latest earnings news could easily prompt fresh revisions.
Explore 2 other AZZ fair value estimates, including one that suggests as much as 18% upside from the current price.
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your AZZ research is our analysis highlighting 1 key reward and 1 important warning sign that could impact your investment decision.
- See our latest analysis for AZZ. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate AZZ's overall financial health at a glance.
Looking For More Ideas Beyond AZZ?
Once you have formed a view on AZZ, it can help to compare it with other opportunities that match different risk, income, and quality profiles using the Simply Wall St Screener.
- For investors who care most about balance sheet strength and solid fundamentals, the list of solid balance sheet and fundamentals (25 results) can highlight companies where financial resilience is a key feature.
- If you want ideas that aim to reduce downside risk, the 31 resilient stocks with low risk scores can surface businesses with more measured risk profiles according to Simply Wall St's scoring.
- When you are hunting for less followed opportunities with stronger fundamentals, the 19 high quality undiscovered gems can point you toward companies that may not yet be widely followed by the market.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com