
What Downer EDI Shares Buy Back Update Means For Shareholders
- Downer EDI has updated investors on its on market share buy back, reporting 7,778,445 shares repurchased before 29 September 2026 and a further 611,282 shares bought on that day, against a maximum target of 21,015,692 shares.
- The scale of the repurchases reduces the share count and tightens ownership, which can lift earnings per share and underlines management’s confidence in the current valuation and capital allocation priorities.
- We will now see how Downer EDI’s investment narrative is affected by this sizeable on market buy back and shrinking share base.
Scan how other companies are using buybacks and disciplined capital returns by checking out our hand picked list of 5 high quality undervalued stocks.
Downer EDI Investment Narrative Recap
To stay invested in Downer EDI, you need to believe its simplification into Transport, Energy & Utilities, and Facilities continues to support steady contract demand from government and infrastructure clients. The key short term swing factor is how efficiently those contracts are delivered, given tight margins and ongoing cost and labour pressures.
The new on market buy back does not materially change that operational story. It may help earnings per share optics as the share count falls, but the bigger risk still sits with execution of the transformation program and timing of new work, especially where state spending or New Zealand infrastructure activity softens.
The current buy back program, which has a maximum of 21,015,692 shares and has already retired over 8.3 million, sits alongside the broader reset of Downer EDI’s portfolio. Management has been cutting complexity, focusing on higher quality contracts and tightening risk controls across the three core divisions.
For you as a shareholder, the key link is between this capital return and the operational catalysts already in motion. Cost out initiatives of A$180 million, with another A$20 million targeted, higher quality earnings, and exposure to areas like transitional energy and government outsourcing all place greater emphasis on execution quality, contract discipline and future work in hand rather than on the buy back itself.
Downer EDI's current analyst narrative points to forecast revenue of A$10.9b and earnings of A$359.0 million by 2029, built on an assumed 4.0% yearly revenue growth rate and a lift in profit margins from 2.2% today. That earnings target implies an increase of about A$142.5 million from current earnings of A$216.5 million.
Discover why Downer EDI's fair value indicates a 16% potential upside to its current price, which could close sooner than many investors expect.
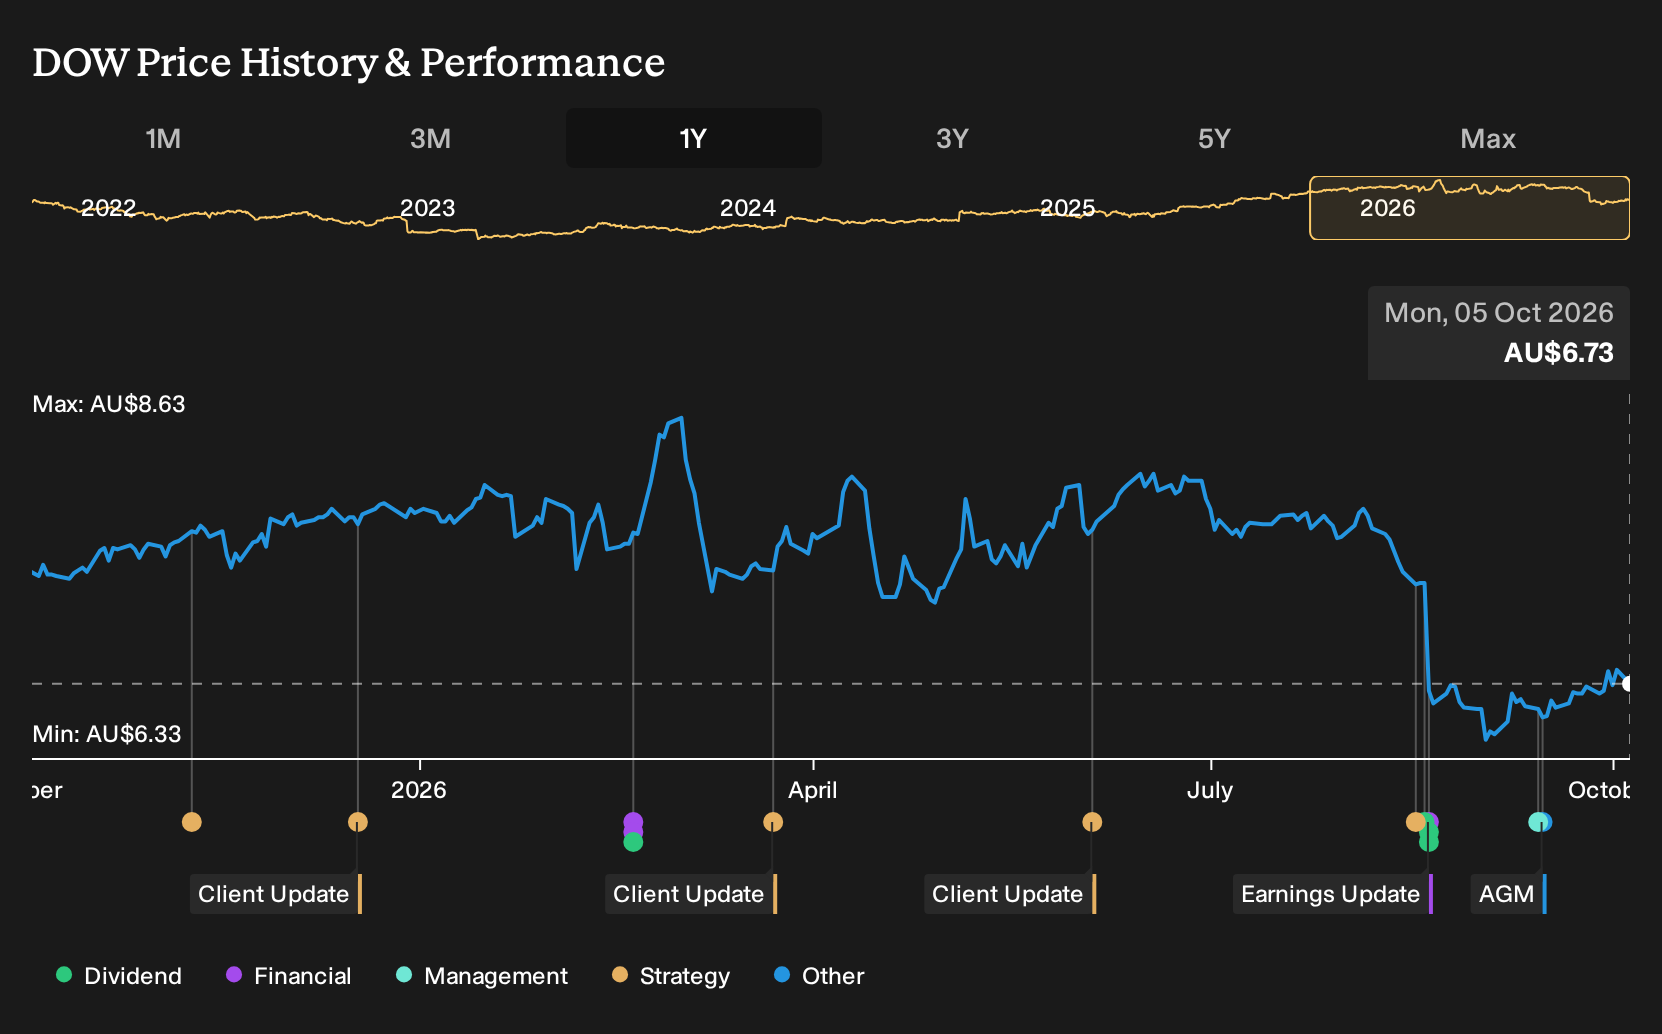
Exploring Other Perspectives
Some of the most optimistic analysts frame the on market buy back as a potential accelerator for a different story. They already expected Downer EDI to reach A$11.5b of revenue and A$407.3 million of earnings by 2029, versus consensus at A$10.9b and A$359.0 million, before this update. You can compare those viewpoints and decide which assumptions feel closer to your own, bearing in mind that the new buy back details may shift both narratives from here.
Explore another Downer EDI fair value estimate, including one that suggests the potential for as much as 260% upside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Downer EDI research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Downer EDI. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Downer EDI's overall financial health at a glance.
Looking For More Ideas Beyond Downer EDI?
If you want to stress test your thesis on Downer EDI, it helps to set it against a wider watchlist of potential opportunities. The Simply Wall St Screener lets you line up companies with very different income profiles, balance sheets and risk levels so you can see where this stock really fits in your broader portfolio.
- If you are hunting for underappreciated quality with room for a re rating, scan our 5 high quality undervalued stocks and see which businesses combine strong fundamentals with discounted prices.
- For investors who prefer resilience and financial strength, start with a list of solid balance sheet and fundamentals (12 results) that can help anchor your portfolio through different market conditions.
- When you want growth potential that is not already crowded, filter for 15 high quality undiscovered gems that pair sound metrics with lower market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com