
Is Panasonic Holdings (TSE:6752) Fairly Valued As It Returns To Canada With Premium TVs?
Panasonic Holdings (TSE:6752) is back in the Canadian TV market with new Z85C OLED and W90C QD-Mini LED models aimed at living rooms built around movies, sports, streaming and gaming.
Over the past year Panasonic Holdings has seen strong momentum, with a year to date share price return of 127.38% and a 1-year total shareholder return of 176.92%. The latest product launch arrives against this backdrop of already very large 3-year and 5-year total gains.
Scan other consumer hardware plays showing strong momentum and premium product focus with our hand picked list of 75 high quality undiscovered gems for a broader context around Panasonic Holdings' latest TV move.
Panasonic Holdings has already delivered very large multi year gains, and the Canadian TV return and premium lineup keep adding new story lines. Is the current share price still leaving meaningful upside on the table, or has most of it already played out?
Most Popular Narrative: 5% Undervalued
On the most followed view, Panasonic Holdings screens as modestly undervalued, with a fair value estimate of ¥4,974 against a last close of ¥4,726, which puts the new TV push in the context of a broader battery and energy story that is doing much of the valuation heavy lifting.
Demand for industrial energy storage systems is accelerating beyond initial expectations due to large-scale data center investment driven by generative AI adoption, which is likely to support revenue growth and improve recurring earnings quality in the Energy segment.
Despite a near-term EV slowdown in North America from policy headwinds (IRA tax credit termination, tariffs), Panasonic's locally produced, IRA-compliant battery cells and new high-capacity cell technology are sustaining strong customer demand, positioning the company for volume growth and higher net margins as electrification resumes its long-term trend.
See why 24 investors see Panasonic Holdings as 5% undervalued.
Result: Fair Value of ¥4,973.69 (UNDERVALUED)
Still, the analyst story around Panasonic Holdings can break if EV demand stays weak for longer than expected or if restructuring and cost cuts continue to stall.
Find out about the key risks to this Panasonic Holdings narrative.
Another View: Panasonic Holdings Through The P/E Lens
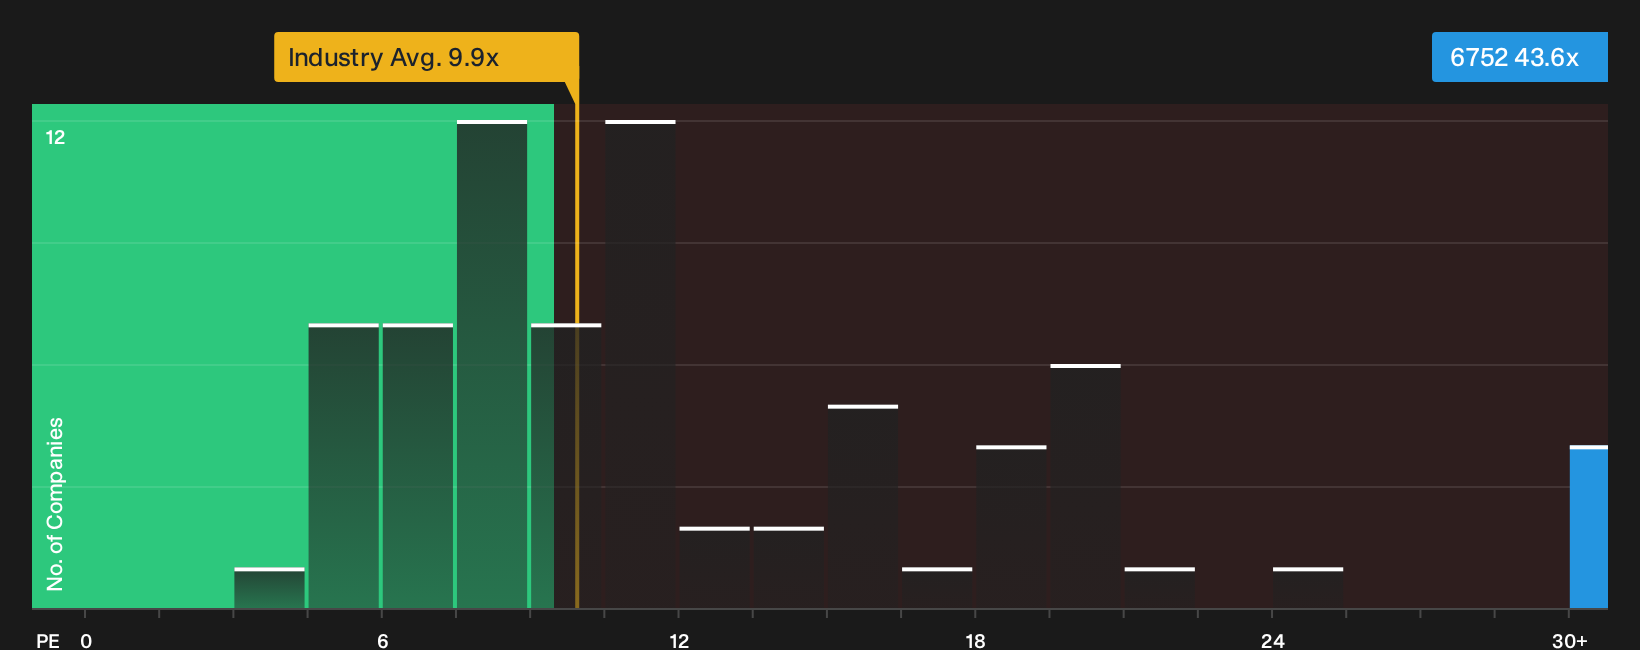
On a simple earnings multiple, Panasonic Holdings looks far less relaxed than the 5% undervalued story suggests. The shares trade on a P/E of 43.6x versus about 9.9x for the JP Consumer Durables group and 19.9x across close peers, while the fair ratio sits nearer 33.1x.
That gap points to meaningful valuation risk if sentiment cools and the market leans closer to that fair ratio, rather than the current premium multiple investors are paying today. Is the present price rewarding, or just pricing in too much of the battery and AI infrastructure narrative already?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed views so far on Panasonic Holdings and its recent surge. If you want to move quickly and test the bullish and cautious arguments against your own framework, start by weighing its 2 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Panasonic Holdings?
If Panasonic Holdings has your attention, do not stop there. Extend your watchlist with a few focused idea sets that match specific goals and risk comfort.
Shortlist income pillars that aim to keep paying you while you wait by combing through 22 dividend fortresses and see which payouts align with your cash flow needs.
Target resilient performers that prioritise financial strength by scanning the list of solid balance sheet and fundamentals (23 results) and filter for balance sheets that look built to endure rough patches.
Hunt for potential future leaders before they become crowded trades by working through the 75 high quality undiscovered gems and spot stories the broader market may be missing.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com