
What Did The Market Misjudge About JK Lakshmi Cement?
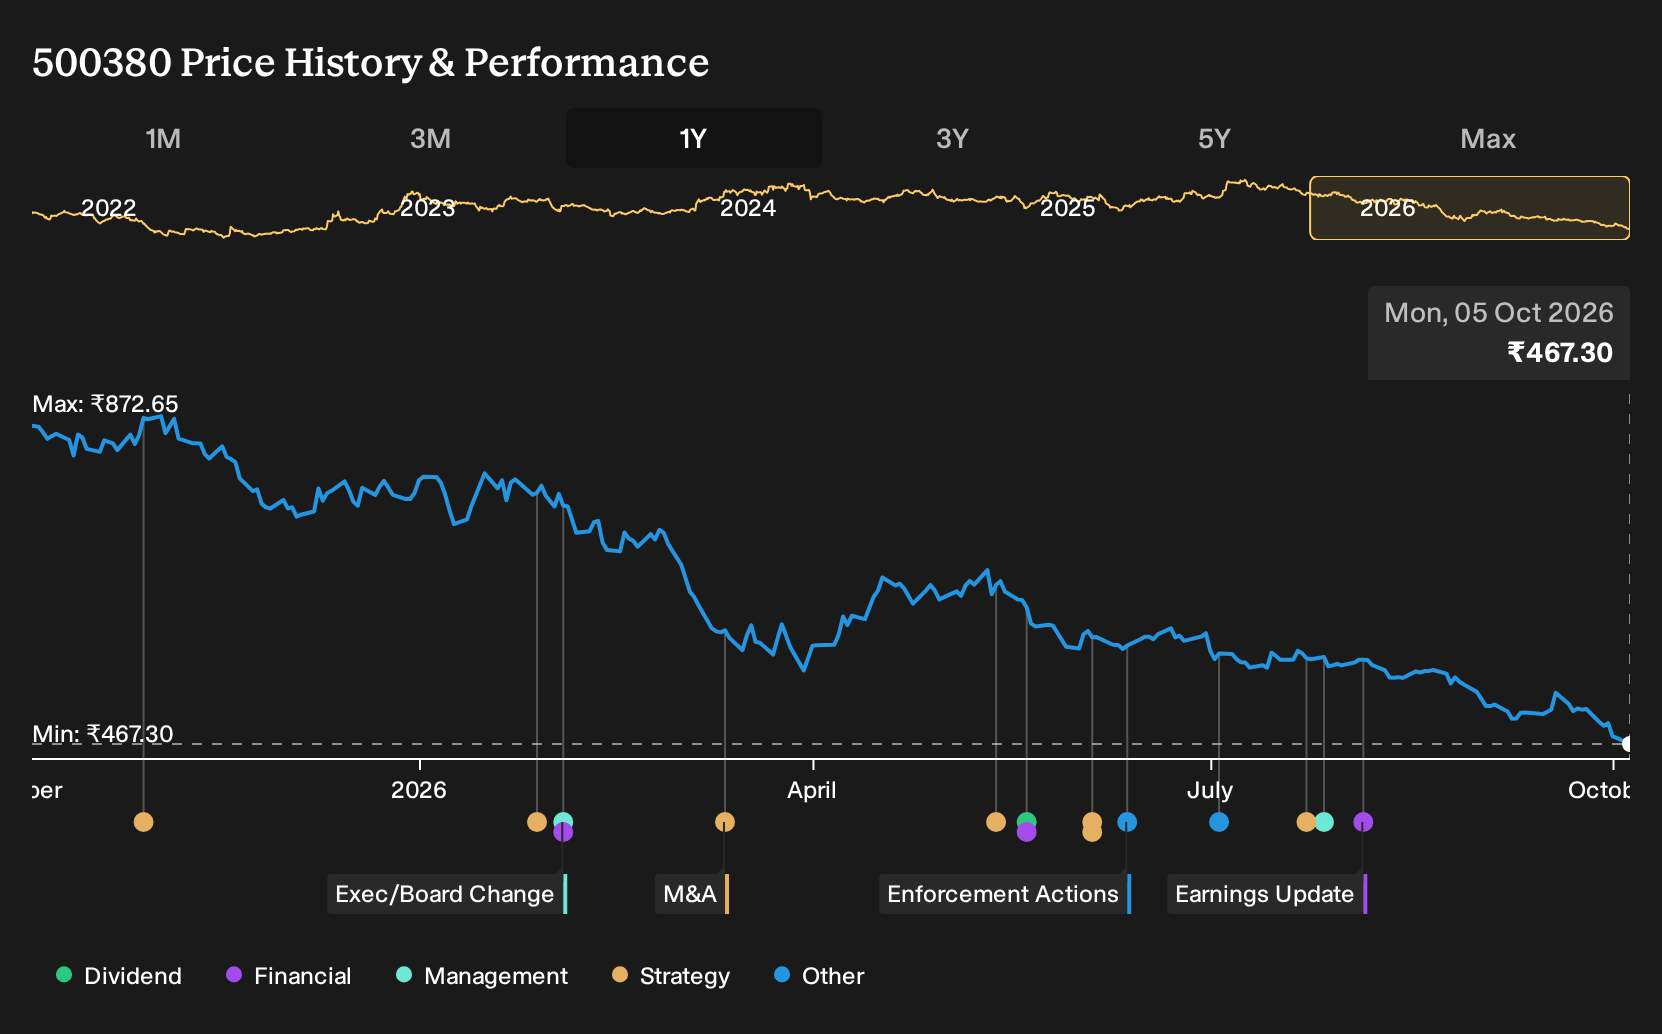
Q1 2027 results for JK Lakshmi Cement showed higher revenue alongside a thinner net margin compared with Q1 2026, a mix that rarely reassures investors by itself. For JK Lakshmi Cement shareholders, the loss over the past year was 45.0%, including dividends. If you had chosen to buy on 5 October 2025, that is the experience you would be weighing today. The real question is whether margin pressure is a temporary setback or a sign of something more persistent.
Narratives are how investors here put a case on the record, with explicit assumptions about revenue, margins and the multiple. Those assumptions imply an estimated Fair Value.
If the move has made JK Lakshmi Cement harder to judge, start where the gap is still open and scan 187 high quality undervalued stocks.
The Two Stories JK Lakshmi Cement Investors Were Weighing
The shares cost ₹862 at the start of the period, which left JK Lakshmi Cement holders choosing between two very different stories about what came next.
On the bullish side, the Fair Value sat at ₹962. This was built on expectations that multi year capacity expansions in East and Northeast India would capture infrastructure led cement demand and support steadier revenue and profit growth.
The bearish view put Fair Value at ₹685. This focused on rising environmental and royalty costs, especially at the Northeast project, as a potential threat to net margins and future cash flows.
What The Results Changed For JK Lakshmi Cement
The Q1 2027 print gave JK Lakshmi Cement investors a clean test of both stories. Top line reached ₹19,047.8m against ₹17,409.3m a year earlier, which supported the expansion driven bullish case. Net income slipped to ₹1,080.2m from ₹1,501.7m and net margin moved from 8.6% to 5.7%, which backed the cautious, cost focused argument. The evidence cut both ways.
The episode turned on one assumption. You would check whether extra volume and capacity at a business like JK Lakshmi Cement are showing up in a higher net margin, not just higher sales. Any story that skips that test might be priced more conservatively.
What JK Lakshmi Cement's Fall Asks You To Believe
JK Lakshmi Cement trades at ₹467 today, with this Narrative’s Fair Value sitting above that level. The argument leans on volume growth in underpenetrated regions and a push toward higher value cement mix.
You would need to believe renewable power use and efficiency gains can offset regulatory, competition and sustainability risks for the fall to look like an opportunity instead of a warning.
"Efficiency gains through renewable energy, AI-driven manufacturing, and resource security are set to structurally boost margins and de-risk capacity expansion."
That disagreement has a full argument behind it. → Uncover the higher Fair Value this Narrative argues for
Where Could You Get There Earlier?
Passing on this one could have spared you a loss. Where might you find the opposite surprise? Start looking for companies whose prices leave room for a better outcome than investors expect. These three trade below our estimated value.
- Company 1 - 47% below our estimate - supplies hardware agnostic oncology planning software as hospitals adopt AI supported treatment workflows.
- Company 2 - 25% below our estimate - runs a distributed, tech enabled legal platform attracting partners seeking higher fee shares.
- Company 3 - 27% below our estimate - scales automated in house supplement manufacturing as distributors expand everyday fitness product access.
That is three of the list. See every one of the 207 solid balance sheet companies →
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com