
Exploring 3 Undervalued Small Caps With Insider Buying Across Regions
The United States market has remained flat over the past week but has experienced a 12% rise in the last year, with earnings projected to grow by 18% annually. In this context, identifying small-cap stocks that are potentially undervalued and have insider buying can be an intriguing strategy for investors looking to capitalize on future growth opportunities.
Top 10 Undervalued Small Caps With Insider Buying In The United States
| Name | PE | PS | Discount to Fair Value | Value Rating |
|---|---|---|---|---|
| Regional Management | 6.3x | 0.5x | 35.58% | ★★★★★☆ |
| Financial Institutions | 9.7x | 3.2x | 22.99% | ★★★★★☆ |
| Enovis | NA | 0.4x | 45.19% | ★★★★★☆ |
| Surgery Partners | NA | 0.5x | 27.79% | ★★★★★☆ |
| German American Bancorp | 13.1x | 4.9x | 28.05% | ★★★☆☆☆ |
| Bank of Marin Bancorp | NA | 7.3x | 31.51% | ★★★☆☆☆ |
| Five Star Bancorp | 14.9x | 6.4x | 46.20% | ★★★☆☆☆ |
| Franklin Financial Services | 11.5x | 3.1x | -40.26% | ★★★☆☆☆ |
| Shore Bancshares | 11.6x | 3.3x | 36.99% | ★★★☆☆☆ |
| New Peoples Bankshares | 9.5x | 2.6x | 10.82% | ★★★☆☆☆ |
We're going to check out a few of the best picks from our screener tool.
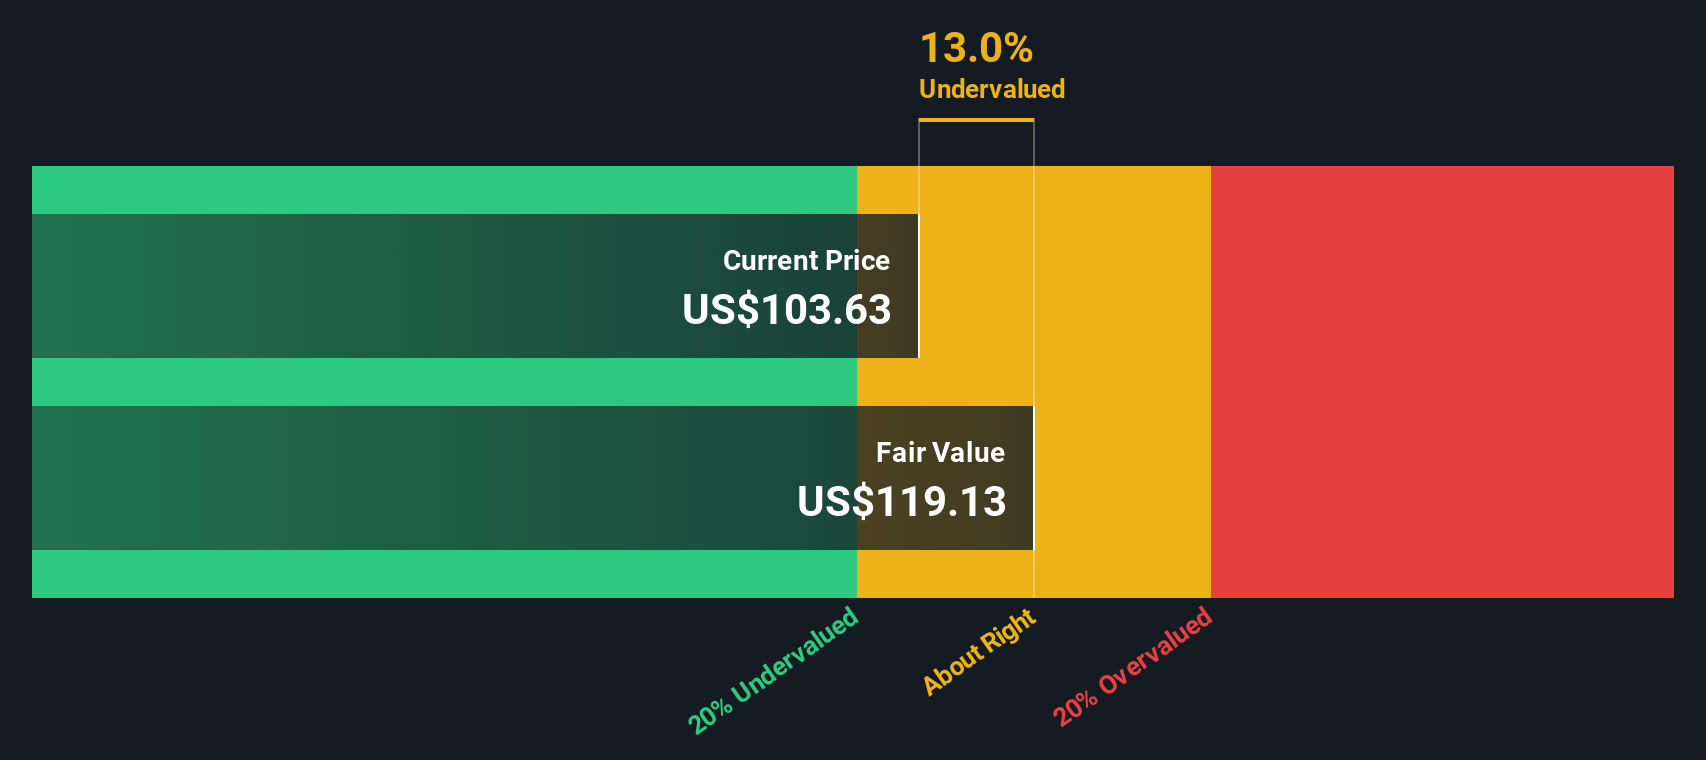
Coastal Financial (CCB)
Simply Wall St Value Rating: ★★★★☆☆
Overview: Coastal Financial operates through its CCBX, Community Bank, and Treasury & Administration segments with a market cap of $0.60 billion.
Operations: CCBX is the largest revenue contributor with $248.41 million, followed by Community Bank at $95.80 million and Treasury & Administration at $17.81 million. The gross profit margin consistently stands at 100%, indicating no cost of goods sold was reported across all periods provided. Operating expenses are primarily driven by general and administrative costs, which reached approximately $153.95 million in the latest period ending June 2026, significantly impacting net income margins that have shown variability over time, recently turning negative to -1.06%.
PE: -159.5x
Coastal Financial, a smaller player in the U.S. market, faces challenges with recent legal issues and a significant second-quarter loss of US$42.1 million due to credit expenses. Despite this, insider confidence is evident as Steven Hovde purchased 15,000 shares for US$658,250 in early 2026. The company is poised for potential growth with earnings projected to increase by over 100% annually and strategic partnerships like Pliant's U.S. launch enhancing its market presence.
- Unlock comprehensive insights into our analysis of Coastal Financial stock in this valuation report.
Examine Coastal Financial's past performance report to understand how it has performed in the past.
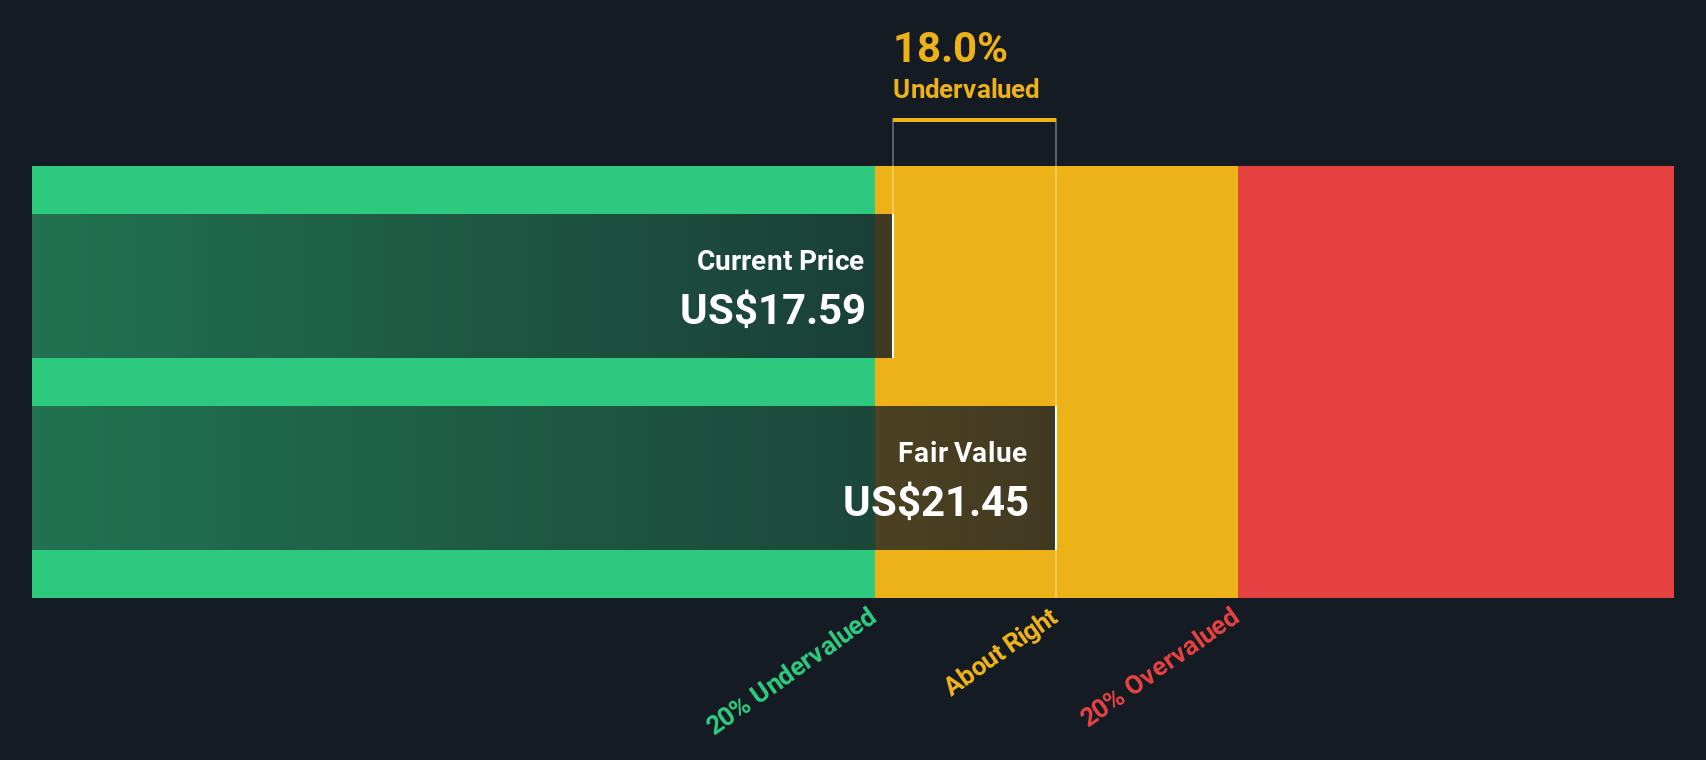
Northpointe Bancshares (NPB)
Simply Wall St Value Rating: ★★★★★★
Overview: Northpointe Bancshares operates primarily in retail banking and mortgage warehouse services, with a market cap of $1.25 billion.
Operations: Retail Banking and Mortgage Warehouse are the primary revenue streams, contributing $165.05 million and $92.20 million respectively. The company consistently achieves a gross profit margin of 100%, with a notable increase in net income margin from 5.32% in December 2022 to 31.69% by October 2026, indicating improved profitability over this period. Operating expenses, primarily driven by general and administrative costs, have shown an upward trend alongside revenue growth.
PE: 6.5x
Northpointe Bancshares, with its recent leadership changes and consistent earnings growth, presents an interesting case for investors. The company reported a net income of US$21.75 million in Q2 2026, up from US$20.34 million the previous year, alongside a net interest income increase to US$42.42 million. Insider confidence is evident as Charles Williams purchased 85,000 shares valued at approximately US$1.4 million in early 2026, indicating potential optimism about future prospects despite low bad loan allowances at 11%.
- Dive into the specifics of Northpointe Bancshares here with our thorough valuation report.
Understand Northpointe Bancshares' track record by examining our Past report.
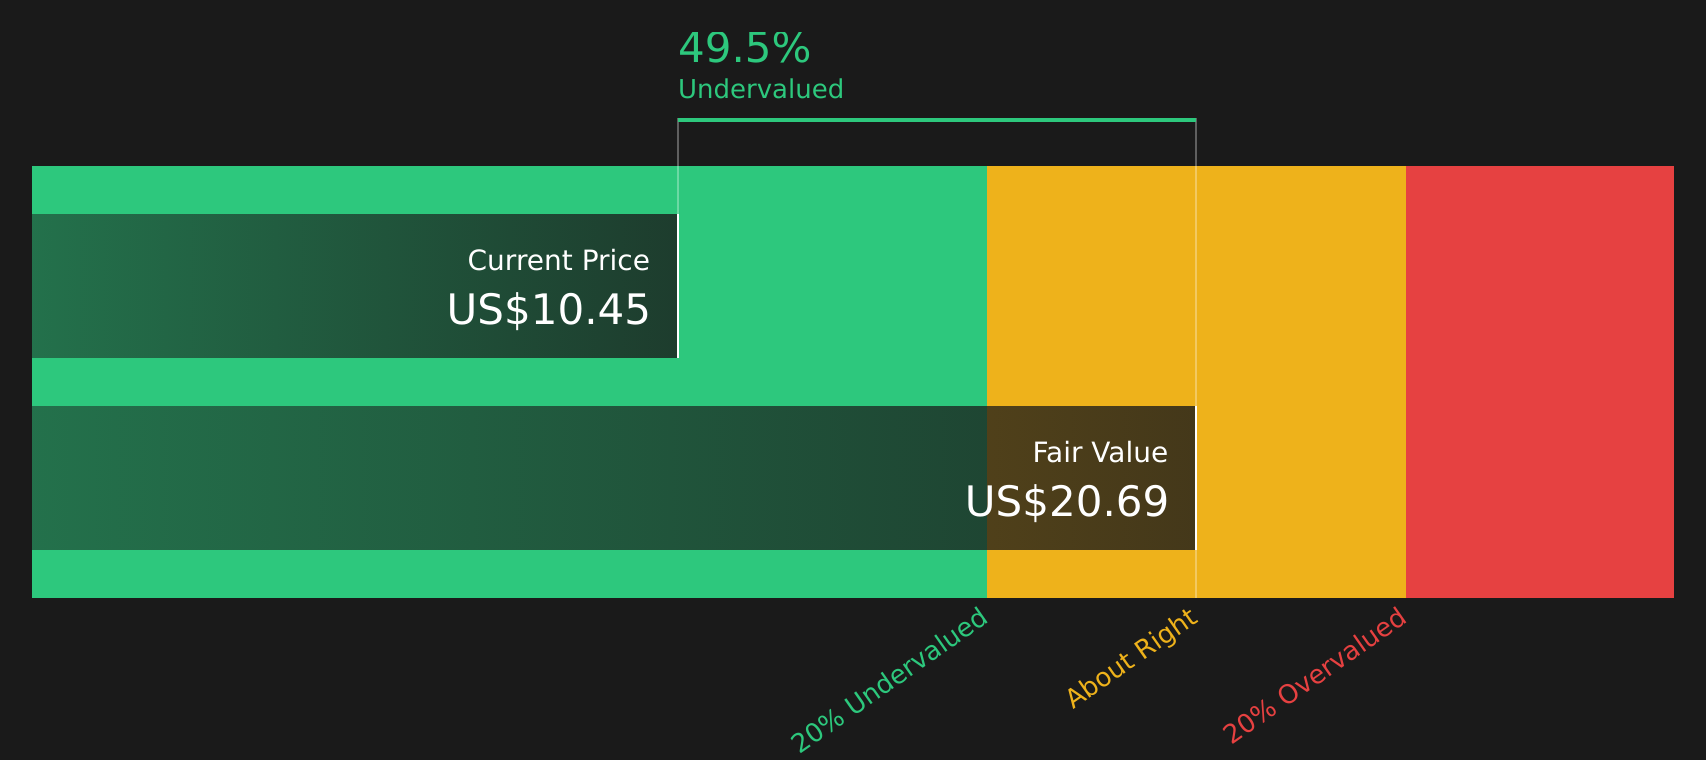
TETRA Technologies (TTI)
Simply Wall St Value Rating: ★★★☆☆☆
Overview: TETRA Technologies operates in the energy sector, providing water and flowback services as well as completion fluids and products, with a market cap of $0.45 billion.
Operations: The company generates revenue primarily from its Water & Flowback Services and Completion Fluids & Products segments, with recent quarterly revenues of $641.83 million. Over the years, the gross profit margin has seen fluctuations, reaching 31.93% in June 2025 before adjusting to 29.58% by June 2026. Operating expenses have been a significant cost factor, averaging around $137 million in recent quarters.
PE: 119.8x
TETRA Technologies, a notable player in the energy services industry, exhibits characteristics of an undervalued small-cap stock. Despite a dip in net profit margin from 19.8% to 1.2%, the company anticipates earnings growth of 55.34% annually, indicating potential for future expansion. Recent insider confidence is evident with share purchases occurring between July and August 2026, suggesting optimism about the company's trajectory. Although reliant on external borrowing for funding, recent quarterly sales increased to US$185.66 million from US$173.87 million year-over-year, reflecting resilience amidst financial challenges.
- Click to explore a detailed breakdown of our findings in TETRA Technologies' valuation report.
Explore historical data to track TETRA Technologies' performance over time in our Past section.
Make It Happen
- Dive into all 67 of the Undervalued US Small Caps With Insider Buying we have identified here.
- Hold shares in these firms? Setup your portfolio in Simply Wall St to seamlessly track your investments and receive personalized updates on your portfolio's performance.
- Invest smarter with the free Simply Wall St app providing detailed insights into every stock market around the globe.
Ready To Venture Into Other Investment Styles?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
- Find companies with promising cash flow potential yet trading below their fair value.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com