
Cui Dongshu: The share of Chinese independent brands in Russia will reach 54.2% in 2026
The Zhitong Finance App learned that Cui Dongshu, Secretary General of the Passenger Link Branch, published an article stating that in 2026, the share of Chinese independent brands in Russia will reach a high level of 54.2%, and sales volume and revenue benefits are good. In 2026, a large number of models from international car companies will enter. German and Japanese companies will perform well, and the advantages of Korean cars will weaken. From January to August 2026, Russian, European and American brands picked up. The main force was the explosion of models imported from Japan and South Korea. The cumulative growth rates of Nissan and Mazda reached 611% and 585% respectively, while Honda, Suzuki, Audi, and Volkswagen also achieved significant growth of more than 200%.
In August 2026, Russian car sales reached 124,000 units, a year-on-year decrease of 8%. In January-August, Russian car sales reached a high level of 920,000 units, an increase of 6% over the previous year. In August 2026, China exported 96,700 vehicles to Russia, and its own brand sold 65,000 vehicles. Local sales volume was 68% of China's exports. In January-August, China exported 638,000 vehicles to Russia, and its own brand sold 500,000 units. Local sales were 78% of China's exports, which is generally relatively balanced.
Chinese car companies are speeding up localized production and supply chain restructuring in Russia, and a number of measures have been taken to improve the situation. The first is to deepen the KD assembly model and establish a regional production base in response to the stepped increase in Russian import tariffs. Avoid tariffs and shorten delivery times through localized production. Build a regional parts center warehouse to increase the localization rate of core components to more than 60% to reduce supply chain risks; secondly, do a good job in product improvement, technology adaptation and special research and development for extremely cold environments. The third is to upgrade the omni-channel after-sales service system. In response to the problem of delayed maintenance response in remote regions of Russia, a three-level network of “central warehouse+mobile service vehicle+authorized repair point” was built to increase service coverage to more than 90%; fourth, brand value reshaping and accurate marketing. Establish a high-end image through technical endorsement and scenario-based marketing, develop a cross-border e-commerce platform between Europe and Asia, provide online matching+offline pick-up services, and use the RMB settlement system to reduce the impact of exchange rate fluctuations.
I. Overall trends in the Russian market
1. Monthly trend of the Russian car market
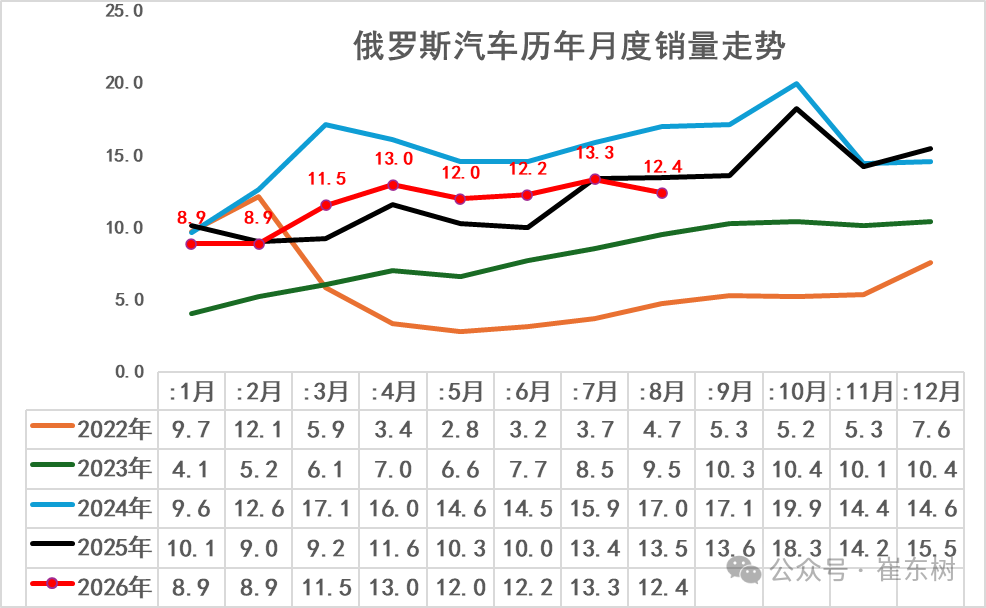
Sales in the Russian car market have fluctuated sharply, and there have been ups and downs in recent years. The monthly trend of the Russian car market in 2021 is relatively stable. In 2022, with the outbreak of the Russian-Ukrainian crisis, monthly sales reached a low level of less than 30,000 vehicles. With strong support from Chinese autonomous car companies, the Russian car market returned to a monthly sales level of around 100,000 vehicles in 2023. In 2024, the Russian car market will return to around 150,000 vehicles. The Russian car market declined significantly in the first half of 2025, and gradually picked up in the second half of the year. The initial sales trend in January-February 2026 was stable, then gradually strengthened. Sales of 124,000 units in August were weaker than the same period in 2025.
2. Annual trends in the Russian car market
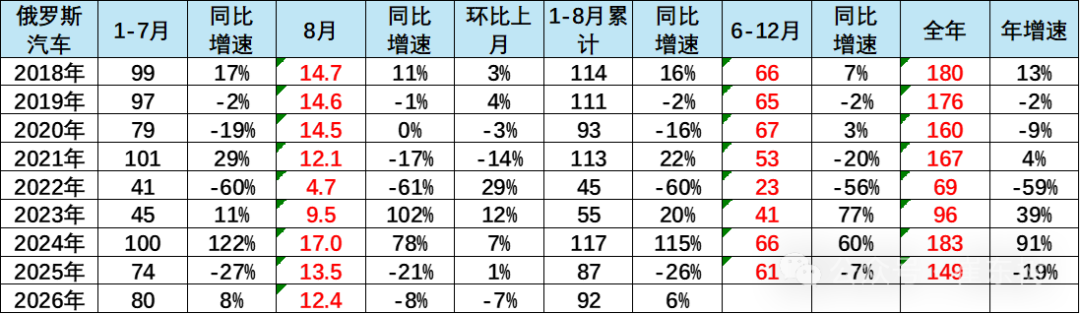
Russia is an established world superpower. With the rise in oil prices before 2008, Russian car sales reached nearly 3 million units; with the 2014 Crimean crisis, the annual sales volume dropped from 2.5 million to 1.5 million; after the 2022 Russian-Ukrainian conflict, sales bottomed out to 687,000 units in 2022; and Russian car sales rebounded to 960,000 units in 2023. With the guaranteed supply of Chinese cars, the overall sales volume of Russian cars in 2024 reached 1.83 million units, an increase of 91% over the previous year, and recently hit a new annual sales high. The cumulative sales volume of the Russian car market in 2025 was 1.49 million vehicles, a decrease of 19% over the previous year. In August 2026, Russian car sales reached 124,000 units, a year-on-year decrease of 8%. In January-August, Russian car sales reached a high level of 920,000 units, an increase of 6% over the previous year.
3. Export and local sales trends of independent brands in the Russian car market
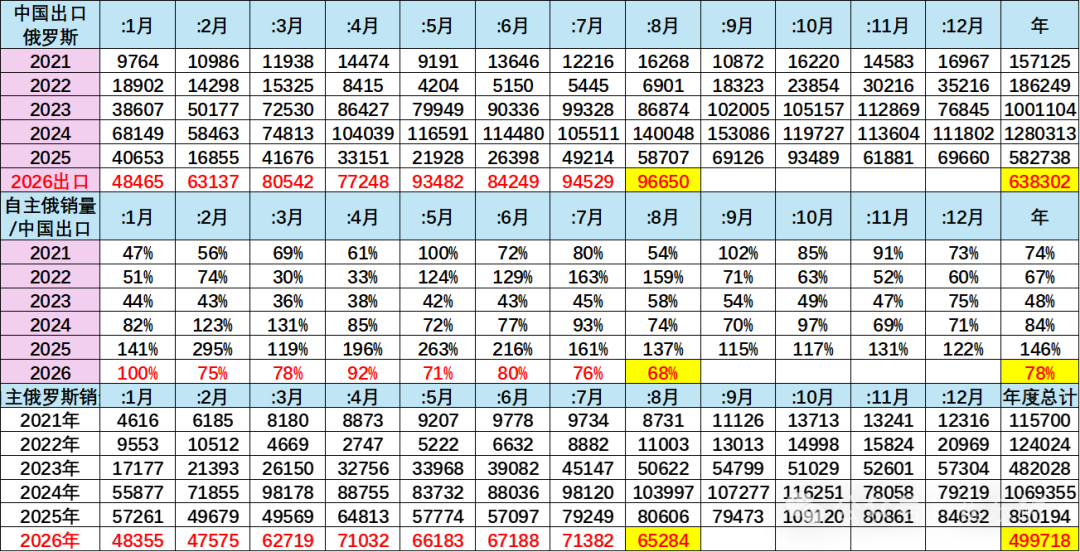
In 2021, Chinese car companies sold only 157,000 vehicles in Russia, and by 2024, 1.28 million vehicles, an increase of 1.12 million units. Strong exports from Chinese car companies are closely linked to gaps and opportunities in the Russian market. In 2025, China exported 583,000 vehicles to Russia, and its own brand sold 85,000 vehicles. Local sales were 146% of China's exports, and finally achieved a sharp trend of inventory removal. In August 2026, China exported 96,700 vehicles to Russia, and its own brand sold 65,000 vehicles. Local sales volume was 68% of China's exports. In January-August, China exported 638,000 vehicles to Russia, and its own brand sold 500,000 units. Local sales were 78% of China's exports, which is generally relatively balanced.
II. Russian Market Structure
1. Market share trends in Russia
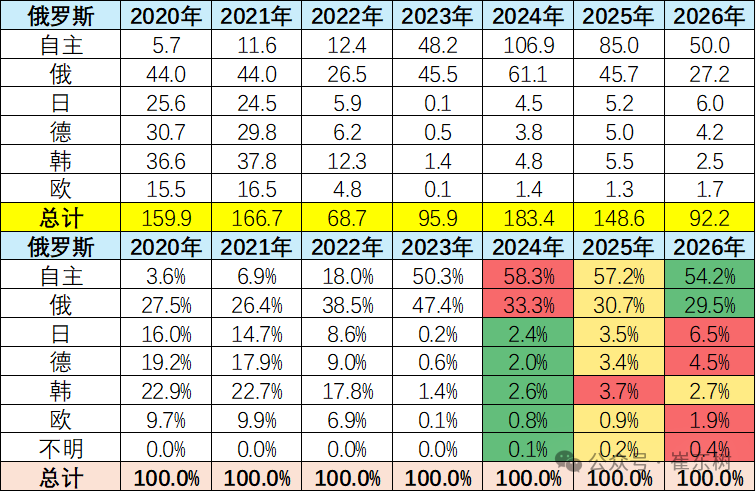
Before the Russian-Ukrainian conflict, the Russian automobile market was occupied by foreign investors for a long time, and the pattern was quite scattered. The main competitors in the Russian car market are European car companies, and Korean cars are relatively better than Japanese cars. The performance of Chinese autonomous car companies is relatively weak, with a share of less than 10%. However, after 2022, many foreign car companies temporarily withdrew and agreed to sell shares to the Russian side. As a result, these joint ventures and foreign car companies switched to the concept of local Russian car companies, so the share of local Russian car companies quickly increased to around 40% in 2023.
At the same time, autonomous car companies have seized the opportunity to quickly fill the gap in the high-end market where European and American car companies have left, reaching a high of 58.3% in 2024. In 2026, the share of Chinese independent brands in Russia reached a high level of 54.2%, and the sales efficiency was good. In 2026, a large number of models from international car companies will enter. German and Japanese companies will perform well, and the advantages of Korean cars will weaken.
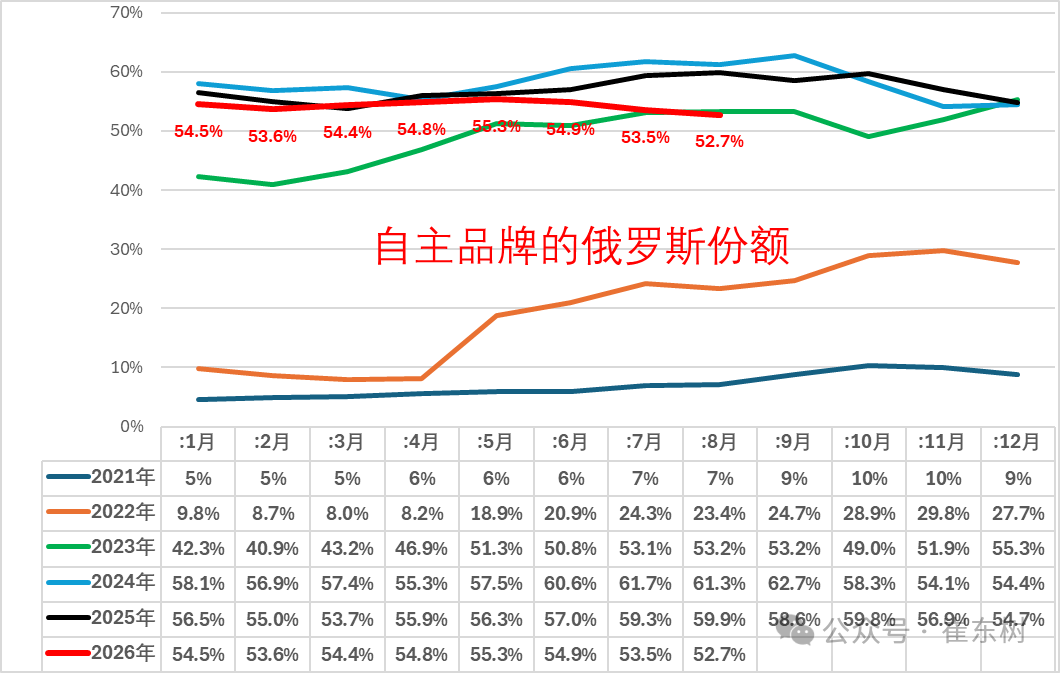
After the Russian-Ukrainian conflict, international car companies successively withdrew from the Russian market due to sanctions and material shortages. Chinese car companies have gradually risen in the Russian market in early 2021, but their share is around 5%; in 2023, Chinese autonomous car companies captured the relatively strong demand in the Russian domestic market and achieved a share of more than 50%; in 2024, the monthly share of independent brands in Russia broke through 60% in the second half of the year, achieving strong growth in Chinese car companies; in 2025, Russia's share of Chinese autonomous car companies rebounded to 57%; heavy trucks plummeted significantly. In August 2026, the share of autonomous car companies in Russia was still 52.7%. Lower level in 2026.
2. Analysis of Russia's new energy demand structure
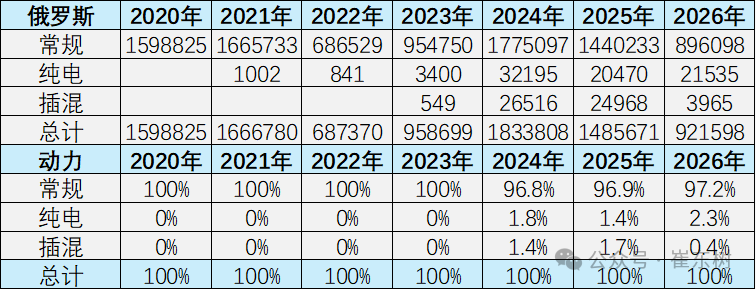
New energy sales in the Russian car market are relatively low. Since European, American, Japanese, and South Korean car companies are relatively poor in new energy, there were very few new energy sources in Russia before 2023. However, with the entry of Chinese car companies, new energy became the favorite of Russia's rich. Pure electric performance was excellent. Later, Ideal and other models sold well in Russia, bringing the characteristics of plug-in hybrid sales higher than pure electric ones in Russia since 2025. The Russian market improved in 2026, and showed a steady recovery of new energy sources in August.
III. Trends in Russian brand structure
1. The trend of major brands in Russia in 2026
0. Russia 1 Russia currently imports cars in three ways: natural person imports, corporate batch imports, and parallel corporate imports. Parallel import policy adjustments benefit the official exports of Chinese car companies, and scrapping tax policy adjustments block the gray channel of low tariffs in neighboring countries. In terms of scrap tax, this year Russia stipulated that if cars are imported from the Eurasian Economic Union (EAEU) countries, the customs fees saved must be paid in Russia in addition to the “scrap tax”, blocking the gray channel of low tariffs in neighboring countries. Parallel import or individual import routes are also gradually being tightened. Starting at the end of 2025, models with more than 160 horsepower will no longer be subject to the low personal import rate (originally about 3,400 rubles), but will have to pay the full commercial tax rate, which can reach 750,000 to 1 million rubles or more. The “power-linked” algorithm introduced in 2026 and the “full compensation” customs clearance formula for Central Asian transit (such as Kyrgyzstan) have further reduced the space for grey trade channels. The sale of Chinese cars in Russia is suitable for mass import by legal entities. Russia prohibits Chinese cars from going through parallel import channels. In fact, it avoids low price competition from unauthorized dealers, which is beneficial to the official export sales of Chinese car companies.
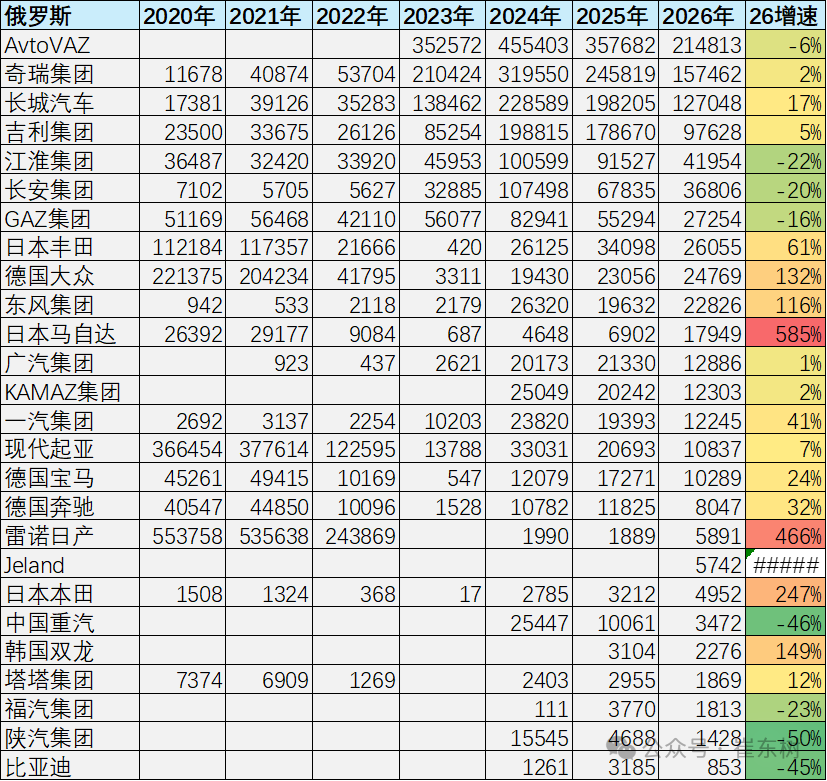
The ideal is to start an official distribution model in Russia soon. JELAND is a local Russian car brand created by the Russian AGR Group in cooperation with Chinese Defetoo. It is essentially Chery Jaecoo (Jetu Traveller series), Omoda (Omoda) bid exchange + Russian localized CKD assembly, produced at the former GM factory in St. Petersburg and the original Volkswagen factory in Kaluga, and officially launched and sold in Russia in 2026. The overall sales volume of international car brands in Russia remains relatively high. The Japanese and Korean brands have performed relatively well, especially Mazda, Hyundai, Kia, and Toyota. The average monthly sales performance of BMW and Mercedes-Benz in 2026 is relatively good, while the performance of other international car companies also has specific sales requirements.
2. The trend of independent brands in Russia
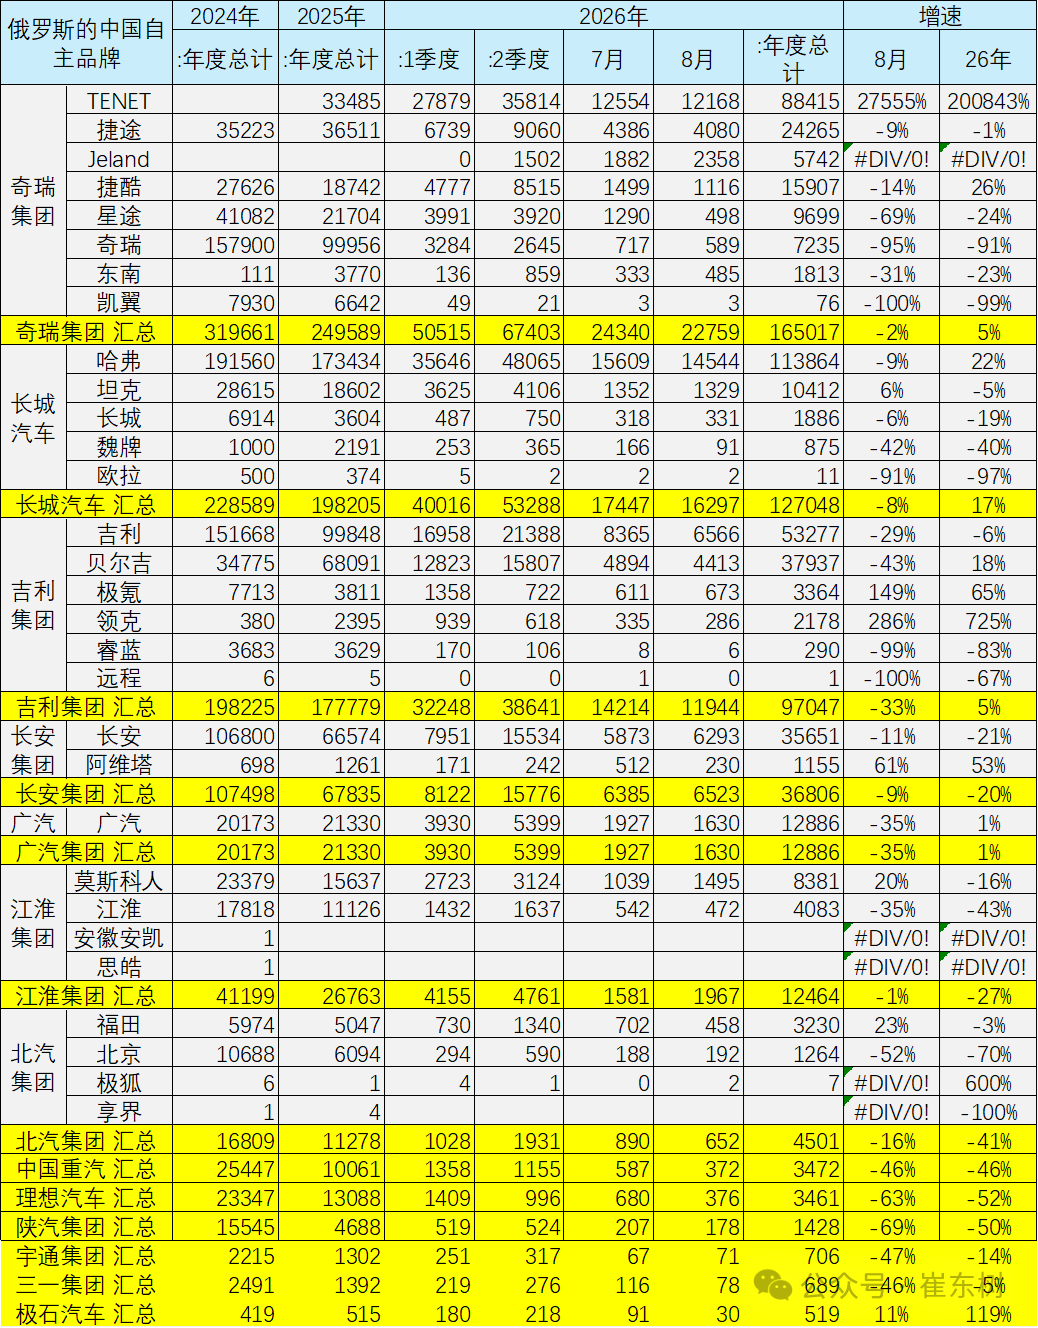
Due to weak technology and product strength, Russian cars are mainly concentrated in the low-end market where the price segment is lower. The first sales champion in the Russian car market was Lada. The best seller was mainly due to its low price and policy protection, which met the needs of Russians for cars. Relying on strong technological improvements and industrial chain advantages, Chinese autonomous car companies are characterized by relatively strong performance in Russia. Chery maintained an average monthly sales volume of nearly 20,000 units in 2026. In particular, Chery (09973) has achieved a good trend of localized production, OEM production, and comprehensive development of imported car portfolios in Russia with multiple brands, and has also achieved the trend of joint development of many children and good fights. Geely's (00175) performance in Russia has also achieved strong growth. Localized OEM products and imported models all performed relatively well. In particular, the performance of products such as Extreme Krypton was also relatively excellent. Other Chinese car companies are also strong, and the performance of products such as BAIC in Russia is also relatively strong.
3. The overall performance of Russian new energy vehicles is good
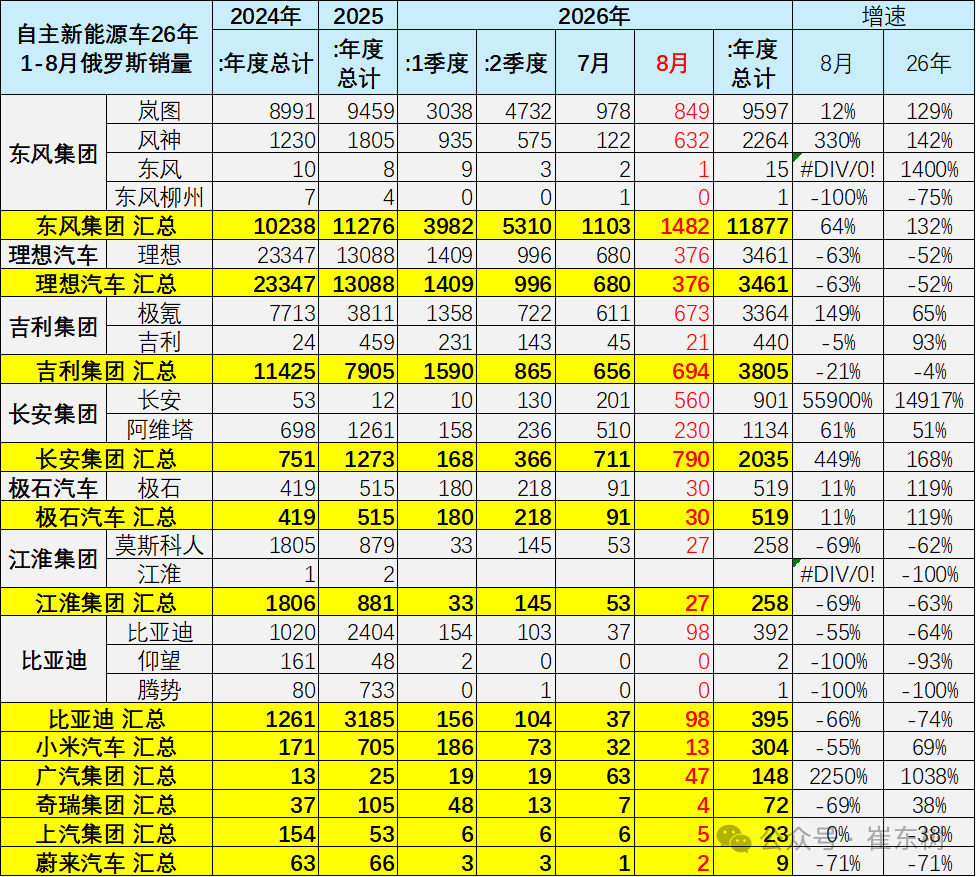
Chinese car brands occupy the middle and high-end market in Russia. Chinese car companies have significant advantages in technology and products. Combined with factors such as tariffs, transportation costs, and dealer sharing, Chinese brand models are more expensive in Russia than domestic ones. Recently, Russia included high-end fuel vehicles and electric vehicles made in China (including the luxury car tax list, covering models with a price of 10 million rubles or more). The overall performance of China's autonomous NEV sales in the Russian car market is good. In particular, high-end models such as extenders and plug-in hybrids in the narrow sense have achieved good performance in replacing European and American luxury cars. Among new energy vehicles, brands such as Ideal, Extreme Krypton, and Rantu have outstanding performance characteristics. However, in the world, brands such as BYD and Xiaomi have also had a certain sales performance. And the latest products, such as Xiaomi, and high-end models with the most intelligent connectivity, also performed well.
4. Russian European and American brands are gradually picking up
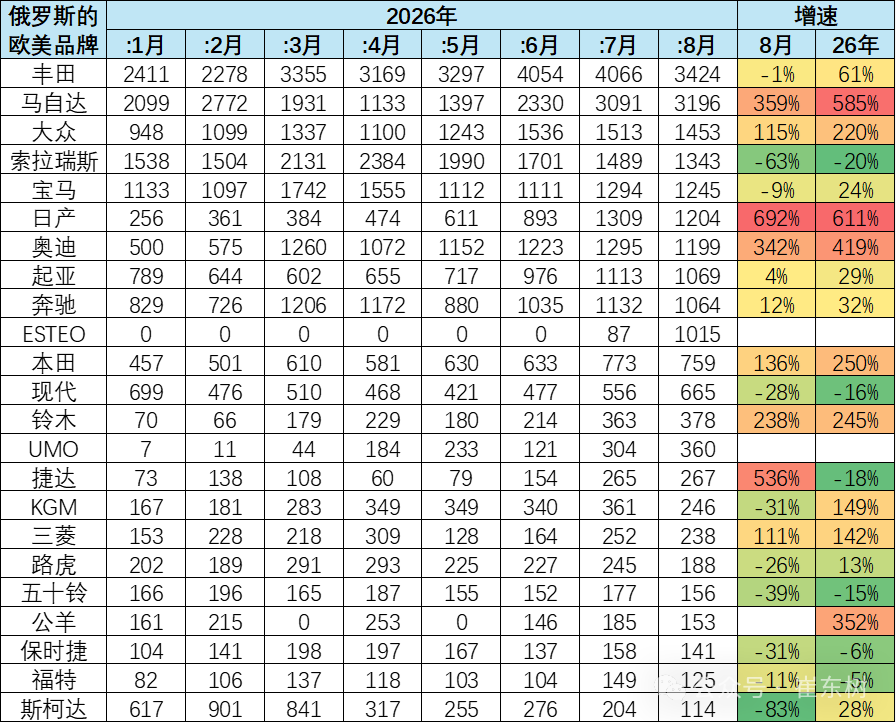
According to Russian overseas brand registration data from January to August 2026, European and American brands are recovering. The main force is actually the explosion of imported models from Japan and South Korea. The cumulative growth rates of Nissan and Mazda reached 611% and 585% respectively. Honda, Suzuki, Audi, and Volkswagen also achieved significant growth of more than 200%. Most of the supply was imported from vehicles produced by Chinese factories through parallel channels; luxury brands such as BMW and Mercedes-Benz were only moderately restored. Russia's AGR Group's JELAND, which relies on the Chery technology platform to exchange bids for localized production, is a typical practice of Chinese car companies' “have more children and fight” overseas. The sales volume of the same group's Solaris (formerly Hyundai platform) continues to be under pressure, and internal product echelons complement each other. Parallel imports fluctuate greatly due to supply and customs clearance. For example, Skoda's sales volume plummeted 83% in August, so it is important to have a base in China.