
Willis Towers Watson (WTW) Partners With Sapien as Undervalued Narrative Stays in Focus
Willis Towers Watson (WTW) just signed an agreement with Sapien Software to integrate AI-driven HR and deal intelligence tools into its Human Capital Divestitures in a Box solution for mid-market M&A activity.
Recent pricing action tells a mixed story for Willis Towers Watson. The share price is down 13.78% over the past month and 11.54% year to date, while the 3 year total shareholder return of 43.32% and 5 year total shareholder return of 27.16% point to a stronger longer run record. As a result, the latest AI focused partnerships may be landing against a backdrop of fading short term momentum rather than a break in the longer trend.
See how Willis Towers Watson's AI initiatives compare with other data driven insurers by reviewing our curated list of 90 AI infrastructure stocks.
For Willis Towers Watson, a double digit pullback sits opposite a longer record of solid total returns and fresh AI deals. Does that recent slide still leave enough upside in the valuation to reward new risk today?
Most Popular Narrative: 24% Undervalued
At a last close of $288.61 compared with a widely followed fair value view of about $378.58, Willis Towers Watson is framed as materially undervalued, with that gap linked directly to how much of its AI and automation plan ultimately translates into earnings strength.
Acceleration of the Propel AI Acceleration Plan, which targets about US$400m in run-rate savings and higher enterprise and segment margin levels by 2028, could lift Willis Towers Watson’s adjusted operating margin profile and support higher earnings power.
Find out how 7 investors see Willis Towers Watson as 24% undervalued.
Result: Fair Value of $378.58 (UNDERVALUED)
Still, the Willis Towers Watson narrative can be knocked off course if insurance pricing continues to soften or if AI driven tools end up compressing fees.
Find out about the key risks to this Willis Towers Watson narrative.
Another View: Willis Towers Watson Through The P/E Lens
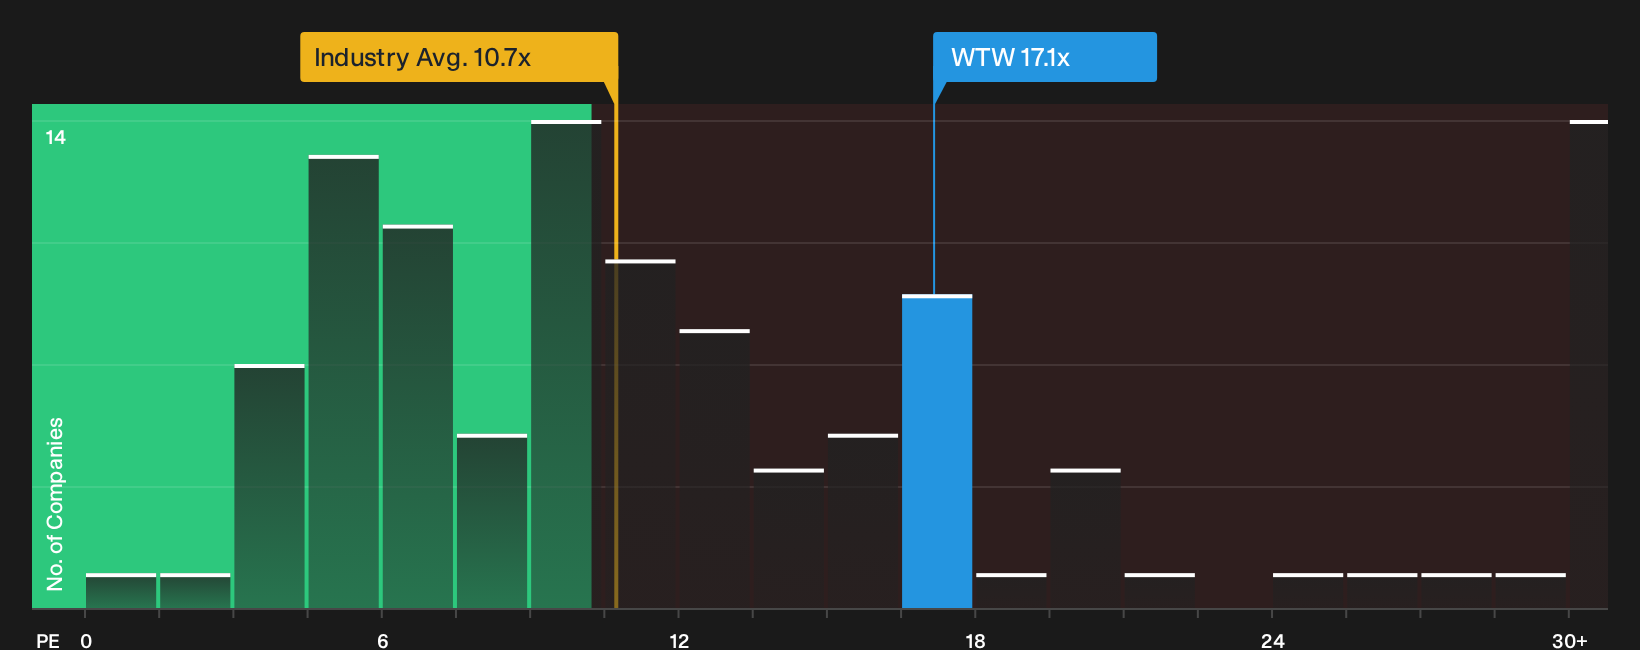
The fair value narrative paints Willis Towers Watson as undervalued, yet the market multiple tells a different story. At a P/E of 17.1x versus a US Insurance industry average of 10.7x and a fair ratio of 12.6x, the stock trades on a richer earnings tag that could compress if sentiment cools.
Investors weighing that richer P/E against the wider analyst target range may want to stress test their own assumptions on margins, AI execution and fee pressure before deciding which signal to trust most.See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on Willis Towers Watson can be confusing, so it may be helpful to act promptly and review the figures, risks and upside yourself with 4 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Willis Towers Watson?
Do not stop with Willis Towers Watson. Use the Simply Wall Street Screener to spot fresh opportunities that match how you like to invest.
- Target income today and potential resilience over time by scanning for companies that meet your yield and stability preferences through 7 dividend fortresses.
- Hunt for mispriced quality by lining up valuation, cash flows and balance sheet strength using the focused view in 31 high quality undervalued stocks.
- Prioritise capital protection first by filtering for businesses that clear stricter financial health checks with 31 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com